

FHA Loan Down Payment Guide: How Low Can You Really Go? For most borrowers, the answer is 3.5% of the home’s purchase price if the borrower has a qualifying credit score of 580 or higher. Borrowers with scores from 500 to 579 generally need at least 10% down under FHA rules.
That does not mean you need to have the entire amount sitting in your checking account today. Eligible gift funds and approved down payment assistance programs may help cover some or all of the required investment, while seller contributions may help with eligible closing costs.
The important part is understanding the difference between the minimum FHA down payment and the amount of cash you actually need to close.
In this guide, we will break down the numbers, explain the credit score rules, show real dollar examples, and look at when putting more than 3.5% down may make sense.
How Low Can an FHA Loan Down Payment Go?
For a standard FHA purchase loan, the minimum required down payment is generally:
| Credit Score | Minimum Down Payment |
|---|---|
| 580 or higher | 3.5% |
| 500 to 579 | 10% |
| Below 500 | Generally not eligible for FHA insurance |
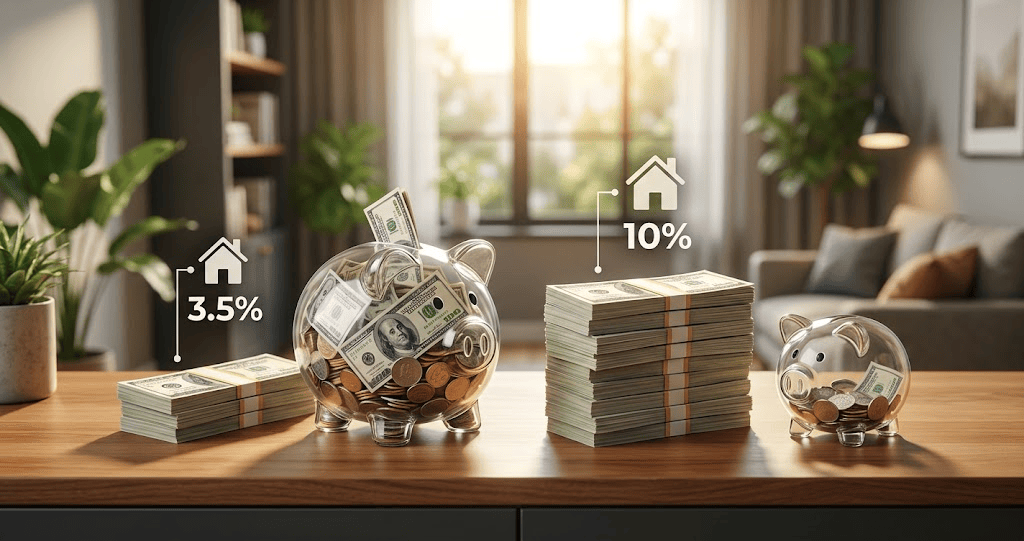
The 3.5% figure is the number most buyers associate with FHA financing. However, 3.5% is not a universal requirement for every FHA borrower. Your credit score matters.
HUD’s FHA policy has long used the two tier structure: borrowers with scores of 580 or higher can qualify for maximum financing, while borrowers in the 500 to 579 range are limited to 90% loan to value, which means a 10% minimum investment.
Also remember that FHA sets program requirements, while individual lenders can apply their own underwriting standards. A lender may require a higher credit score or additional documentation even when FHA guidelines permit a lower score.
What does 3.5% down actually mean?
It is simply 3.5% of the purchase price.
For example:
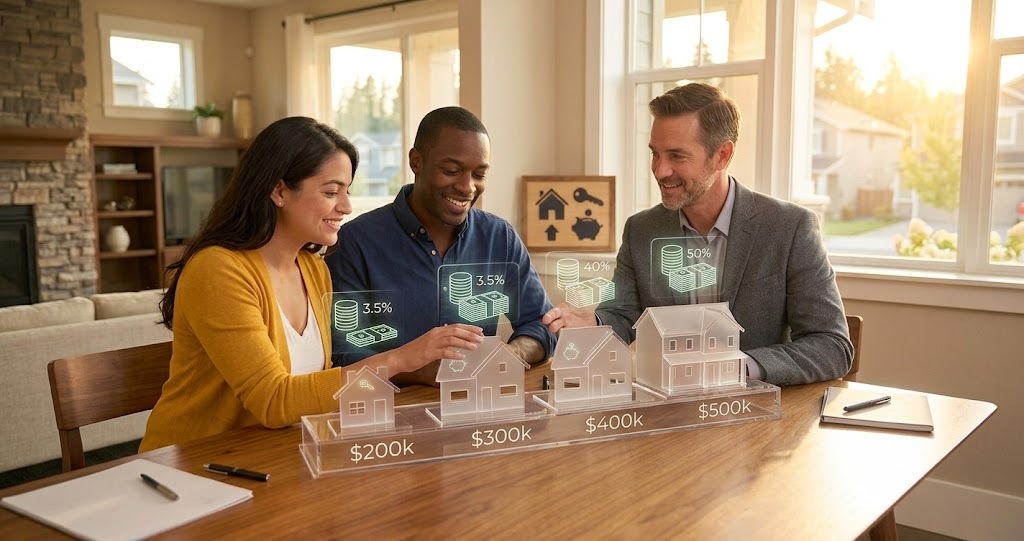
- $200,000 home = $7,000
- $250,000 home = $8,750
- $300,000 home = $10,500
- $350,000 home = $12,250
- $400,000 home = $14,000
- $500,000 home = $17,500
This is one of the biggest practical advantages of FHA financing. A buyer does not have to wait until they have 20% saved.
FHA Loan Down Payment Guide: Your Down Payment Is Not Your Total Cash to Close
This is where many first time buyers misunderstand FHA financing.
If you purchase a $300,000 home and put 3.5% down, your required down payment is $10,500. But you may still have other costs, including closing costs, prepaid expenses, escrow funding, and mortgage insurance.
Fairway notes that closing costs can add several percentage points to the transaction, while Neighbors Bank similarly emphasizes that down payment and closing costs should be considered separately.
FHA upfront mortgage insurance
Most FHA loans also require an upfront mortgage insurance premium, commonly called UFMIP.
HUD currently lists the standard upfront premium for most FHA purchase and refinance mortgages at 1.75% of the base loan amount. In many transactions, borrowers finance this premium into the mortgage rather than paying it entirely in cash at closing.
There is also an annual mortgage insurance premium that is generally collected through monthly payments. The amount and duration depend on factors such as the loan term, loan amount, and loan to value ratio.
That means a buyer should not think:
“I need only 3.5%, so I need exactly 3.5% of the purchase price in my bank account.”
A better question is:
“How much cash will I need to bring to closing after credits, assistance, financed costs, and other expenses are considered?”
That distinction can make your home buying budget much more realistic.
Can You Get an FHA Loan With 500 to 579 Credit?
Yes, FHA guidelines can allow borrowers with credit scores from 500 to 579, but the minimum required investment is generally 10% rather than 3.5%.
For example, imagine two buyers purchasing the same $250,000 home:
Buyer A:
Credit score: 620
Down payment: 3.5%
Required down payment: $8,750
Buyer B:
Credit score: 560
Down payment: 10%
Required down payment: $25,000
The difference is $16,250.
That is why improving your credit before applying can sometimes have a much bigger impact than simply trying to save more money.
However, do not assume a 580 score automatically guarantees approval. Lenders still evaluate income, employment, debts, assets, credit history, property eligibility, and other underwriting factors.
A practical strategy for lower credit scores
If your score is below 580, compare two paths:
- Save toward the 10% FHA requirement.
- Work on your credit profile and see whether you can qualify for the 3.5% tier later.
The better choice depends on your timeline, financial situation, debt profile, and lender requirements.
Can Gift Money Pay the FHA Down Payment?
Yes. Eligible gift funds can be used toward an FHA borrower’s required investment when they meet FHA documentation and donor requirements. HUD’s rules allow certain approved donors, and the money must genuinely be a gift rather than an undisclosed loan.
Potential gift sources can include:
- Eligible relatives
- Employers or labor unions
- Close friends under applicable FHA rules
- Approved charitable or down payment assistance sources
The documentation matters.
A lender may require a gift letter confirming that the funds do not need to be repaid, along with evidence showing where the money came from and how it was transferred.
What about borrowing your down payment?
This is an important distinction.
You generally cannot simply take out a personal loan and tell the lender it is your down payment. New debt can affect your debt to income ratio and underwriting.
If someone gives you money, document it correctly. If someone lends you money, disclose it.
Trying to disguise borrowed money as a gift can create a serious underwriting problem.
Can Down Payment Assistance Reduce Your FHA Cash Requirement?
Yes. Down payment assistance, or DPA, can potentially reduce the amount of your own money needed for an FHA purchase.
Programs vary significantly by state, county, city, income, property, and borrower circumstances. Assistance may come in forms such as:
- Grants
- Forgivable second loans
- Deferred payment loans
- Low interest second mortgages
- Matching savings programs
Fairway notes that assistance programs can have different eligibility rules, and HUD recommends checking available resources in your area.
The key is not to assume that every advertised “down payment assistance” program is free money.
Before accepting assistance, ask:
- Is it a grant or a loan?
- Does it have to be repaid?
- When does repayment begin?
- Is there an occupancy requirement?
- What happens if you refinance or sell?
- Does the program have income limits?
- Does the program have purchase price limits?
Can the Seller Pay Your FHA Down Payment?
This is another area where buyers often get confused.
A seller generally cannot simply hand you money and label it as your FHA down payment. However, eligible seller concessions can help cover certain closing costs and other allowable expenses.
Bankrate reports that FHA seller concessions can be up to 6% of the purchase price, subject to FHA rules and the actual eligible costs involved.
For example, on a $300,000 home, 6% equals $18,000.
But that does not mean you automatically receive an $18,000 cash payment.
The money is used for allowable transaction costs. If your eligible costs are lower than the concession amount, you generally cannot pocket the unused difference as cash.
This is why buyers should distinguish between:
Down payment assistance and closing cost assistance.
They solve different problems.
Should You Put More Than 3.5% Down on an FHA Loan?
Not necessarily.
Putting more down reduces the amount you borrow, which can lower your principal and interest payment. It can also affect FHA mortgage insurance costs and, depending on the loan structure, how long annual MIP remains. HUD’s current MIP framework shows that mortgage insurance pricing depends on loan term, loan amount, and loan to value.
But there is a tradeoff.
Suppose you have $30,000 available for your home purchase.
You could put:
$10,500 down on a $300,000 home and retain roughly $19,500 before accounting for closing costs and other expenses.
Or you could put $30,000 down and have far less cash available after closing.
The second option gives you more initial equity, but the first could leave you with a stronger emergency reserve.
The overlooked question: How much cash will remain?
In real mortgage planning, the strongest down payment is not always the largest possible down payment.
A buyer who empties their savings account to increase their down payment may have less money available for:
- Emergency repairs
- Moving expenses
- Home maintenance
- Insurance deductibles
- Job interruptions
- Unexpected household expenses
Original practical insight: If increasing your down payment by $10,000 saves you only a modest amount each month but leaves you without an emergency reserve, the financial tradeoff may not be attractive. The right comparison is not just “lower mortgage balance versus higher mortgage balance.” It is lower mortgage balance versus liquidity after closing.
That is a more useful way to evaluate an FHA down payment.
FHA vs. Conventional, VA, and USDA Down Payments
FHA is not automatically the cheapest option for every buyer.
A quick comparison:
| Loan Type | Potential Minimum Down Payment | Key Consideration |
| FHA | 3.5% | Flexible credit guidelines, FHA mortgage insurance |
| Conventional | As low as 3% for eligible programs | PMI may be removable |
| VA | 0% | Available to eligible veterans and service members |
| USDA | 0% | Geographic and income requirements apply |
Conventional programs can offer a lower minimum down payment than FHA for qualified borrowers. VA and USDA financing can potentially eliminate the down payment altogether for eligible buyers.
So if you qualify for VA or USDA financing, it is worth comparing those programs before automatically choosing FHA.
How to Build Your FHA Down Payment Faster
If you need to save the money yourself, focus on the target rather than the abstract idea of “saving for a house.”
For a $300,000 home, your 3.5% target is $10,500.
If you want to save that amount in 12 months:
$10,500 ÷ 12 = $875 per month
For 18 months:
$10,500 ÷ 18 = about $584 per month
This turns a large goal into a monthly number.
You can then combine strategies:
- Automate a fixed transfer after every paycheck.
- Direct bonuses or tax refunds into the home fund.
- Reduce large recurring expenses before cutting small purchases.
- Consider a less expensive property.
- Research state and local DPA programs.
- Protect your credit while saving.
- Keep documentation for large deposits and gift funds.
A lower home price can also make a meaningful difference. At 3.5%, reducing a purchase price by $50,000 reduces the required down payment by $1,750.
That may be more realistic than trying to find another $10,000 in savings.
FHA Down Payment Checklist for 2026
Before you make an offer, work through these questions:
- Is your credit score at least 580 for the 3.5% tier?
- If your score is 500 to 579, have you planned for 10% down?
- Have you estimated closing costs separately from the down payment?
- Have you accounted for FHA mortgage insurance?
- Are your gift funds properly documented?
- Have you checked state and local DPA programs?
- Have you compared FHA with conventional financing?
- If eligible, have you compared VA or USDA financing?
- Will you still have emergency savings after closing?
- Has a lender reviewed your income, debts, assets, and proposed property?
Final Answer: How Low Can You Really Go?
For most FHA borrowers who meet the credit requirements, the minimum down payment is 3.5%. Borrowers with credit scores from 500 to 579 generally need 10% down under FHA rules.
But the smartest FHA strategy is not simply finding the smallest possible down payment.
You should calculate your total cash to close, investigate assistance and eligible gift funds, account for mortgage insurance and closing costs, and decide how much emergency savings you want to keep after buying.
A 3.5% down payment can make homeownership accessible sooner. A larger down payment can reduce borrowing and potentially lower long term costs. Neither choice is automatically best.
The right number is the one that helps you buy a home without leaving your finances dangerously short of cash afterward.
FAQ Section
What is the minimum FHA loan down payment in 2026?
The minimum is generally 3.5% for borrowers with a qualifying credit score of 580 or higher. Borrowers with scores from 500 to 579 generally need 10% down. Individual lenders may impose additional requirements.
Can I get an FHA loan with 500 credit score?
FHA guidelines can allow borrowers with credit scores from 500 to 579, but a 10% minimum down payment generally applies. A score below 500 generally does not meet FHA’s minimum credit requirement. Lender requirements can be stricter.
Can someone else pay my FHA down payment?
Eligible gift funds and certain down payment assistance programs can help cover the required investment. Gift funds must meet FHA requirements and be properly documented.
Can FHA down payment assistance cover closing costs too?
Some assistance programs can help with both down payment and closing costs, but program rules vary. Seller concessions may also help with eligible closing costs, subject to FHA limits and requirements.
Is 3.5% down always better than putting 10% down?
No. A larger down payment reduces the loan balance and can affect mortgage insurance costs, but it also uses more of your available savings. Compare the monthly savings with the emergency cash you would have remaining after closing.
Do FHA loans require mortgage insurance?
Yes. Most FHA loans require an upfront mortgage insurance premium and an annual mortgage insurance premium collected through monthly payments. HUD currently lists the standard upfront premium at 1.75% of the base loan amount for most FHA purchase and refinance mortgages.






