

Learn about FHA loan down payment 2026 requirements, 3.5% options, credit score rules, gift funds, and how to qualify for an FHA home loan today.
FHA Loan Down Payment 2026: 3.5% Options Explained
Buying a home is one of the biggest financial decisions you will ever make. If saving for a large down payment feels difficult, an FHA loan could make homeownership more accessible. In 2026, many buyers continue to choose FHA loans because they offer a lower down payment requirement and more flexible qualification standards than many conventional loans.
This guide explains how the FHA loan down payment works, who qualifies for the 3.5% option, and what you should know before applying. Whether you are buying your first home or returning to the housing market, understanding your options can help you make a confident decision.
What Is an FHA Loan?
An FHA loan is a mortgage that is insured by the Federal Housing Administration. These loans are designed to help borrowers qualify for financing with a lower down payment and more flexible credit requirements.
Many buyers choose FHA financing because it allows them to purchase a home without saving a large amount of money upfront.
Benefits of an FHA Loan
- Down payment as low as 3.5%
- Flexible credit requirements
- Competitive interest rates
- Gift funds may be used for the down payment
- Available for many primary residences
FHA Loan Down Payment 2026 Requirements
The biggest advantage of an FHA loan is the low down payment requirement.
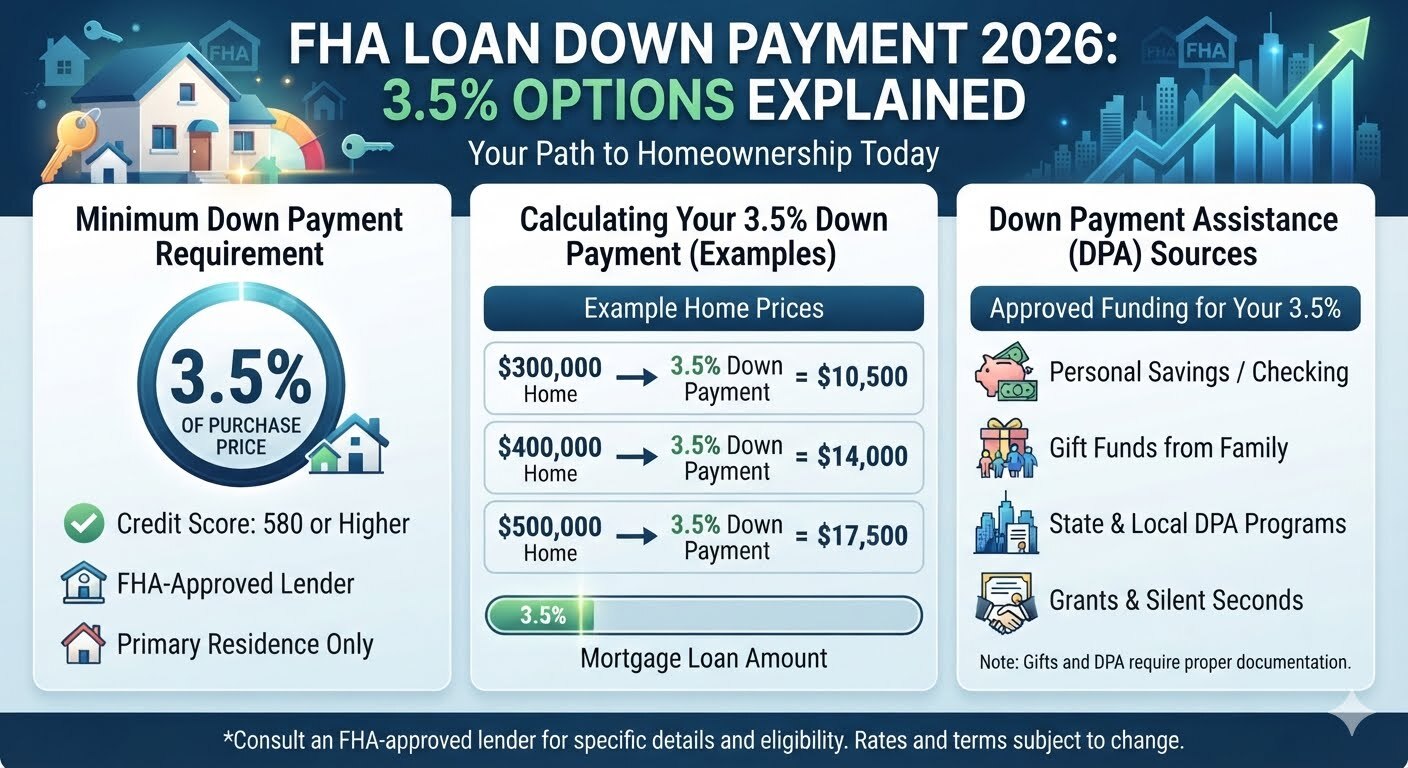
If you qualify, you may only need to put down 3.5% of the home’s purchase price.
For example:
| Home Price | Down Payment at 3.5% |
|---|---|
| $250,000 | $8,750 |
| $300,000 | $10,500 |
| $400,000 | $14,000 |
| $500,000 | $17,500 |
Compared with larger down payment requirements on many other loan types, this can make buying a home much more affordable.
Who Qualifies for the 3.5% Down Payment?
To qualify for the 3.5% down payment option, borrowers generally need to meet FHA lending requirements.
These often include:
Credit Score
Many lenders allow the 3.5% down payment for borrowers with a qualifying credit score that meets FHA guidelines.
Stable Income
Lenders want to see reliable income that demonstrates your ability to repay the mortgage.
Employment History
A steady employment record helps strengthen your application.
Debt to Income Ratio
Your monthly debt compared to your income should fall within acceptable lender guidelines.
Can You Use Gift Funds?
Yes.
One of the biggest advantages of an FHA loan is that family members and certain approved sources can provide gift funds for your down payment and closing costs.
This allows many buyers to purchase a home without using all of their personal savings.
Always keep documentation showing that the money is a genuine gift and not a loan.
Can You Get Down Payment Assistance?
Many state and local housing agencies offer down payment assistance programs.
These programs may provide:
- Grants
- Forgivable loans
- Low interest loans
- Closing cost assistance
Eligibility depends on your income, location, and home purchase price.
If you qualify, combining an FHA loan with down payment assistance may significantly reduce your upfront costs.
FHA Loan Credit Requirements
Although FHA loans are known for flexible credit standards, lenders still evaluate your financial history.
Factors they review include:
- Credit score
- Payment history
- Existing debts
- Income stability
- Employment record
Improving your credit before applying may help you receive better loan terms.
Other Costs to Expect
Your down payment is only one part of buying a home.
You should also plan for:
Closing Costs
These may include lender fees, title fees, appraisal costs, and recording fees.
Mortgage Insurance
FHA loans require mortgage insurance, which helps protect lenders if a borrower defaults.
Home Inspection
Although not always required by every lender, a home inspection is strongly recommended before purchasing a property.
Moving Expenses
Budget for moving, utility setup, and other expenses after closing.
FHA Loan vs Conventional Loan
Many buyers compare FHA loans with conventional mortgages before making a decision.
| FHA Loan | Conventional Loan |
|---|---|
| Down payment as low as 3.5% | May require a larger down payment depending on the loan |
| Flexible credit guidelines | Often stricter credit requirements |
| Mortgage insurance required | Mortgage insurance depends on the loan and equity |
| Popular with new home buyers | Popular with buyers who have stronger credit |
Choosing the right mortgage depends on your financial situation, savings, and long term goals.
Tips Before Applying
Preparing ahead of time can improve your chances of approval.
Save More Than the Minimum
Even if you qualify for a 3.5% down payment, additional savings can help cover closing costs and unexpected expenses.
Check Your Credit
Review your credit report and correct any errors before applying.
Reduce Existing Debt
Lower monthly debt can improve your borrowing power.
Compare Multiple Lenders
Different lenders may offer different interest rates, fees, and loan programs.
Get Preapproved
A mortgage preapproval shows sellers that you are a serious buyer and helps you understand your budget before shopping for a home.
Why FHA Loans Remain Popular in 2026
Housing affordability continues to be a major concern for many buyers. FHA loans remain one of the most popular financing options because they make homeownership possible with a relatively small down payment.
Combined with flexible qualification standards and available down payment assistance programs, FHA financing continues to help many families achieve their goal of owning a home.
Conclusion
The FHA loan down payment 2026 program continues to provide an affordable path to homeownership for qualified buyers. With a minimum down payment of just 3.5%, flexible credit guidelines, and the ability to use gift funds or down payment assistance, FHA loans remain one of the best choices for many home buyers.
Before choosing a mortgage, compare lenders, review your finances carefully, and understand all costs involved. With proper planning, you can move closer to purchasing the home that fits your needs and budget.
Frequently Asked Questions
1. What is the minimum FHA loan down payment in 2026?
Qualified borrowers may be eligible for a down payment as low as 3.5% of the home’s purchase price.
2. Can I use gift money for an FHA down payment?
Yes. Eligible gift funds from approved sources may be used for the down payment and, in some cases, closing costs.
3. Are FHA loans only for new home buyers?
No. FHA loans are available to eligible buyers who meet program requirements, even if they have owned a home before.
4. Do FHA loans require mortgage insurance?
Yes. FHA loans require mortgage insurance according to FHA program rules.
5. Can I combine an FHA loan with down payment assistance?
Yes. Many buyers qualify for state or local down payment assistance programs alongside an FHA loan.
6. Is it possible to buy a home with limited savings?
Yes. FHA financing, gift funds, and assistance programs can help reduce the amount of cash needed at closing.
7. How do I improve my chances of FHA loan approval?
Maintain steady income, reduce debt, improve your credit profile, save for closing costs, and obtain mortgage preapproval before house hunting.






