

FHA Loan vs Conventional Loan is one of the most important comparisons for homebuyers who are deciding how to finance a home in 2026. The right choice depends less on which loan is “better” and more on your credit profile, available cash, debt, property, and how long you expect to keep the mortgage.
An FHA loan can make sense when you need flexible credit and down payment requirements. A conventional loan is often more attractive when you have stronger credit, lower debt, and enough savings to qualify for favorable pricing and potentially remove PMI later.
Both options can help you buy a home with a relatively small down payment, but their mortgage insurance rules, underwriting requirements, property standards, and long term costs can be very different.
FHA Loan vs Conventional Loan: What Is the Difference?
An FHA loan is insured by the Federal Housing Administration and issued by an FHA approved lender. FHA financing is designed to make homeownership accessible to borrowers who may not qualify as easily for conventional financing.
A conventional loan is not part of a specific federal government mortgage insurance program. Many conventional conforming loans are eligible for purchase or backing through Fannie Mae or Freddie Mac. The Consumer Financial Protection Bureau notes that conventional loans can cost less than FHA loans but can also be more difficult to qualify for.
The important distinction is not simply government backed versus conventional. The real question is how the loan’s requirements affect your total monthly payment and total borrowing cost.
Quick comparison
| Feature | FHA Loan | Conventional Loan |
|---|---|---|
| Typical minimum down payment | 3.5% with qualifying credit | As low as 3% for some programs |
| Credit flexibility | More flexible | Generally stronger credit profile preferred |
| Mortgage insurance | Upfront and annual MIP | PMI generally required below 20% down |
| PMI or MIP removal | Depends on FHA insurance terms | PMI can generally be canceled under applicable rules |
| Property use | Primary residence | Primary, second home, and some investment uses |
| Appraisal standards | FHA property requirements apply | Generally more flexible |
| 2026 one unit loan limit | $541,287 floor to $1,249,125 ceiling depending on location | $832,750 baseline, up to $1,249,125 in high cost areas |
| Best suited to | Buyers needing more qualification flexibility | Buyers with stronger overall finances |
These are general guidelines. Individual lenders can impose additional requirements.
FHA Loan vs Conventional Loan: Credit Score and Down Payment
Your credit score and available savings can quickly narrow the decision.
FHA credit and down payment requirements
FHA guidelines allow a 3.5% down payment for borrowers with a qualifying credit score of 580 or higher. Borrowers with scores from 500 to 579 generally need at least 10% down under FHA’s standard requirements. Lenders may apply their own underwriting standards.
That flexibility is one reason FHA financing can be useful for buyers who have limited savings or a credit history that does not fit conventional underwriting as comfortably.
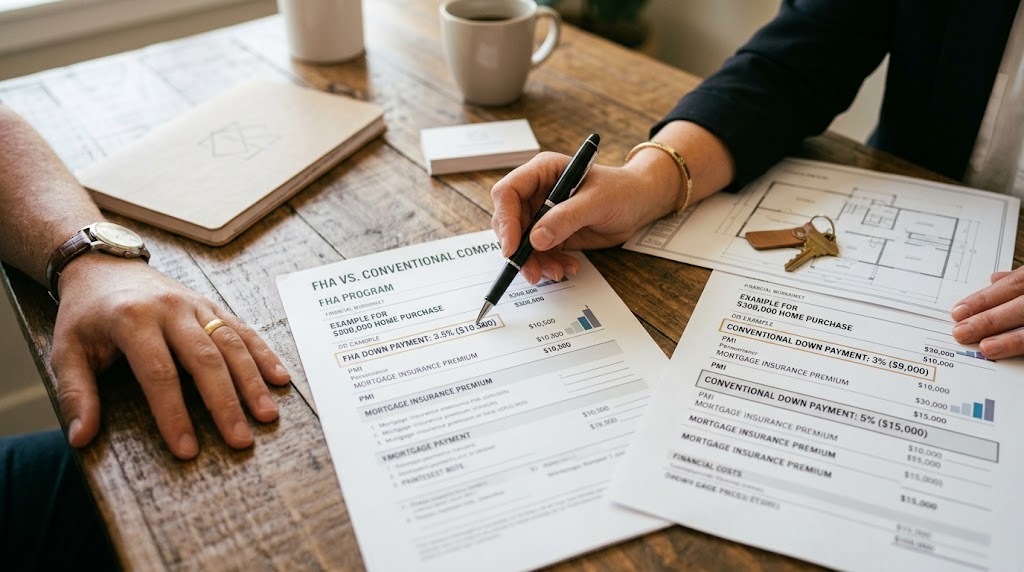
For example, on a $300,000 home:
- 3.5% down = $10,500
- 10% down = $30,000
- 20% down = $60,000
Remember that the down payment is only part of the cash needed to buy. Closing costs, prepaid taxes, insurance, inspections, and other expenses can also affect your cash to close.
Conventional credit and down payment requirements
Some conventional programs permit down payments as low as 3%. However, approval depends on the entire borrower profile, including credit, income, assets, debt, property characteristics, and loan type.
A strong credit profile can make conventional financing particularly attractive because pricing and mortgage insurance costs may improve as borrower risk decreases.
Original practical insight: Do not compare FHA and conventional loans by looking only at the minimum down payment. A buyer with $15,000 available may technically qualify for both, but the loan with the smaller required down payment is not automatically the cheaper loan over five or ten years.
Mortgage Insurance: FHA MIP vs Conventional PMI
Mortgage insurance is one of the biggest differences between the two programs.
How FHA mortgage insurance works
FHA loans generally require an upfront mortgage insurance premium and an annual mortgage insurance premium. The upfront premium has historically been 1.75% of the base loan amount for standard FHA single family financing.
The upfront premium can generally be financed into the mortgage rather than paid entirely from your savings.
The annual MIP is then included in your monthly housing payment. How long you pay it depends in part on the original loan to value ratio and other loan characteristics.
This creates an important long term consideration. A low FHA interest rate does not necessarily mean the FHA loan has the lowest total cost.
How conventional PMI works
Conventional borrowers who put less than 20% down will often have private mortgage insurance. PMI protects the lender against losses and increases the borrower’s monthly cost.
One major advantage is that PMI can generally be canceled once the borrower meets applicable equity requirements. Under federal rules, borrowers can generally request cancellation when the principal balance reaches 80% of the home’s original value, subject to applicable conditions. Automatic termination generally occurs at 78% of original value if the borrower is current.
Which mortgage insurance is better?
For borrowers who expect to build equity relatively quickly, conventional PMI can be more flexible.
For borrowers whose credit profile makes conventional financing expensive or difficult to obtain, FHA MIP can still produce a better overall approval and payment structure.
That is why you should compare monthly payment, upfront costs, insurance, interest rate, and expected time in the loan together.
FHA vs Conventional: Interest Rates and Total Cost
Many borrowers make the mistake of choosing the mortgage with the lowest advertised interest rate.
That can be misleading.
Mortgage pricing depends on the borrower, lender, loan amount, property, credit profile, down payment, loan term, market conditions, and other factors. An FHA rate can be lower than a conventional rate in one scenario while the conventional loan still produces the lower total cost.
Consider a simplified example:
A buyer compares two $300,000 purchase scenarios. The FHA option offers a lower interest rate, but the loan includes FHA mortgage insurance. The conventional option has a somewhat higher rate but a lower insurance cost and greater flexibility for removing PMI.
The correct comparison is not:
“Which rate is lower?”
It is:
“Which option produces the better combination of cash to close, monthly payment, insurance cost, closing costs, and total interest for the time I expect to keep the loan?”
Ask each lender for a Loan Estimate and compare the same loan amount, term, property taxes, homeowners insurance assumptions, and points.
A useful break even question
Suppose FHA saves you $100 per month compared with conventional financing but costs more in mortgage insurance and upfront expenses. That initial advantage may disappear after several years.
On the other hand, if FHA approval is substantially easier and the monthly payment fits your budget better, the FHA option may be the more practical choice.
The answer depends on your actual numbers.
FHA Loan vs Conventional Loan: Property and Appraisal Differences
The property itself can influence your decision.
FHA properties must satisfy FHA minimum property requirements. The FHA appraisal therefore considers not only value but also whether the property meets applicable FHA standards.
Issues involving the roof, electrical systems, utilities, access, structural condition, or other safety concerns can require attention before closing. Rocket Mortgage notes that FHA appraisal standards can be more stringent than conventional appraisal requirements.
Conventional financing can offer more flexibility for properties that do not fit FHA requirements.
This matters when you are buying an older home or a property that needs repairs.
Do sellers prefer conventional offers?
Sometimes.
In a competitive market, some sellers may prefer conventional financing because they perceive it as having fewer property condition complications. FHA financing is not inherently a weak offer, but the appraisal and property requirements can affect negotiations.
Your offer strength also depends on the purchase price, earnest money, contingencies, preapproval, closing timeline, and local market conditions.
2026 FHA and Conventional Loan Limits
Loan limits matter if you are buying an expensive property.
For 2026, FHA’s one unit loan limit ranges from a $541,287 floor to a $1,249,125 ceiling, depending on the location. Limits are higher for two, three, and four unit properties.
For conventional conforming mortgages, the 2026 baseline limit for a one unit property is $832,750 in most of the United States. The ceiling reaches $1,249,125 in high cost areas.
Because limits vary by county, always verify the applicable limit for the property you want to purchase rather than relying on a national number.
Which Loan Is Better for First Time Homebuyers?
There is no rule saying first time buyers should choose FHA.
A first time buyer with strong credit, stable income, manageable debt, and enough savings may find conventional financing more attractive.
Another first time buyer with a lower credit score or limited savings may benefit from FHA financing.
FHA may be a better fit if:
- Your credit profile makes conventional qualification difficult.
- You have limited funds for a down payment.
- Your debt to income ratio needs more flexibility.
- You want a government insured mortgage designed for broader borrower eligibility.
- The property meets FHA requirements.
Conventional may be a better fit if:
- You have strong credit.
- You have stable income and manageable debt.
- You want to avoid FHA’s upfront mortgage insurance premium.
- You expect to build equity and want the possibility of removing PMI.
- You want financing for a second home or certain investment properties.
FHA vs Conventional: Pros and Cons
FHA loan advantages
- Lower credit barriers for many borrowers.
- 3.5% down payment option for qualifying borrowers.
- Government insurance can make lenders more comfortable with higher risk profiles.
- Can be useful for first time buyers and borrowers with limited savings.
FHA loan disadvantages
- Upfront mortgage insurance premium.
- Annual mortgage insurance costs.
- FHA property requirements can be more restrictive.
- Loan limits vary by county.
- Mortgage insurance can remain for a long period depending on the original down payment.
Conventional loan advantages
- Down payments can be as low as 3% for eligible borrowers and programs.
- PMI can generally be removed when applicable equity requirements are met.
- More property and occupancy flexibility.
- Potentially lower long term costs for well qualified borrowers.
- Available for primary residences and, depending on the program, second homes and investment properties.
Conventional loan disadvantages
- Qualification can be more difficult for borrowers with weaker credit or higher debt.
- PMI can increase the monthly payment when the down payment is below 20%.
- Interest rates and mortgage insurance pricing can vary substantially by borrower profile.
How to Choose Between FHA and Conventional Financing
Use this five step process before making a decision.
1. Compare your credit
Check your credit reports and scores before applying. A stronger credit profile can materially change conventional pricing.
2. Calculate your available cash
Do not put every dollar into the down payment. Keep reserves for closing costs, moving expenses, repairs, and unexpected bills.
3. Compare total monthly payments
Look beyond principal and interest. Include mortgage insurance, property taxes, homeowners insurance, and HOA fees when applicable.
4. Consider how long you will keep the loan
A loan that looks cheaper in year one may not be cheaper over ten years.
5. Get comparable Loan Estimates
Ask lenders to quote both options using the same purchase price and assumptions. Compare interest rate, APR, points, lender fees, mortgage insurance, cash to close, and projected payments.
The goal is not to find the mortgage with the lowest advertised rate. The goal is to find the mortgage that fits your finances and costs less for your expected ownership period.
FHA Loan vs Conventional Loan: Final Verdict
So, FHA Loan vs Conventional Loan: which one is right for you?
Choose FHA when its flexible qualification requirements solve a real problem for you, such as limited savings or a weaker credit profile.
Choose conventional when your credit, income, debt, and savings allow you to take advantage of potentially lower mortgage insurance costs and greater flexibility.
Neither loan is automatically better. The strongest decision comes from comparing actual offers side by side.
If you are preparing to buy in 2026, start by reviewing your credit, calculating your available cash, checking the applicable county loan limits, and requesting comparable quotes from multiple lenders.
Sources and Further Reading
- U.S. Department of Housing and Urban Development, 2026 FHA loan limits.
- Federal Housing Finance Agency, 2026 conforming loan limits.
- Consumer Financial Protection Bureau, conventional loans and PMI guidance.
- Rocket Mortgage, updated 2026 FHA versus conventional comparison.
FAQ Section
Is an FHA loan better than a conventional loan?
Neither is universally better. FHA can be useful for borrowers with lower credit scores or limited savings, while conventional financing may be more cost effective for borrowers with stronger credit and finances.
Is FHA cheaper than conventional?
Not necessarily. FHA may offer competitive interest rates, but FHA mortgage insurance can increase the total cost. Conventional PMI can often be removed after reaching applicable equity requirements.
Can I get a conventional loan with 3% down?
Yes. Some conventional programs allow eligible borrowers to purchase a home with as little as 3% down. Your lender will determine eligibility based on the complete application.
What credit score do I need for an FHA loan?
FHA guidelines allow borrowers with credit scores from 500 to 579 to qualify with a 10% down payment, while borrowers with scores of 580 or higher can generally qualify for the 3.5% minimum down payment. Individual lenders may have additional requirements.
Does FHA mortgage insurance ever go away?
It depends on the loan’s original loan to value ratio and applicable FHA rules. For many FHA loans with less than 10% down, annual MIP remains for the life of the loan. With sufficient initial equity, MIP may have a limited duration.
Should a first time buyer choose FHA or conventional?
A first time buyer should compare both. FHA may be preferable when qualification flexibility is important. Conventional may be preferable when the buyer has strong credit, manageable debt, and enough financial strength to receive favorable terms.






