

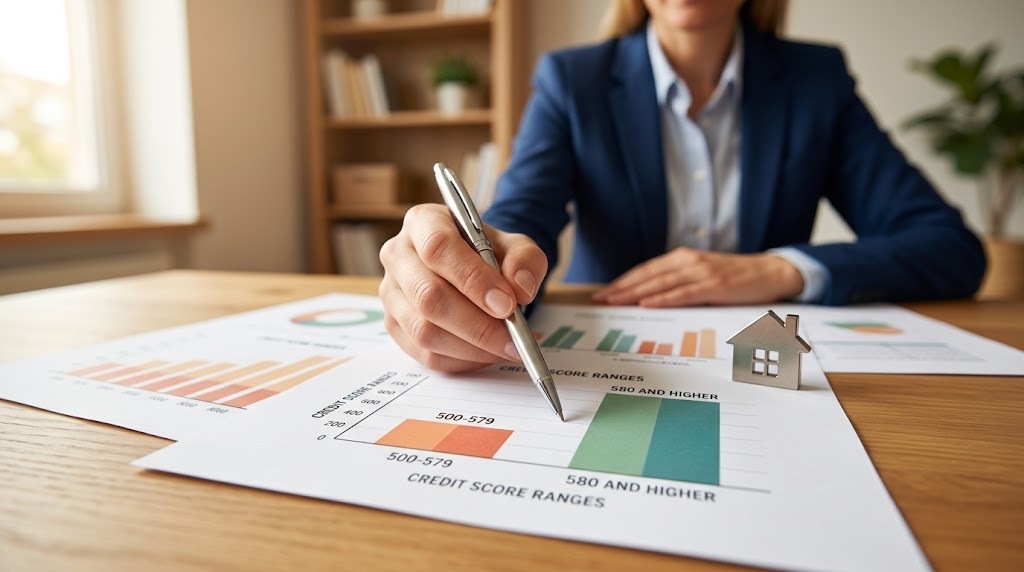
Minimum Credit Score for FHA Loans: What You Need to Qualify depends on both FHA’s baseline rules and the requirements of the lender you choose. Generally, FHA guidelines allow borrowers with a credit score of 580 or higher to qualify for the minimum 3.5% down payment. Borrowers with scores from 500 to 579 may qualify with at least 10% down, although individual lenders can impose stricter requirements.
That distinction matters. A borrower might meet the FHA’s basic credit standard but still be declined by a lender with a higher internal minimum. Your credit score is also only one part of mortgage approval. Income, debt, assets, payment history, employment, property eligibility, and other underwriting factors can affect the final decision.
This guide explains the FHA credit score rules, what happens at different score levels, how lender overlays work, and what you can do if your score is below the preferred range.
What Is the Minimum Credit Score for FHA Loans?
The FHA’s national baseline creates two important credit score ranges:
| Credit Score | Typical FHA Down Payment | What It Means |
|---|---|---|
| 580 or higher | 3.5% | Eligible for the FHA’s minimum down payment option |
| 500–579 | 10% | May qualify under FHA rules with a larger down payment |
| Below 500 | Not eligible under standard FHA credit policy | You generally need to improve your credit before qualifying |
The 580 threshold is therefore important, but it is not technically the only FHA credit score number that matters. FHA policy permits scores from 500 to 579 when the borrower contributes at least 10% toward the purchase. HUD documentation confirms the two tier structure, while current mortgage industry guidance notes that lenders may set higher minimums.
Why 580 Is an Important Target
If your score is 580 or above, the difference in required cash can be substantial.
For example, imagine a $300,000 home:
- At 3.5% down: $10,500
- At 10% down: $30,000
- Difference: $19,500
This is one reason improving a score from the 570s into the 580-plus range can have a meaningful practical effect. It can potentially reduce the cash needed at closing by thousands of dollars, assuming all other requirements are satisfied.
How Does FHA Credit Score Requirements Work in 2026?
One common misconception is that FHA itself approves every borrower based only on a credit score. It does not.
FHA insurance guidelines establish eligibility standards, but an FHA approved lender still evaluates the entire mortgage application. Lenders can also use stricter standards, commonly called lender overlays.
For example, the FHA baseline may permit a 500 credit score with 10% down, while a particular lender might require 580 or another higher score for its FHA products. Pennymac specifically notes that lenders can apply additional requirements beyond FHA’s national baseline.
That creates three different numbers borrowers should understand:
- Your credit score: The score reported by the credit reporting agencies and used during underwriting.
- FHA’s baseline: The federal program’s eligibility standard.
- The lender’s minimum: The lender’s own underwriting requirements.
The third number is often overlooked.
Does FHA Have One Universal Credit Score?
Not necessarily.
Mortgage lenders typically obtain credit information from the major credit reporting agencies. When there are multiple borrowers, the underwriting process also considers the borrowers’ individual credit profiles and the applicable FHA rules.
This is why seeing a score online does not guarantee that the exact same number will be used for mortgage underwriting.
If you are close to an important threshold, ask the lender which credit score and underwriting rules will apply before making major financial decisions.
What Other Requirements Do You Need for an FHA Loan?
Meeting the minimum credit score is necessary, but it does not automatically qualify you for an FHA mortgage.
Down Payment
Borrowers with a qualifying score of 580 or higher may be eligible for a down payment as low as 3.5%. Borrowers in the 500 to 579 range generally need at least 10% down under FHA’s baseline rules.
Your down payment can also affect your overall mortgage costs and cash requirements.
Debt to Income Ratio
Lenders evaluate your debt to income ratio (DTI) to determine whether your income can support your existing obligations and proposed mortgage payment.
A commonly referenced FHA benchmark is 31% for the housing expense ratio and 43% for total debt obligations. However, underwriting can be more nuanced, and stronger compensating factors may matter when a borrower’s ratios exceed common benchmarks.
Do not assume that a 43% DTI is an automatic approval or that exceeding it automatically means denial.
Income and Employment
You generally need to document income and demonstrate your ability to repay the mortgage.
Depending on your employment situation, the lender may review:
- Pay stubs
- W-2 forms
- Tax returns
- Bank statements
- Employment history
- Self employment documentation
- Other qualifying income
There is no single universal income amount that guarantees FHA approval. The lender evaluates your income in relation to the mortgage payment and other debts.
Primary Residence Requirement
FHA purchase loans are generally intended for owner occupied primary residences. The property must meet applicable FHA property standards and the borrower must satisfy occupancy requirements.
Mortgage Insurance
FHA loans require mortgage insurance. HUD’s current FHA guidance states that the upfront mortgage insurance premium for most forward purchase and refinance loans is 1.75% of the base loan amount, with annual mortgage insurance premiums generally paid in monthly installments.
This cost should be included when comparing an FHA mortgage with other loan programs.
Can You Get an FHA Loan With a 500 Credit Score?
Yes, a borrower with a 500 to 579 credit score may be eligible under FHA’s baseline rules, but the minimum down payment requirement is generally 10%.
That does not mean every lender will approve a 500 score.
A lender can establish stricter requirements, and the complete application still has to satisfy underwriting requirements. This is one of the biggest content gaps borrowers encounter when reading simple FHA credit score charts: the federal minimum and the lender’s practical minimum are not always the same.
If your score is 500, expect the lender to look closely at the rest of your financial profile.
Factors that may matter include:
- Recent late payments
- Collection accounts
- Outstanding debts
- Credit utilization
- Income stability
- Cash reserves
- Debt to income ratio
- Housing payment history
- Bankruptcy or foreclosure history
- Compensating factors
A lower score does not automatically tell the whole story.
What If Your Credit Score Is Below 580?
If your score is below 580, you have two broad paths: qualify under the 500 to 579 FHA tier if a lender is willing to approve the application, or work toward a higher score before applying.
Check Your Credit Reports
Start by reviewing your credit reports for inaccurate information.
Look for:
- Accounts you do not recognize
- Incorrect balances
- Incorrect payment history
- Duplicate accounts
- Outdated negative information
If you identify an error, follow the appropriate dispute process with the credit reporting company.
Reduce Credit Card Balances
Credit utilization can influence credit scores. Reducing revolving balances may help improve your profile, although there is no guaranteed number of points or guaranteed timeline.
Avoid taking on unnecessary new debt while preparing for a mortgage.
Protect Your Payment History
A new late payment can hurt your mortgage preparation. Continue making payments on time and avoid deliberately closing accounts without understanding how the change could affect your credit profile.
Avoid Unnecessary Credit Applications
Opening multiple new credit accounts shortly before applying for a mortgage can complicate your financial profile.
If you are planning to buy soon, speak with a mortgage professional before making significant credit changes.
Does a Higher Credit Score Improve FHA Approval Chances?
A higher score can strengthen your application, but there is no magic number that guarantees approval.
For example, a borrower with a 620 score and stable income, manageable debts, substantial reserves, and clean recent payment history may have a very different risk profile from another borrower with the same score but significant recent delinquencies.
Think of credit score as one piece of the underwriting picture, not the entire picture.
This is especially important for borrowers who see an online statement such as “FHA requires 580” and assume they are automatically approved once they reach that number.
They are not.
The 580 threshold can make the minimum FHA down payment option available under FHA’s baseline rules, but the lender still reviews the complete application.
How Much Can You Borrow With an FHA Loan in 2026?
Credit score does not determine the FHA loan limit by itself.
FHA loan limits vary by location and property size. For 2026, HUD lists a nationwide one unit FHA loan limit floor of $541,287 and a high cost ceiling of $1,249,125. Higher limits apply to two, three, and four unit properties.
That means a borrower could have a credit score high enough for FHA eligibility but still need to choose a property that fits the applicable FHA loan limit for the location.
FHA Credit Score vs. Conventional Loan Credit Score
FHA is often attractive to borrowers who have less than perfect credit because its federal baseline is more flexible than many conventional mortgage options.
However, the best loan is not automatically the one with the lowest credit score requirement.
Consider:
- Down payment
- Mortgage insurance
- Interest rate
- Closing costs
- DTI
- Cash reserves
- Long term plans
- Credit profile
A borrower with strong credit may find that a conventional mortgage offers advantages, while another borrower with a lower score may find FHA more accessible.
The right comparison should consider total borrowing costs, not just the minimum score advertised by the lender.
What Should You Do Before Applying for an FHA Loan?
If buying a home is your goal, use this simple preparation process.
1. Check Your Credit
Review your credit profile and identify anything that needs attention.
2. Calculate Your Down Payment
Determine whether you are financially prepared for 3.5% or, if your score falls between 500 and 579, the potentially required 10% down payment under FHA’s baseline.
3. Review Your Debts
Calculate your monthly debt obligations and compare them with your gross monthly income.
4. Avoid Major Financial Changes
Do not make large purchases, open unnecessary accounts, or move significant amounts of money without understanding how those actions could affect underwriting.
5. Compare FHA Lenders
Ask each lender:
- What is your minimum FHA credit score?
- Do you allow 500 to 579 scores?
- What down payment is required at my score?
- Are there lender overlays?
- What documentation will you need?
- What are the estimated closing costs?
This approach can save time because you are comparing the lender’s actual policy, not just FHA’s federal baseline.
The Bottom Line: What Credit Score Do You Need for FHA?
The FHA’s baseline credit score structure is straightforward:
- 580 or higher: potentially eligible for the 3.5% minimum down payment.
- 500 to 579: potentially eligible with at least 10% down.
- Below 500: generally not eligible for standard FHA insurance.
However, your lender can impose stricter requirements, so the FHA minimum is not necessarily the lender’s minimum.
The most useful way to think about FHA qualification is to treat 580 as an important target, not an automatic approval score.
If your score is below 580, do not assume homeownership is out of reach. First determine whether your lender accepts the lower FHA range, then compare the cost of a larger down payment with the potential benefit of improving your credit before applying.
For official FHA information, review and verify current loan limits and program guidance before making a mortgage decision.
FAQ Section
What is the minimum credit score for an FHA loan?
The FHA baseline generally allows borrowers with credit scores of 580 or higher to qualify for the 3.5% minimum down payment option. Borrowers with scores from 500 to 579 may qualify with at least 10% down, subject to lender requirements.
Can I get an FHA loan with a 500 credit score?
Potentially, yes. FHA guidelines allow borrowers in the 500 to 579 range with a 10% minimum down payment. However, some lenders impose higher credit score requirements, so a 500 score does not guarantee approval.
Is 580 a good credit score for an FHA loan?
Yes. A 580 score is an important FHA threshold because it can allow the borrower to qualify for the program’s minimum 3.5% down payment under FHA’s baseline rules. The lender still evaluates income, debts, assets, credit history, and the property.
Does FHA require a 620 credit score?
No. FHA’s national baseline is not a 620 minimum. FHA guidelines can allow scores from 500 to 579 with 10% down and scores of 580 or higher with the minimum 3.5% down payment. Individual lenders may require higher scores.
Can I qualify for an FHA loan with bad credit?
Possibly. FHA is designed to provide access to mortgage financing for borrowers who may not qualify as easily for some conventional loans. However, approval depends on the complete financial profile, lender requirements, and the circumstances behind the credit issues.
How can I improve my credit score before applying for FHA?
Review your credit reports for errors, make payments on time, reduce revolving balances, avoid unnecessary new credit applications, and discuss major credit changes with a qualified mortgage professional before applying.






