
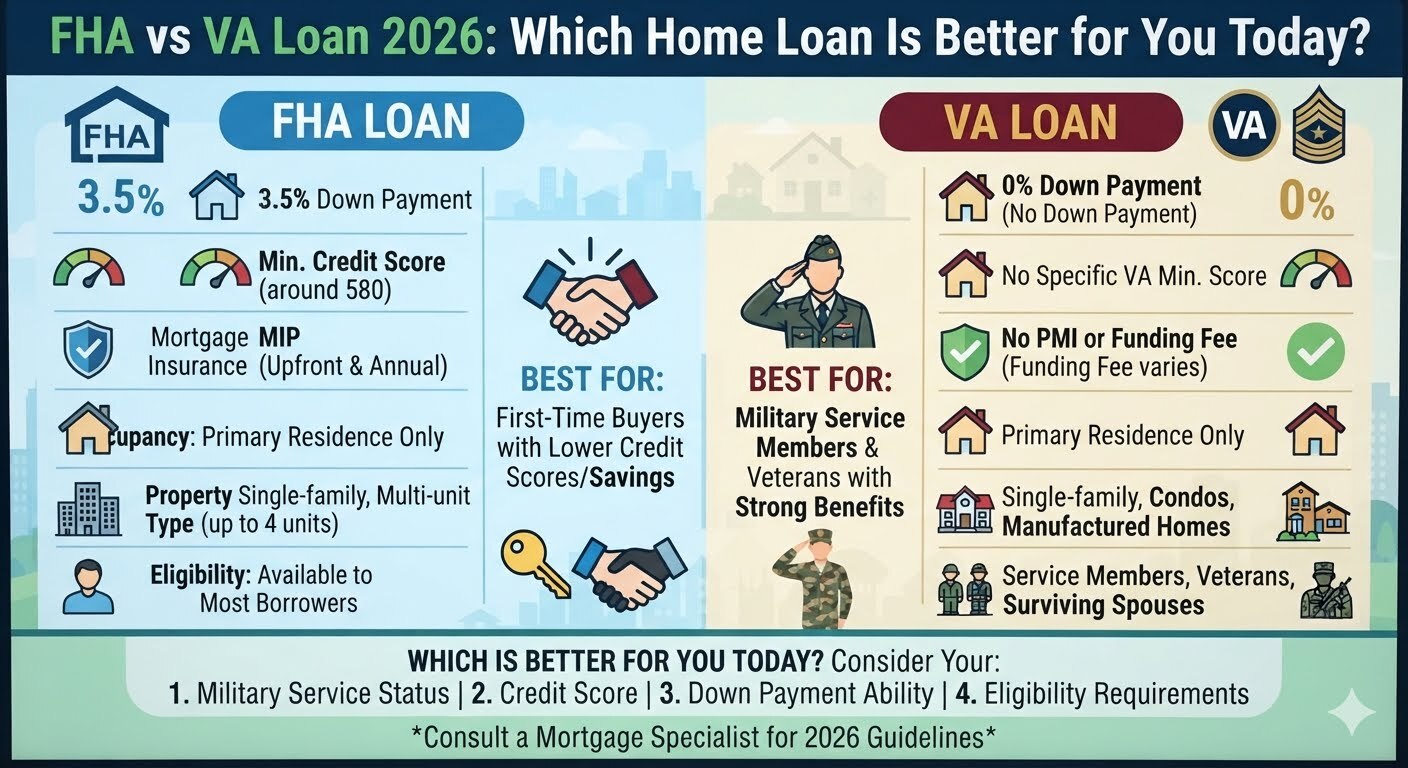

Compare FHA vs VA Loan 2026 requirements, rates, fees, credit scores, and benefits. Learn which mortgage loan is the best choice for your home purchase.
FHA vs VA Loan 2026: Key Differences Explained
Buying a home is one of the biggest financial decisions you will ever make. Choosing the right mortgage can save you thousands of dollars over the life of your loan. Two of the most popular home financing programs are the FHA loan and the VA loan. Each offers unique benefits, but they are designed for different types of borrowers.
If you are comparing FHA vs VA Loan 2026, this guide explains the key differences, eligibility requirements, costs, and advantages so you can make the best decision for your situation.
What Is an FHA Loan?
An FHA loan is a mortgage insured by the Federal Housing Administration. It is designed to help borrowers who may have limited savings or lower credit scores qualify for home financing.
Many first time buyers choose FHA loans because they offer flexible qualification requirements and lower down payment options.
Main Benefits of FHA Loans
- Down payment as low as 3.5 percent
- Flexible credit score requirements
- Competitive interest rates
- Available to many home buyers
- Can be used for primary residences
What Is a VA Loan?
A VA loan is backed by the United States Department of Veterans Affairs. It is available to eligible veterans, active military members, qualifying National Guard members, Reservists, and some surviving spouses.
VA loans provide some of the most valuable mortgage benefits available today.
Main Benefits of VA Loans
- No down payment for most borrowers
- No private mortgage insurance
- Competitive mortgage rates
- Flexible credit guidelines
- Limited closing costs
FHA vs VA Loan 2026: Side by Side Comparison
| Feature | FHA Loan | VA Loan |
|---|---|---|
| Down payment | Starting at 3.5 percent | Usually no down payment |
| Credit requirements | More flexible | Flexible depending on lender |
| Mortgage insurance | Required | Not required |
| Eligibility | Open to qualified buyers | Military service required |
| Property type | Primary residence | Primary residence |
| Interest rates | Competitive | Often lower than FHA |
Credit Score Requirements
Your credit score plays an important role in mortgage approval.
FHA Loan
Many lenders accept borrowers with credit scores starting around 580 for the lowest down payment. Some lenders may approve lower scores with additional requirements.
VA Loan
The VA does not set a minimum credit score. Individual lenders establish their own standards. Many lenders prefer scores around 620 or higher, although some accept lower scores.
Down Payment Differences
One of the biggest differences between these loan programs is the required down payment.
FHA Loan
Most borrowers need at least a 3.5 percent down payment if they meet the credit requirements.
VA Loan
Qualified borrowers can often purchase a home with no down payment, making it one of the most affordable mortgage options available.
Mortgage Insurance and Funding Fees
This area creates one of the biggest cost differences.
FHA Mortgage Insurance
FHA loans require mortgage insurance. Borrowers pay an upfront mortgage insurance premium and an annual premium that is included in monthly payments.
VA Funding Fee
VA loans do not require mortgage insurance. Instead, many borrowers pay a one time VA funding fee. Some veterans may qualify for an exemption from this fee.
Who Qualifies?
FHA Loan Eligibility
An FHA loan may be a good choice if you:
- Have moderate income
- Need a lower down payment
- Have limited credit history
- Are purchasing your primary home
VA Loan Eligibility
A VA loan may be right if you:
- Are an eligible veteran
- Are serving in the military
- Meet service requirements
- Have a valid Certificate of Eligibility
Which Loan Has Lower Monthly Payments?
In many cases, VA loans have lower monthly payments because borrowers do not pay monthly mortgage insurance.
FHA borrowers often pay more each month because mortgage insurance increases the total payment.
However, your actual payment depends on:
- Home price
- Interest rate
- Loan amount
- Property taxes
- Homeowners insurance
FHA vs VA Loan 2026: Pros and Cons
FHA Loan Pros
- Easier qualification
- Lower credit score requirements
- Lower down payment
- Good for many buyers
FHA Loan Cons
- Mortgage insurance required
- Higher monthly costs
- Smaller loan flexibility
VA Loan Pros
- No down payment
- No monthly mortgage insurance
- Lower borrowing costs
- Excellent long term savings
VA Loan Cons
- Only available to eligible military borrowers
- Funding fee may apply
- Certificate of Eligibility required
Which Loan Is Better?
The best mortgage depends on your personal situation.
Choose an FHA loan if:
- You are not eligible for a VA loan.
- You have limited savings.
- You need flexible qualification requirements.
Choose a VA loan if:
- You qualify through military service.
- You want to avoid mortgage insurance.
- You want the lowest possible monthly payment.
- You want to purchase with no down payment.
For eligible military borrowers, a VA loan often provides greater long term savings because it eliminates monthly mortgage insurance and reduces upfront costs.
Conclusion
Choosing between an FHA loan and a VA loan is an important step toward homeownership. Both loan programs help buyers qualify for financing, but they serve different needs.
If you qualify for a VA loan, it usually offers greater financial advantages, including no down payment and no monthly mortgage insurance. If you do not qualify for VA benefits, an FHA loan remains an excellent option thanks to its flexible credit requirements and affordable down payment.
Compare loan estimates from multiple lenders, review your financial goals, and select the mortgage that best fits your budget and future plans.
Frequently Asked Questions
1. Is a VA loan better than an FHA loan?
For eligible military borrowers, a VA loan is often better because it offers no down payment and no monthly mortgage insurance.
2. Can anyone apply for a VA loan?
No. VA loans are only available to eligible veterans, military members, and certain surviving spouses who meet service requirements.
3. Which loan is easier to qualify for?
FHA loans are generally easier for buyers with lower credit scores or limited savings.
4. Does an FHA loan require mortgage insurance?
Yes. FHA loans require both upfront and monthly mortgage insurance premiums.
5. Do VA loans require a down payment?
Most qualified borrowers can purchase a home with no down payment.
6. Which loan has lower monthly payments?
VA loans often have lower monthly payments because they do not require monthly mortgage insurance.
7. Can I refinance from an FHA loan to a VA loan?
Yes. If you become eligible for VA benefits and meet lender requirements, refinancing may be possible.






