

The Complete FHA Loan Guide for First-Time Home Buyers can help you understand one of the most accessible mortgage options available in the United States. If you are buying your first home, have limited savings, or have less than perfect credit, an FHA loan may be worth considering.
An FHA loan is a mortgage issued by an FHA-approved private lender and insured by the Federal Housing Administration. The FHA does not lend the money directly. Instead, its insurance reduces the lender’s risk and allows lenders to offer more flexible qualifying standards.
In simple terms, an FHA loan can let an eligible buyer purchase a primary residence with as little as 3.5% down when the borrower meets the applicable credit requirements. However, FHA mortgage insurance, loan limits, property standards, and lender requirements all affect the real cost and eligibility.
What Is an FHA Loan?
An FHA loan is a government insured mortgage designed to make homeownership more accessible. You apply through an FHA approved lender, and the FHA provides mortgage insurance to the lender.
The program can be particularly useful for first time buyers who may not have a large down payment or a strong conventional credit profile.
HUD says FHA loans can offer down payments as low as 3.5% and are available for eligible one to four unit properties.
Being a first time buyer is not itself a requirement for an FHA loan. The program can also be used by repeat buyers who meet its requirements. That distinction matters because many buyers incorrectly assume FHA financing is exclusively for people purchasing their first home.
Why do first time buyers choose FHA loans?
Common reasons include:
- A down payment as low as 3.5% for eligible borrowers
- More flexible credit requirements than many conventional loans
- Financing for eligible one to four unit primary residences
- Potential use of acceptable gift funds and separate down payment assistance programs
- Options such as FHA 203(k) financing for eligible renovation projects
- Annual county based loan limits rather than one nationwide limit
The tradeoff is that FHA financing requires mortgage insurance and has property and loan requirements that buyers need to understand before making an offer.
The Complete FHA Loan Guide: What Are the Main FHA Requirements?
FHA requirements involve more than your credit score. Your lender will evaluate your credit history, income, assets, debts, employment, property, and ability to repay the mortgage.
Credit score and down payment
For the standard FHA minimum down payment structure, borrowers with a qualifying credit score of 580 or higher can generally put down 3.5%.
Borrowers with credit scores from 500 through 579 may be eligible for FHA financing with a 10% down payment. Individual lenders can impose stricter requirements, known as overlays.
For example, a $300,000 home with a 3.5% down payment would require:
- Purchase price: $300,000
- 3.5% down payment: $10,500
- Base FHA loan amount: $289,500
That $10,500 is not necessarily the total cash you need. Buyers must also consider closing costs, prepaid expenses, reserves, inspection costs, moving expenses, and other transaction costs.
Income and employment
There is not one universal FHA minimum salary. Instead, lenders evaluate whether your documented income is sufficient and likely to continue.
You may need documents such as:
- Recent pay stubs
- W-2 forms
- Federal tax returns when applicable
- Bank statements
- Employment information
- Documentation for other qualifying income
- Explanations for certain credit or financial issues
Employment history is also reviewed. The exact documentation depends on your employment situation and lender requirements.
Debt to income ratio
Your debt to income ratio, or DTI, compares your recurring monthly debt obligations with your gross monthly income.
For example, if your gross monthly income is $7,000 and your qualifying monthly debts total $3,150:
$3,150 ÷ $7,000 = 45% DTI
A lower DTI generally gives you more financial breathing room. FHA underwriting can allow higher ratios in some circumstances when other qualifying factors support the application, so buyers should not treat 43% as an absolute FHA rule. Lender overlays can also differ.
Primary residence requirement
The FHA program is generally intended for owner occupied primary residences. It is not designed to let you buy a standard investment property or vacation home with an ordinary FHA purchase mortgage.
This is an important distinction for first time buyers who may be thinking about purchasing a rental property.
How Much Down Payment Do You Need for an FHA Loan?
The minimum FHA down payment can be as low as 3.5% when the borrower meets the applicable credit requirement.
Consider this simple comparison:
| Home Price | 3.5% Down Payment |
|---|---|
| $200,000 | $7,000 |
| $250,000 | $8,750 |
| $300,000 | $10,500 |
| $400,000 | $14,000 |
A smaller down payment can make homeownership easier to enter, but it does not necessarily make the mortgage cheaper over time.
A buyer should compare the full monthly payment and long term costs rather than focusing only on the cash needed at closing.
The CFPB recommends considering the down payment together with closing costs, mortgage insurance, interest, and other home buying expenses.
Can you get FHA down payment assistance?
Yes, an FHA loan can generally be combined with qualifying assistance programs.
However, there is no single federal FHA down payment assistance program that automatically gives every FHA borrower money for a down payment. Assistance may instead come through state or local housing agencies, nonprofits, employers, or other approved programs, with eligibility varying by location and program.
FHA Down Payment Assistance Programs
FHA Mortgage Insurance: What Will It Cost?
Mortgage insurance is one of the most important differences between FHA financing and some conventional mortgage options.
FHA loans generally have two mortgage insurance components:
- Upfront Mortgage Insurance Premium, or UFMIP
- Annual Mortgage Insurance Premium, or MIP, normally collected through monthly payments
HUD’s current guidance lists the standard upfront premium at 1.75% of the base loan amount for most FHA forward purchase and refinance transactions.
Using the $300,000 example above:
- Base loan: $289,500
- UFMIP at 1.75%: $5,066.25
The borrower may generally finance the UFMIP into the mortgage rather than paying it entirely in cash at closing. Financing it increases the loan balance and therefore increases the total amount paid over time.
Annual MIP depends on factors such as loan amount, loan term, and loan to value ratio. The applicable FHA premium schedule should be confirmed with the lender because the rules can change.
Mortgage insurance is not a benefit paid to the borrower. It protects the lender against losses.
What Are the 2026 FHA Loan Limits?
FHA loan limits vary by location and property size. They are not the same in every U.S. county.
For 2026, HUD announced these standard forward mortgage limits:
| Property | Low Cost Area Floor | High Cost Area Ceiling |
| One unit | $541,287 | $1,249,125 |
| Two units | $693,050 | $1,599,375 |
| Three units | $837,700 | $1,933,200 |
| Four units | $1,041,125 | $2,402,625 |
These limits apply to FHA case numbers assigned on or after January 1, 2026. Special higher limits apply in Alaska, Hawaii, Guam, and the U.S. Virgin Islands.
Because the limit can vary by county, never assume the national floor or ceiling is your personal borrowing limit.
What Types of Homes Can You Buy With FHA Financing?
FHA financing can cover several eligible property types when they meet program requirements and occupancy rules.
Single family homes
A standard FHA 203(b) mortgage is commonly used to purchase an eligible primary residence.
Two to four unit properties
FHA financing can be used for eligible one to four unit properties. This can create an interesting strategy for a first time buyer who wants to live in one unit while renting the others, subject to FHA occupancy and property requirements.
Condos
Eligible condominium units can qualify, but the project and unit must satisfy applicable FHA requirements.
Fixer upper properties
The FHA 203(k) program can combine a home purchase with eligible renovation financing. This can be useful when the property needs improvements that a standard purchase mortgage may not easily accommodate.
Manufactured housing
FHA also offers financing options for certain manufactured homes and factory built housing. HUD notes that different FHA products can apply depending on the home and land arrangement.
FHA Appraisal vs. Home Inspection: What Is the Difference?
This is one area where first time buyers often become confused.
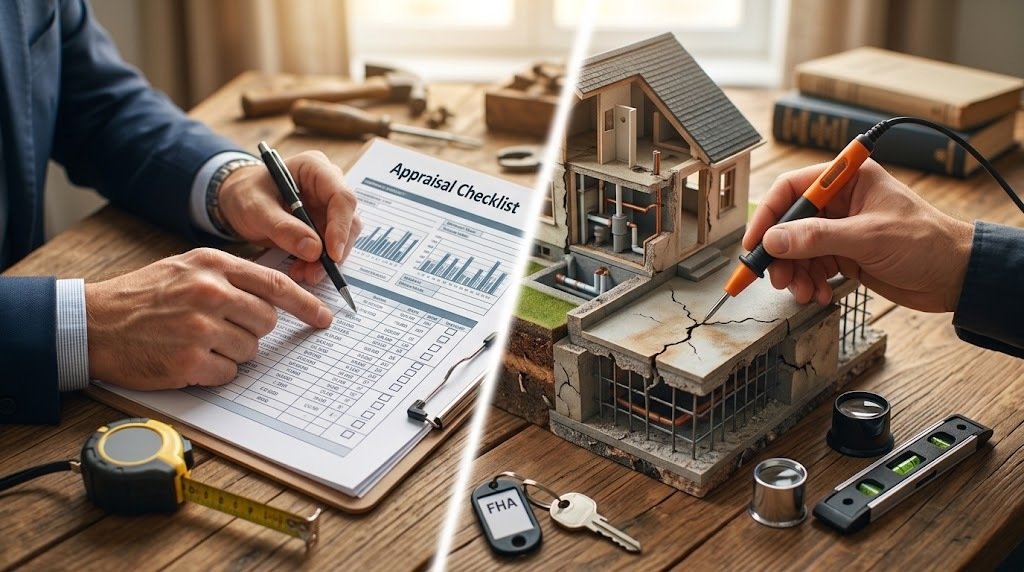
An FHA appraisal is used to determine the property’s market value and evaluate whether the property meets applicable FHA property requirements.
A home inspection is a separate buyer protection tool. It is more comprehensive and is intended to help the buyer understand the condition of the property.
HUD explains that an FHA roster appraiser’s observation is not the same as a comprehensive inspection by a licensed home inspector.
FHA properties must meet applicable safety, soundness, and security standards. If serious deficiencies are identified, repairs or additional inspections may be required before the mortgage can move forward.
Practical tip: Never skip an independent home inspection simply because an FHA appraisal has been completed.
How Does the FHA Loan Process Work?
The FHA mortgage process becomes easier to understand when you break it into stages.
Step 1: Review your finances
Check your credit, income, savings, debts, and monthly budget.
Step 2: Compare FHA lenders
Do not assume every FHA lender offers identical pricing or underwriting standards. Ask multiple lenders for comparable loan estimates.
The CFPB recommends shopping and comparing mortgage offers rather than focusing only on the advertised interest rate.
Step 3: Get preapproved
A preapproval helps you understand your potential buying range before you start making offers.
Step 4: Find an eligible property
Work with a real estate professional who understands FHA property requirements.
Step 5: Make an offer
Your offer should account for your financing, appraisal considerations, inspection, and desired closing timeline.
Step 6: Complete underwriting
Your lender verifies income, assets, debts, credit, employment, and other required information.
Step 7: Complete the appraisal
The property is evaluated by an FHA roster appraiser through the lender’s process.
Step 8: Resolve conditions
If underwriting or the appraisal identifies outstanding requirements, those issues must be addressed before final approval.
Step 9: Close
You sign the final loan documents, pay required funds, and take ownership according to the closing documents.
How to Get Pre Approved for a Mortgage in 2026
FHA vs. Conventional Loan: Which Is Better for First-Time Buyers?
Neither loan is automatically better for every buyer.
An FHA loan may make sense when you have a smaller down payment, a lower credit score, or other circumstances that make conventional qualification more difficult.
A conventional loan may become more attractive when you have stronger credit, more money available for a down payment, and a financial profile that qualifies for competitive conventional pricing.
The CFPB notes that FHA loans can sometimes be cheaper for borrowers with lower credit scores or smaller down payments, while conventional financing may be less expensive for borrowers with stronger credit and larger down payments.
Compare:
- Interest rate
- APR
- Monthly mortgage insurance
- Upfront costs
- Closing costs
- Loan term
- Cash required at closing
- Total interest
- Expected time you will keep the mortgage
The lowest advertised rate is not necessarily the lowest cost mortgage.
What Are the Biggest FHA Loan Pros and Cons?
FHA loan advantages
- Low minimum down payment
- Flexible credit requirements
- Financing for eligible one to four unit properties
- Potential access to approved assistance programs
- 203(k) renovation financing for eligible properties
- Useful option for some borrowers rebuilding their credit
FHA loan disadvantages
- Mortgage insurance adds cost
- UFMIP increases the initial financing cost if financed
- Loan limits vary by county
- Properties must meet applicable FHA standards
- Lender overlays can make qualification stricter than basic FHA guidelines
- Conventional financing may be less expensive for some financially stronger borrowers
The important lesson is simple: an FHA loan is a tool, not automatically the best mortgage.
How Much Cash Should a First-Time FHA Buyer Actually Save?
Do not build your home buying budget around the 3.5% down payment alone.
A stronger savings target should account for:
- Down payment
- Closing costs
- Prepaid taxes and insurance
- Home inspection
- Appraisal related expenses
- Moving expenses
- Immediate repairs
- Emergency savings
For example, a buyer purchasing a $300,000 home may need $10,500 for the minimum 3.5% down payment, but that does not mean $10,500 is enough cash to safely complete the purchase.
This is an important practical distinction that is easy to miss when mortgage advertising focuses heavily on minimum down payments.
Is an FHA Loan Right for You?
An FHA loan may be worth exploring if you:
- Are buying a primary residence
- Have limited funds for a down payment
- Have a credit profile that makes conventional financing difficult
- Want to purchase an eligible one to four unit property
- Can comfortably afford the full monthly payment
- Understand the cost of FHA mortgage insurance
It may be worth comparing conventional financing if you have stronger credit, a larger down payment, or a financial profile that could qualify for lower total mortgage costs.
Before choosing, ask at least two or three lenders to compare the same loan amount, term, down payment, and property type.
Conclusion: Start With the Numbers, Not Just the Down Payment
The Complete FHA Loan Guide for First-Time Home Buyers comes down to one important idea: qualifying for an FHA loan and being financially ready for an FHA loan are two different things.
FHA financing can provide an accessible path to homeownership through a low minimum down payment and flexible qualifying standards. But mortgage insurance, closing costs, property requirements, loan limits, interest rates, and lender overlays all affect the final decision.
Start by reviewing your credit, calculating your realistic monthly housing budget, checking the FHA loan limit for your county, and comparing FHA and conventional offers.
FAQ Section
What is the minimum down payment for an FHA loan?
The minimum FHA down payment can be 3.5% when the borrower meets the applicable credit requirements. Borrowers with scores from 500 through 579 may be eligible with a 10% down payment. Individual lenders may impose stricter requirements.
What credit score do I need for an FHA loan?
FHA guidelines can allow borrowers with credit scores as low as 500, but a 10% down payment generally applies to scores from 500 through 579. A score of 580 or higher can qualify for the 3.5% minimum down payment under the standard FHA structure. Lenders may have stricter overlays.
Do FHA loans require mortgage insurance?
Yes. FHA loans generally require an upfront mortgage insurance premium and an annual mortgage insurance premium. The standard upfront premium for most FHA forward mortgages is 1.75% of the base loan amount.
Can first time home buyers use FHA down payment assistance?
Yes. Eligible FHA borrowers may combine FHA financing with qualifying assistance from state or local agencies, nonprofits, employers, or other approved programs. Eligibility and terms vary by location and program.
What are the 2026 FHA loan limits?
For 2026, the FHA one unit loan limit ranges from a $541,287 floor in low cost areas to a $1,249,125 ceiling in high cost areas. The exact limit depends on the county and property size.
Can I use an FHA loan to buy a fixer upper?
Yes. An FHA 203(k) mortgage can combine eligible home purchase and renovation financing into one mortgage, subject to program and lender requirements.






