

Buying a home is one of the biggest financial decisions most people make, and knowing how to get preapproved for mortgage can make the entire process easier. A mortgage preapproval shows sellers that you are a serious buyer and helps you understand how much home you can realistically afford.
A mortgage preapproval is an official review by a lender where they evaluate your income, credit history, debts, and financial documents before deciding how much they may be willing to lend. Unlike a simple estimate, a preapproval gives you a stronger position when making an offer.
The mortgage preapproval process usually involves checking your credit score, submitting financial documents, comparing lenders, completing an application, and receiving a preapproval letter.
Many first-time buyers confuse prequalification with preapproval. While both provide an estimate, preapproval requires more detailed financial verification and carries more weight with sellers.
What Does Mortgage Preapproval Mean?
Mortgage preapproval means a lender has reviewed your financial information and determined the approximate loan amount you may qualify for.
During the process, lenders usually analyze:
- Income and employment history
- Credit score and credit report
- Existing debts
- Savings and assets
- Down payment amount
- Debt-to-income ratio
A preapproval is not a guarantee that you will receive the final mortgage. The lender will still complete a full underwriting review after you choose a property.
However, it gives buyers a clearer understanding of their budget and helps avoid wasting time looking at homes outside their financial range.
According to the Consumer Financial Protection Bureau (CFPB), getting preapproved before shopping for a home can help buyers understand their borrowing options and compare loan offers.
How to Get Preapproved for Mortgage: Step-by-Step Process
1. Check Your Credit Score Before Applying
Your credit score is one of the most important factors lenders consider during mortgage approval.
Generally, a higher credit score can help you qualify for better interest rates. Many conventional lenders prefer borrowers with stronger credit profiles, although government-backed loans may have different requirements.
Before applying:
- Review your credit reports
- Check for errors
- Pay down high credit card balances
- Avoid opening unnecessary new accounts
For example, a buyer with a $5,000 credit card balance and a $7,000 monthly income may receive a different approval result compared with someone earning the same income but carrying only $500 in debt.
You can review your credit reports through authorized sources such as AnnualCreditReport.com.
2. Calculate Your Budget and Affordability
Before contacting lenders, understand how much monthly payment you can comfortably manage.
Mortgage affordability depends on more than the purchase price. Buyers should consider:
- Principal and interest payments
- Property taxes
- Home insurance
- Mortgage insurance (if applicable)
- Maintenance costs
- HOA fees
A common mistake is focusing only on the maximum amount a lender approves instead of choosing a payment that fits your lifestyle.
For example, a lender may approve a $450,000 mortgage, but your personal budget may make a $350,000 home a more comfortable choice.
3. Gather Required Documents
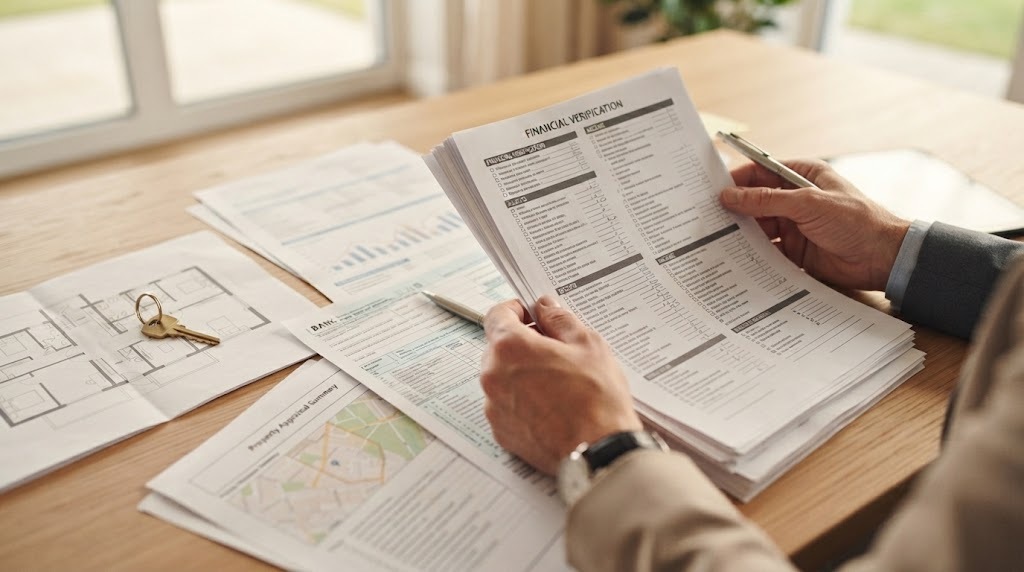
One of the biggest steps in the mortgage preapproval process is preparing your financial documents.
Most lenders ask for:
Income Documents
- Recent pay stubs
- W-2 forms
- Tax returns
- Employment verification
Asset Information
- Bank statements
- Investment account statements
- Proof of down payment funds
Debt Information
- Credit card statements
- Student loans
- Auto loans
- Personal loans
Identification
- Government-issued ID
- Social Security number
Having these documents ready can speed up the process and prevent unnecessary delays.
What Credit Score Do You Need for Mortgage Preapproval?
There is no single credit score requirement for every mortgage because requirements depend on the lender, loan type, and financial situation.
Common mortgage programs include:
Conventional Loans
Many conventional lenders look for stronger credit profiles. Borrowers with higher scores may receive more favorable interest rates.
FHA Loans
FHA loans are designed to help more buyers qualify and may allow lower credit scores compared with conventional mortgages.
VA Loans
Eligible veterans and active service members may qualify for VA loans with different requirements.
USDA Loans
USDA loans are available for eligible rural and suburban properties and have specific income and location rules.
Improving your credit before applying may increase your options and potentially reduce borrowing costs.
How Long Does Mortgage Preapproval Take?
The timeline depends on your lender and how quickly you provide documents.
Most mortgage preapprovals can take:
- Same day: Some digital lenders provide quick reviews
- 1–3 business days: Common timeframe when documents are complete
- Several weeks: If income verification or financial issues require additional review
To speed up approval:
- Respond quickly to lender requests
- Organize documents before applying
- Avoid making major financial changes
Do not finance a new car, make large purchases, or change jobs during the mortgage process without discussing it with your lender.
Mortgage Preapproval vs Prequalification: What Is the Difference?
Many buyers ask about the difference between preapproval and prequalification.
| Prequalification | Preapproval |
|---|---|
| Basic financial information | Detailed financial review |
| Usually no document verification | Requires income and asset documents |
| Less reliable for sellers | Stronger offer position |
| Estimated borrowing amount | More accurate loan amount |
Prequalification can be useful early in your home search, but preapproval is usually the better step before making an offer.
How Many Mortgage Lenders Should You Contact?
Shopping around can help you compare:
- Interest rates
- Closing costs
- Loan programs
- Customer service
- Estimated monthly payments
Many experts recommend comparing multiple lenders instead of accepting the first offer.
When comparing lenders, ask:
- What is the interest rate?
- What are the closing costs?
- Are there lender fees?
- How long does approval usually take?
- Which loan programs fit my situation?
What Happens After You Receive a Mortgage Preapproval Letter?
After approval, your lender provides a preapproval letter showing:
- Approved loan amount
- Loan program
- Date issued
- Conditions that may apply
You can use this letter when making offers on homes.
Keep in mind that lenders may update your approval if your financial situation changes.
Avoid:
- Missing payments
- Changing employment
- Taking new loans
- Moving large amounts of money without documentation
Common Mistakes During the Mortgage Preapproval Process
Applying With Unstable Income
Lenders want confidence that you can repay the loan. Frequent job changes or inconsistent income may create challenges.
Ignoring Your Debt-to-Income Ratio
Your debt-to-income ratio compares monthly debt payments with gross monthly income.
A high ratio may reduce your borrowing options.
Making Large Purchases
Buying expensive furniture, vehicles, or electronics before closing can affect your mortgage approval.
Not Comparing Loan Offers
Different lenders may offer different rates and fees. Comparing options can help you make a better financial decision.
How to Improve Your Chances of Mortgage Approval
Before applying, consider these steps:
Increase Your Savings
A larger down payment may reduce your loan amount and improve your financial position.
Reduce Existing Debt
Paying down credit cards or personal loans can improve your debt-to-income ratio.
Maintain Stable Employment
Consistent employment history can strengthen your application.
Avoid New Credit Applications
Multiple credit inquiries may affect your credit profile.
Conclusion: Start Your Mortgage Preapproval Journey With Confidence
Understanding how to get preapproved for mortgage helps you enter the home-buying process with realistic expectations and stronger negotiating power.
The mortgage preapproval process does not have to be complicated. By improving your credit, preparing documents, comparing lenders, and understanding your budget, you can make smarter decisions before choosing a home.
A preapproval letter is more than paperwork. It is a financial roadmap that helps you know where you stand and prepares you for the next step toward homeownership.
FAQ Section
How long does mortgage preapproval last?
Most mortgage preapproval letters are valid for around 60 to 90 days, although the exact timeframe depends on the lender.
Does mortgage preapproval hurt your credit score?
A mortgage preapproval usually requires a hard credit inquiry, which may temporarily affect your score. Multiple mortgage inquiries within a short shopping period are often treated as a single inquiry by credit scoring models.
Can I get preapproved for a mortgage without a large down payment?
Yes. Some loan programs allow lower down payments. Requirements depend on the lender, loan type, and borrower qualifications.
What documents do I need for mortgage preapproval?
Common documents include pay stubs, tax returns, bank statements, identification, and information about debts and assets.
Is mortgage preapproval the same as final approval?
No. Preapproval is an early review. Final approval happens after the lender completes underwriting and evaluates the selected property.







One Response