
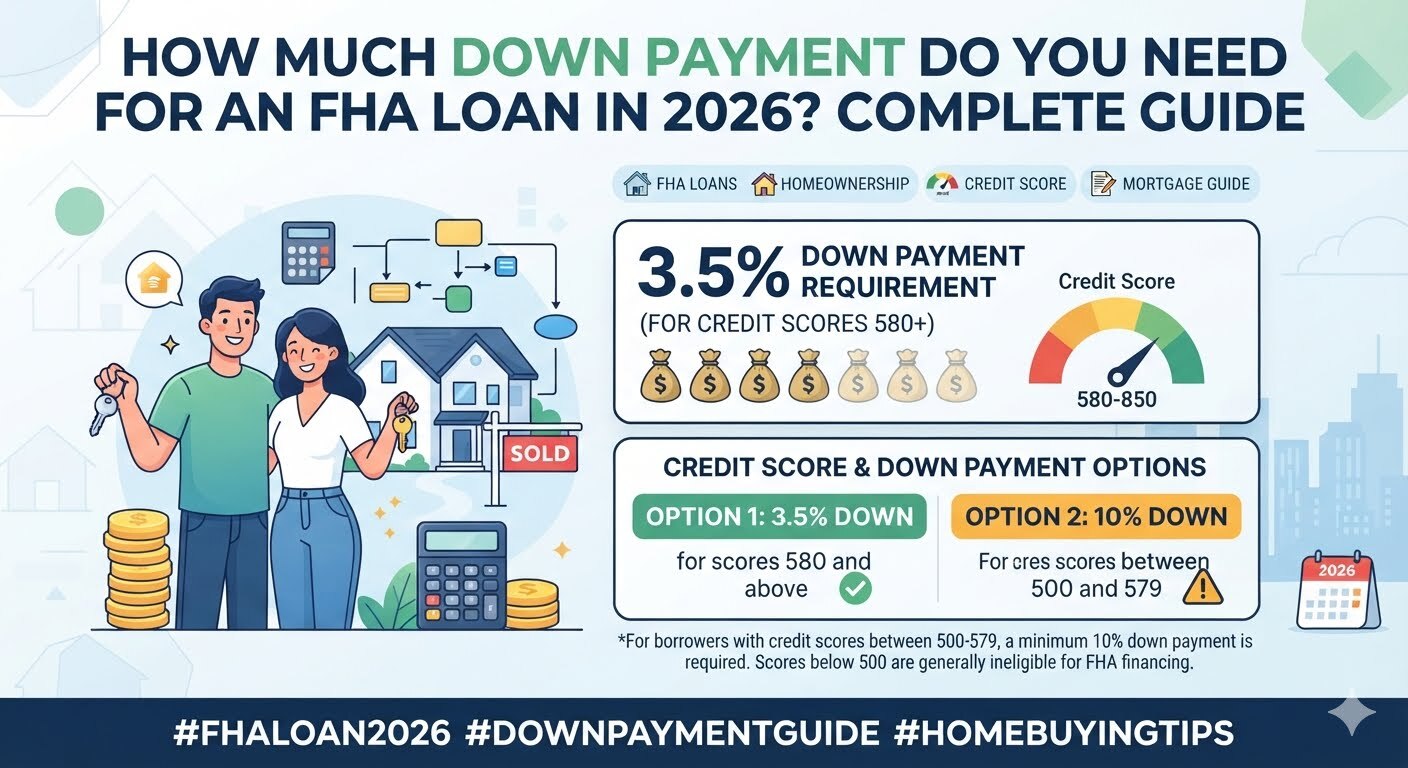

Learn how much down payment you need for an FHA loan in 2026. Discover minimum credit score requirements, gift funds, closing costs, and tips for home buyers.
How Much Down Payment Do You Need for an FHA Loan in 2026?
Buying a home is one of the biggest financial decisions you will ever make. If saving a large down payment feels difficult, an FHA loan may help make homeownership more affordable. FHA loans are popular because they offer lower down payment requirements and flexible credit guidelines compared to many conventional loans.
In this guide, you will learn exactly how much down payment you need for an FHA loan in 2026, what affects your required amount, and how you can prepare for a successful mortgage application.
What Is an FHA Loan?
An FHA loan is a mortgage insured by the Federal Housing Administration. It is designed to help qualified home buyers purchase a home with a smaller down payment and more flexible lending requirements.
Many first time home buyers choose FHA loans because they make it easier to qualify, although repeat buyers may also be eligible if they meet the program requirements.
How Much Down Payment Do You Need for an FHA Loan?
The minimum down payment depends mainly on your credit score.
Credit Score of 580 or Higher
If your credit score is 580 or above, you may qualify for an FHA loan with a 3.5 percent down payment.
For example:
- Home price: $300,000
- Down payment: $10,500
This is the most common down payment requirement for qualified FHA borrowers.
Credit Score Between 500 and 579
If your credit score falls between 500 and 579, you may still qualify, but you generally need a 10 percent down payment.
For example:
- Home price: $300,000
- Down payment: $30,000
Keep in mind that many lenders have stricter credit requirements than the FHA minimum.
How Your Down Payment Is Calculated
Your required down payment is based on the home’s purchase price.
Here are a few examples:
| Home Price | Three Point Five Percent Down | Ten Percent Down |
|---|---|---|
| $200,000 | $7,000 | $20,000 |
| $300,000 | $10,500 | $30,000 |
| $400,000 | $14,000 | $40,000 |
| $500,000 | $17,500 | $50,000 |
Understanding these numbers can help you set realistic savings goals before you begin shopping for a home.
Can Your Down Payment Come From Gifts?
Yes. FHA guidelines allow eligible gift funds for your down payment.
Gift funds may come from:
- Family members
- Close friends
- Employers
- Approved charitable organizations
- Government assistance programs
The donor must provide proper documentation showing that the money is a gift and does not need to be repaid.
Down Payment Assistance Programs
Many state and local agencies offer down payment assistance programs that can help qualified buyers.
These programs may provide:
- Grants
- Forgivable loans
- Deferred payment loans
- Low interest assistance
Eligibility depends on factors such as income, property location, and purchase price.
If you qualify, these programs can significantly reduce the amount of cash you need at closing.
Do You Need Money for Closing Costs?
Yes. Besides the down payment, you should also budget for closing costs.
Common closing costs include:
- Loan origination fees
- Appraisal fees
- Title insurance
- Recording fees
- Home inspection
- Prepaid taxes
- Homeowners insurance
Many buyers negotiate seller concessions that help cover part of these expenses.
Why FHA Loans Are Popular
FHA loans continue to be one of the most popular mortgage choices because they offer several important benefits.
Lower Down Payment
Qualified borrowers may purchase a home with only 3.5 percent down.
Flexible Credit Requirements
Borrowers with less than perfect credit often have more opportunities to qualify.
Competitive Interest Rates
Many FHA borrowers receive attractive mortgage rates depending on market conditions.
Gift Funds Allowed
Family members and approved donors can help with your down payment.
Available Across the Country
FHA loans are available in every state through approved lenders.
Tips for Saving Your Down Payment
Saving for a home becomes easier with a plan.
Here are a few practical ideas:
Create a Monthly Savings Goal
Set aside a fixed amount every month dedicated only to your home purchase.
Reduce Unnecessary Spending
Cut back on subscriptions, dining out, and impulse purchases.
Pay Down Existing Debt
Lower debt may improve your credit profile and increase your mortgage approval chances.
Improve Your Credit Score
A stronger credit score may help you qualify for the lower 3.5 percent down payment.
Research Assistance Programs
Many buyers qualify for grants they never knew existed.
Is an FHA Loan Right for You?
An FHA loan may be a good choice if you:
- Have limited savings
- Need a lower down payment
- Have average credit
- Want flexible qualification guidelines
- Plan to live in the home as your primary residence
However, every buyer has different financial goals. Comparing FHA loans with conventional loans can help determine which mortgage best fits your situation.
Conclusion
If you are wondering how much down payment you need for an FHA loan, the answer depends largely on your credit score. Most qualified borrowers with a credit score of 580 or higher can purchase a home with just a 3.5 percent down payment. Borrowers with lower scores may still qualify but typically need 10 percent down.
Before buying a home, review your finances, improve your credit if possible, and explore available down payment assistance programs. Preparing ahead of time can make the home buying process smoother and help you move into your new home with confidence.
Frequently Asked Questions
1. What is the minimum down payment for an FHA loan?
Most qualified borrowers need only 3.5 percent down with a credit score of 580 or higher.
2. Can I get an FHA loan with no down payment?
No. FHA loans always require a down payment, although assistance programs may help cover it.
3. Can gift money be used for the FHA down payment?
Yes. Eligible gift funds from approved sources may be used if properly documented.
4. Does an FHA loan require mortgage insurance?
Yes. FHA loans generally require both upfront and annual mortgage insurance premiums.
5. Can I qualify with a low credit score?
Possibly. Borrowers with credit scores between 500 and 579 may qualify with a 10 percent down payment if lender requirements are met.
6. Are FHA loans only for first time home buyers?
No. FHA loans are available to both first time and repeat buyers who meet eligibility requirements.
7. Can I combine down payment assistance with an FHA loan?
Yes. Many buyers use approved assistance programs together with FHA financing.






