


Buying your first home is exciting, and it is also the point where most first time buyers ask the same nervous question: how much money to buy first home FHA loan borrowers actually need before they can get the keys. The answer is more than the down payment, and less than many people fear. An FHA loan keeps the down payment small, but you still need cash for closing costs and prepaid items too.
How Much Money to Buy First Home FHA Loan: The Short Answer
For most first time buyers, plan on roughly 7 to 10 percent of the purchase price in cash, or about $21,000 to $30,000 on a $300,000 home, depending on your state, your lender and the seller’s contribution. That number has four parts: the 3.5% down payment, closing costs, prepaid taxes and insurance, and the upfront premium if you pay any of it in cash. Most buyers finance that premium into the loan, so it often adds nothing to cash to close. Seller concessions of up to 6% and down payment assistance can shrink the total a lot.
The Down Payment: 3.5% of the Purchase Price
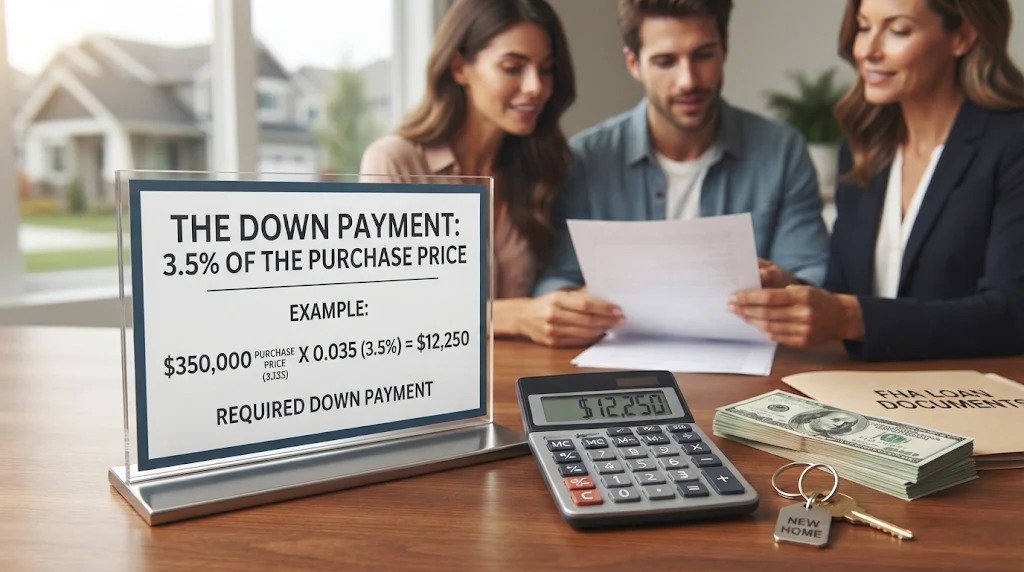
With a credit score of 580 or higher, the minimum down payment is 3.5%: $8,750 on a $250,000 home, $10,500 on a $300,000 home, $14,000 on a $400,000 home. That 3.5% is the starting point for how much money to buy first home FHA loan buyers need. With a score of 500 to 579, the minimum jumps to 10%, so most first time buyers work on credit first. Scores below 500 do not qualify at all.
The money does not have to come entirely from your own savings. FHA allows the whole down payment to come from a family gift, and many state and local assistance programs can cover part or all of it. But the seller cannot pay your down payment. The 3.5% minimum must come from you, a gift, or an assistance program, and your lender will ask where every dollar came from, so keep gift letters and bank statements ready.
Closing Costs: The Part Most First Time Buyers Forget
Closing costs are the fees charged by the lender and the other parties who handle your purchase, and the cost most first time buyers underestimate. For an FHA loan, expect roughly 2% to 5% of the price: about $6,000 to $15,000 on a $300,000 home, with most buyers near the middle. They include the origination fee, appraisal, credit report, title search and insurance, recording fees, and attorney or settlement fees where they apply.
The exact total depends on where you live, because title and recording costs vary a lot by state, and on your lender, because origination fees are not the same everywhere. Your lender must send you a Loan Estimate within three business days of your application, listing every closing cost line by line.
Compare it with Loan Estimates from other lenders before you lock your rate. That comparison is part of working out how much money to buy first home FHA loan buyers really need, because lender fees are the one cost you can shop. Watch out for discount points too. A point costs 1% of the loan amount and buys your rate down, but for a first time buyer short on cash, points rarely make sense.
Upfront MIP: The FHA Fee You Can Usually Finance
Every FHA loan carries an upfront mortgage insurance premium, or UFMIP, of 1.75% of the base loan amount. On a $300,000 purchase with 3.5% down, the base loan is $289,500, so the premium is about $5,066. You almost never pay this in cash. Nearly every borrower adds it to the loan balance, making the total loan about $294,566, and pays it off slowly over the life of the loan.
FHA also charges an annual premium, billed monthly, of 0.55% of the loan balance for most 30 year loans with less than 5% down. With less than 10% down, it stays for the life of the loan. It is not part of your cash to close, but it affects your monthly budget. See our guide to FHA mortgage insurance costs for the full breakdown.
Prepaids and Escrow: Insurance and Taxes Paid Early
Prepaid items are the third bucket of cash to close, and they are easy to confuse with closing costs. Prepaids are not fees. They are real bills you would pay anyway, collected early and held in escrow so your lender can pay them on time: homeowners insurance, property taxes, and prepaid interest. Your lender will usually ask for the first year of insurance paid in full at closing, plus two to three months of insurance and taxes as a cushion.
In a low tax state, prepaids might be $2,000 to $3,000. In a high tax state, they can reach $5,000 or more on the same priced home. Prepaids are a big part of how much money to buy first home FHA loan buyers need in cash, so ask your lender for a written estimate early, because this is the number that varies most.
How Much Money to Buy First Home FHA Loan: A Worked Example
All figures below are illustrative, based on a $300,000 purchase price and typical cost ranges. Your own numbers will differ by state, lender, and home price.
| Cost component | Amount on a $300,000 home |
|---|---|
| Down payment (3.5%) | $10,500 |
| Closing costs (about 2.5%) | $7,500 |
| Prepaids and escrow (insurance and taxes) | $3,000 |
| Upfront MIP (1.75% of base loan) | $0 in cash, about $5,066 financed into the loan |
| Total cash to close | About $21,000 |

That $21,000 is roughly 7% of the price, and the number to aim for when you start saving. If the seller pays 3% toward your closing costs, $9,000, your cash to close drops to about $12,000. If an assistance program covers your $10,500 down payment too, your out of pocket cash can fall to a few thousand dollars, though programs have their own rules, so read them first.
How to Buy Your First Home With Less Cash
Three levers can cut how much money to buy first home FHA loan buyers need at closing. Seller concessions are the biggest lever. FHA allows the seller to contribute up to 6% of the price toward your closing costs, prepaids, discount points and the upfront premium, or up to $18,000 on a $300,000 home. In practice, sellers agree to 2% to 3% far more often than the full 6%, and in a hot market they may agree to nothing. Ask your agent to request a seller credit in your offer. The credit cannot exceed your actual closing costs, and it can never cover the down payment.
Down payment assistance is the second lever. Most states run first time buyer programs offering grants or low interest second loans for the down payment and closing costs. Some grants never have to be repaid. Others are forgivable after you live in the home for a set number of years. Check your state housing finance agency website, then ask your lender which programs they work with.
Gift funds are the third lever. A family member can gift you the full down payment, and FHA allows it, but the donor must sign a gift letter and your lender will want a paper trail. Never accept a gift in cash with no records, because an undocumented deposit can delay or even kill your approval. Finally, shop lenders. Rates and closing costs differ by thousands of dollars on the same loan, so get Loan Estimates from at least three FHA approved lenders on the same day.
Moving Costs and Reserves
Cash to close is not the total cash you need. Moving costs, utility deposits, furniture, and the small repairs every first home seems to need will eat into your savings in the first month. Budget $1,500 to $3,000 for the move, more if you are hiring movers or buying appliances, and keep one or two months of mortgage payments in reserve after closing, so a surprise bill does not put your new mortgage at risk. That is on top of how much money to buy first home FHA loan buyers need for cash to close.
The Bottom Line
So, how much money to buy first home FHA loan buyers need? For most people, about 7% to 10% of the purchase price in cash, with roughly $21,000 covering a $300,000 home before seller help or assistance. The down payment is only the first part. Closing costs, prepaids and escrow make up the rest, and the upfront premium is usually financed, not paid in cash. Check your county’s 2026 FHA loan limit first: $541,287 in most counties, up to $1,249,125 in high cost areas. Get your Loan Estimates early, ask your agent about a seller credit, and check your state’s assistance programs.
FAQs
How much money do I need to buy my first home with an FHA loan?
About 7% to 10% of the purchase price in cash. On a $300,000 home, that is roughly $21,000 before seller concessions or assistance.
Is the 3.5% down payment the only cash I need for an FHA loan?
No. Add closing costs of roughly 2% to 5% of the price, plus prepaid insurance and taxes in escrow. The upfront premium is usually financed into the loan.
What is the minimum credit score for a 3.5% down FHA loan?
You need a score of 580 or higher. With a score of 500 to 579, FHA requires 10% down. Scores below 500 do not qualify.
Can the seller pay my closing costs on an FHA loan?
Yes, up to 6% of the price toward closing costs, prepaids, discount points and the upfront premium. Seller money cannot cover your down payment.
Can I use gift money for my FHA down payment?
Yes, the entire down payment can come as a gift from a family member. The donor must sign a gift letter and your lender will need a paper trail.
How much are FHA closing costs on a $300,000 home?
Roughly $6,000 to $15,000, with most buyers near $7,500. Your Loan Estimate lists every fee.
Do I have to pay the upfront MIP in cash at closing?
Almost never. The upfront premium of 1.75% of the base loan is normally added to your loan balance. Very few first time buyers pay it in cash.
What are prepaid items on an FHA loan?
Prepaids are homeowners insurance and property taxes collected early at closing and held in escrow. They typically add $2,000 to $5,000 to cash to close.
What is the 2026 FHA loan limit?
For 2026, the limit for a one unit home is $541,287 in most counties and up to $1,249,125 in high cost counties. Check HUD’s FHA pages for your exact county limit.
Can down payment assistance cover my FHA down payment?
In many states, yes. State and local programs offer grants or low interest second loans covering part or all of the down payment and some closing costs.
How much should I keep in savings after closing on my first home?
At least one to two months of mortgage payments, plus $1,500 to $3,000 for moving costs and first month expenses.
Does an FHA loan require mortgage insurance for the life of the loan?
With less than 10% down, annual MIP stays for the life of the loan. With 10% or more down, it drops off after 11 years. Many borrowers later refinance into a conventional loan.
#FHALoan #FirstTimeHomeBuyer #FHADownPayment #CashToClose #FHAClosingCosts #BuyYourFirstHome






