

Learn how to get an FHA loan with a 580 credit score in 2026. Discover FHA requirements, down payment rules, approval tips, and helpful mortgage guidance.
Can You Get an FHA Loan With a 580 Credit Score in 2026?
Buying a home with a lower credit score can feel challenging, but an FHA loan can make homeownership possible for many borrowers. If you have a 580 credit score, you may qualify for an FHA loan with a lower down payment compared to many conventional mortgage options.
The Federal Housing Administration created FHA loans to help more people access affordable home financing. These loans are popular among buyers who may not have perfect credit or a large amount of savings.
In 2026, borrowers with a 580 credit score can still have a strong opportunity to qualify for an FHA mortgage if they meet other requirements, including income, debt, employment history, and property guidelines.
What Is the Minimum Credit Score for an FHA Loan?
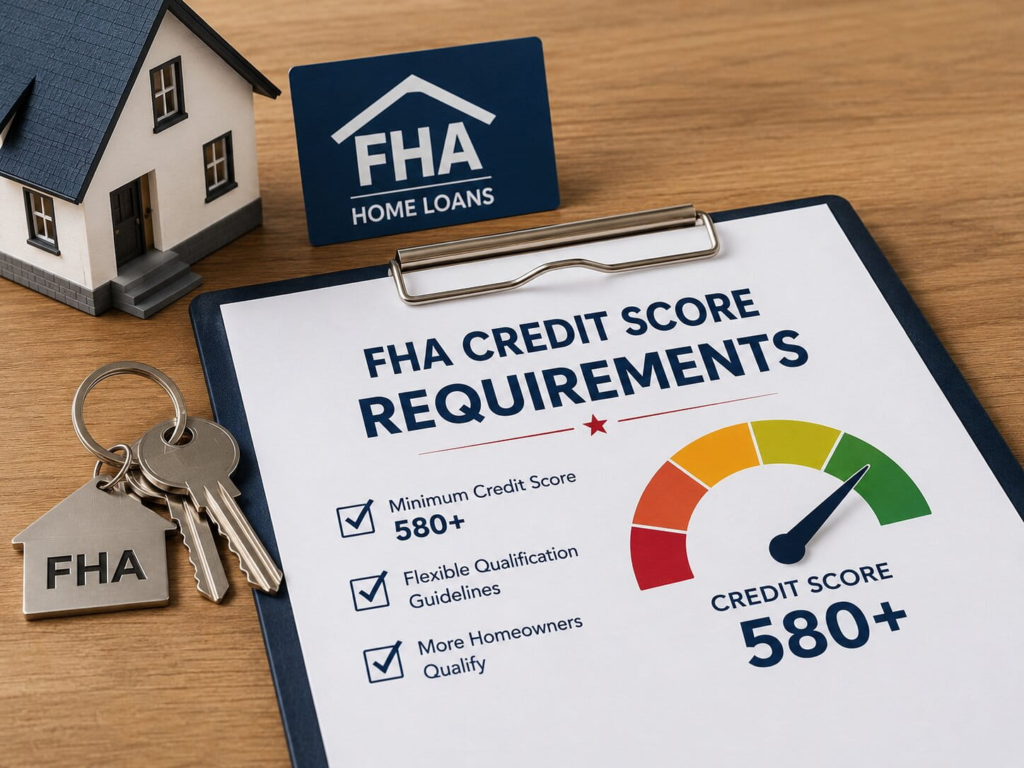
The FHA does not require a perfect credit score. One of the biggest advantages of an FHA mortgage is its flexible credit requirements.
Generally, FHA guidelines allow:
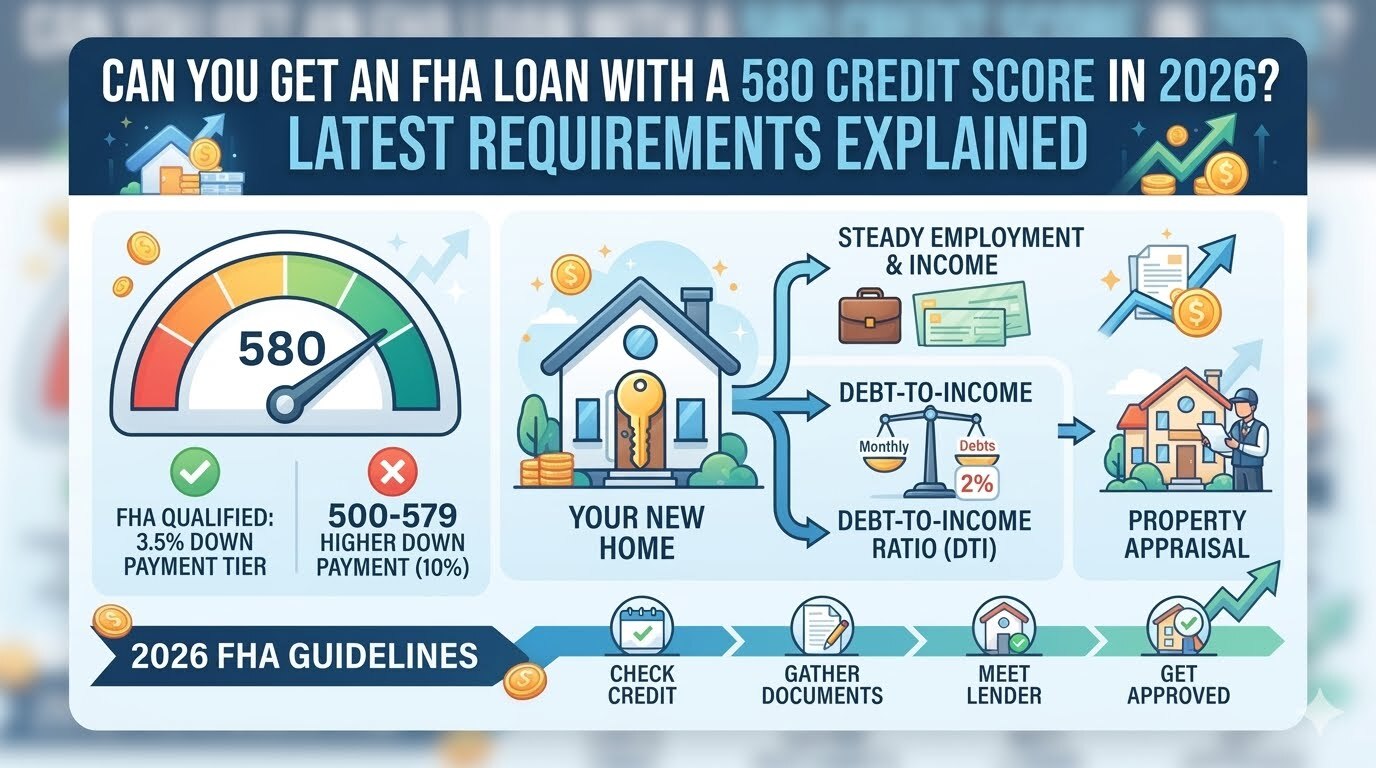
- A credit score of 580 or higher with a 3.5% down payment
- A credit score between 500 and 579 with a 10% down payment
If your credit score is 580, you may qualify for the minimum down payment requirement. However, lenders may have their own requirements that are stricter than FHA guidelines.
Some lenders may look at additional factors, such as your income stability, debt payments, savings, and recent credit history before approving your application.
How Does a 580 Credit Score Affect FHA Loan Approval?
A 580 credit score meets the basic FHA credit requirement, but approval depends on more than your score.
Mortgage lenders usually review:
Income and Employment History
Lenders want to see that you have a reliable source of income to make monthly mortgage payments. Stable employment and consistent earnings can strengthen your application.
Debt to Income Ratio
Your debt to income ratio compares your monthly debt payments with your gross monthly income. A lower ratio can improve your chances of approval.
Payment History
Late payments, collections, or recent credit problems may affect your mortgage application. Showing responsible credit behavior before applying can help.
Down Payment Savings
With a 580 credit score, FHA guidelines may allow a 3.5% down payment. For example, if you purchase a $250,000 home, your minimum down payment could be around $8,750.
FHA Loan Requirements 2026 With a 580 Credit Score
To qualify for an FHA loan with a 580 credit score, borrowers usually need to meet several requirements.
Minimum Credit Score
A 580 credit score is generally the minimum score needed for the 3.5% down payment option.
Down Payment
FHA borrowers with a credit score of 580 or higher may qualify for a 3.5% down payment.
The down payment can sometimes come from:
- Personal savings
- Gift funds from an approved source
- Down payment assistance programs
Mortgage Insurance
FHA loans require mortgage insurance. This includes an upfront mortgage insurance premium and annual mortgage insurance payments.
Mortgage insurance helps protect lenders and allows them to offer more flexible qualification rules.
Property Requirements
The home must meet FHA property standards. The property must be safe, secure, and suitable for living.
Eligible properties may include:
- Single family homes
- Certain condominiums
- Multi unit properties within FHA guidelines
Can You Get an FHA Loan With Bad Credit and a 580 Score?
Yes, many borrowers with a 580 credit score can qualify for an FHA loan. However, having a 580 score does not guarantee approval.
If your credit history includes past financial issues, lenders may review:
- How recent the problems were
- Whether your accounts are currently paid on time
- Your current debt level
- Your overall financial situation
Improving your credit before applying may help you receive better loan terms and increase your approval chances.
How to Improve Your Chances of FHA Approval With a 580 Credit Score
If you are planning to apply for an FHA mortgage, consider these steps:
Pay Bills on Time
Your payment history plays a major role in your credit score. Consistent on time payments can help improve your credit profile.
Reduce Credit Card Balances
Lower credit card balances can improve your credit utilization ratio and make your application stronger.
Avoid Opening New Credit Accounts
Applying for new credit before getting a mortgage may affect your credit score and create additional debt.
Save Extra Money
Although FHA loans may require a low down payment, having additional savings can help cover closing costs and unexpected expenses.
Get Pre Approved
A mortgage pre approval helps you understand how much you can afford and shows sellers that you are a serious buyer.
FHA Loan With 580 Credit Score vs Conventional Loan
Many borrowers compare FHA loans with conventional mortgages when choosing a home loan.
An FHA loan may be better for borrowers who:
- Have a lower credit score
- Want a smaller down payment
- Need flexible qualification rules
A conventional loan may be better for borrowers who:
- Have stronger credit
- Want to avoid FHA mortgage insurance
- Can afford a larger down payment
The right option depends on your financial goals, credit history, and home buying plans.
Benefits of Getting an FHA Loan With a 580 Credit Score
An FHA loan can provide several benefits, including:
- Lower credit score requirements
- Smaller down payment options
- Flexible qualification guidelines
- Ability to use gift funds
- Competitive mortgage rates
For many buyers, FHA financing provides a realistic path toward owning a home.
Common Mistakes to Avoid Before Applying
Before submitting your FHA loan application, avoid these mistakes:
- Making large purchases before closing
- Missing credit card payments
- Changing jobs without planning
- Applying for multiple new loans
- Ignoring your credit report errors
Preparing your finances before applying can improve your mortgage experience.
Conclusion: Is an FHA Loan Possible With a 580 Credit Score?
Yes, you can get an FHA loan with a 580 credit score in 2026 if you meet other FHA and lender requirements. A 580 score may allow you to qualify for a 3.5% down payment, making homeownership more accessible.
Your credit score is only one part of the mortgage approval process. Income, debt, savings, and financial history also play important roles.
If you are considering an FHA mortgage, compare your options, review your finances, and speak with a qualified mortgage professional to understand your best path forward.
Frequently Asked Questions About FHA Loans With a 580 Credit Score
1. Can I get an FHA loan with a 580 credit score?
Yes. Many borrowers with a 580 credit score may qualify for an FHA loan with a 3.5% down payment if they meet other lender requirements.
2. How much down payment is required for an FHA loan with a 580 credit score?
Borrowers with a 580 credit score may qualify for a minimum down payment of 3.5% of the home purchase price.
3. Is 580 a good credit score for buying a house?
A 580 credit score is considered acceptable for FHA financing, but improving your score may help you access more loan options.
4. Can I get an FHA loan with a 580 credit score and no savings?
You may qualify for assistance programs or gift funds, but you still need to meet FHA and lender requirements.
5. Do all lenders approve FHA loans with a 580 credit score?
No. Some lenders may have additional credit requirements beyond FHA guidelines.
6. Can I buy a house with a 580 credit score?
Yes. FHA loans are designed to help borrowers with lower credit scores become homeowners.
7. How can I increase my chances of FHA approval?
Improve your credit habits, reduce debt, maintain stable income, save money, and get mortgage pre approval before shopping for a home.






