

FHA Loans for Manufactured Homes: What You Need to Know before you shop can save you from one of the most frustrating problems in manufactured housing: finding a home you can afford, only to discover that its legal classification, foundation, or paperwork prevents FHA financing.
The good news is that manufactured homes can qualify for FHA financing. However, the rules depend on how the home and land are classified and which FHA program is being used.
In simple terms, a manufactured home can qualify for FHA financing when it meets FHA property standards and the applicable program requirements. Title II financing generally requires the home to be treated as real estate, permanently founded, and compliant with HUD manufactured housing requirements. FHA Title I can provide another option for certain manufactured home purchases, including situations where the borrower leases the lot.
That distinction matters. A manufactured home sitting on owned land with an FHA compliant permanent foundation is a very different financing situation from a home in a community where the land is leased.
What Are FHA Loans for Manufactured Homes?
FHA financing is backed by the Federal Housing Administration and is offered through FHA approved lenders. Manufactured housing can be financed through different FHA programs depending on the property and transaction.
FHA Title II financing
For a standard FHA mortgage secured by the home and property, HUD’s current Handbook 4000.1 says an eligible manufactured home must:
- Be designed as a one family dwelling.
- Have at least 400 square feet of floor area.
- Have a HUD Certification Label or qualifying label verification.
- Have been constructed on or after June 15, 1976.
- Be classified as real estate under applicable state law.
- Remain on a permanent chassis.
- Be designed for use with a permanent foundation that complies with HUD’s Permanent Foundations Guide for Manufactured Housing.
- Have been transported directly from the manufacturer or dealership to the site.
These requirements are important because the word “manufactured” does not automatically make a property FHA eligible.
FHA Title I financing
Title I works differently.
HUD says Title I manufactured home loans can finance a manufactured home unit, a manufactured home lot, or a combination of the home and lot. The home may be classified as personal property or real estate under this program.
Title I can therefore be relevant when the borrower does not own the land, although lender participation and program requirements still matter.
What Are the FHA Requirements for a Manufactured Home?
The property has to satisfy both the general FHA underwriting requirements and manufactured housing requirements.
Here are the major property issues to check before making an offer.
1. The home must meet the HUD age requirement
For FHA Title II mortgage insurance, the manufactured home generally must have been constructed on or after June 15, 1976, when federal manufactured housing construction and safety standards took effect. HUD requires evidence through the HUD Certification Label or acceptable label verification.
If the label is missing, that does not automatically mean financing is impossible. HUD’s current handbook provides for label verification in appropriate circumstances.
2. The home must have at least 400 square feet
HUD’s current Title II standard requires a manufactured home to have at least 400 square feet of floor area.
This is an easy item to check before spending money on inspections, appraisal, or other due diligence.
3. A permanent foundation is critical
This is one of the biggest differences between an FHA eligible manufactured home and a home that may not qualify for standard FHA mortgage financing.
The foundation must comply with HUD’s Permanent Foundations Guide for Manufactured Housing, commonly called the PFGMH. Under the current FHA handbook, the lender must obtain certification from an appropriately licensed engineer or architect confirming compliance.
This is why simply seeing concrete blocks, piers, tie downs, or skirting around a home should not be treated as proof of FHA eligibility.
The foundation needs to satisfy the applicable engineering and HUD requirements.
4. The home must qualify as real estate for Title II
For standard FHA Title II mortgage financing, the manufactured home and site generally need to exist together as a real estate entity under state law.
This makes the ownership structure extremely important.
Before purchasing, verify:
- Who owns the land?
- How is the home titled?
- Has the home been permanently affixed?
- Does state or local law classify the home as real property?
- Are there recorded documents showing the home has been converted to real estate where required?
These questions can prevent expensive surprises late in the transaction.
Can You Get FHA Financing Without Owning the Land?
Sometimes, yes. But the answer depends heavily on the FHA program and property structure.
HUD’s Title I program allows manufactured homes to be placed on leased lots. HUD states that the initial lease term must generally be at least three years and that the lease must provide at least 180 days of advance written notice if the lease is terminated.
This is an important distinction from the standard Title II mortgage structure.
A manufactured home in a community is not automatically disqualified from every FHA program simply because the borrower does not own the land. However, lenders may have their own requirements, and not every lender offers every manufactured housing product.
That lender availability issue is a major practical consideration.
Example: owned land vs. leased land
Imagine two buyers each purchase a $200,000 manufactured home.
Buyer A purchases the home together with a parcel of land and the home is permanently installed on an FHA compliant foundation. The property is classified appropriately as real estate.
Buyer B purchases a manufactured home in a community but leases the underlying lot.
The two transactions may look similar to the buyer, but they can fall under very different financing structures.
HUD specifically recognizes manufactured homes on leased lots under Title I, while lender participation and program rules can limit the available choices.
How Much Down Payment Do You Need?
The minimum down payment for an FHA purchase loan is commonly 3.5% for borrowers who meet the applicable 580 credit score standard. Borrowers with credit scores from 500 to 579 generally face a 10% minimum down payment under FHA’s basic credit score and LTV framework.
However, do not assume that the FHA minimum automatically applies to every manufactured home transaction.
The lender can impose additional requirements, and Title I manufactured home financing has its own loan limits, minimum cash investment, credit, and LTV rules. HUD specifically identifies these factors when determining Title I maximum loan amounts.
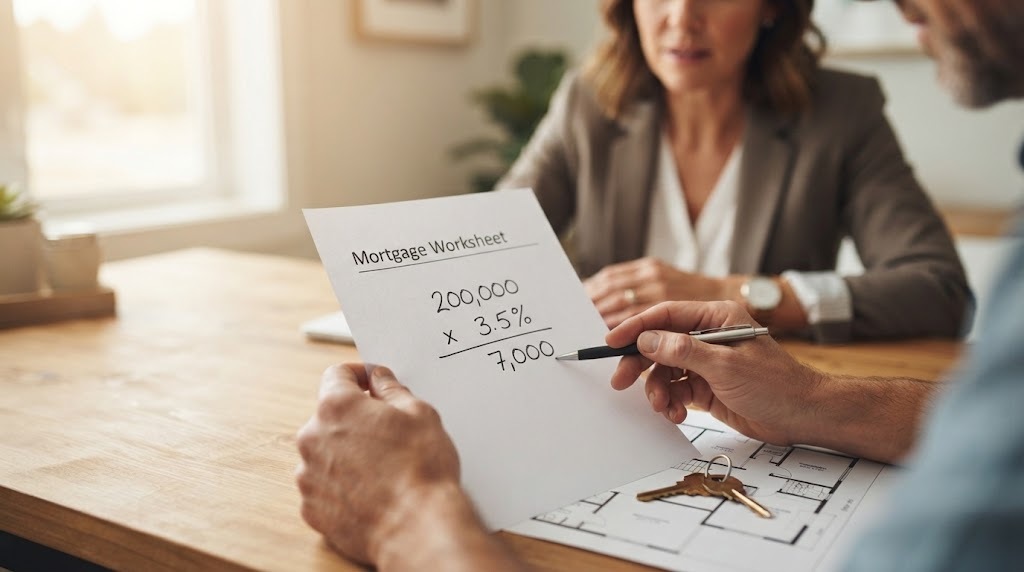
For example, if a qualifying FHA purchase required a 3.5% down payment on a $200,000 purchase price, the minimum would be:
$200,000 × 3.5% = $7,000
That is only the down payment. Buyers should separately budget for closing costs, prepaid expenses, inspection costs, appraisal expenses, moving costs, and potential property repairs.
What About FHA Mortgage Insurance?
FHA loans generally involve mortgage insurance premiums.
This is an important cost to consider when comparing FHA financing with other options.
A manufactured home buyer should look beyond the advertised interest rate and calculate the complete monthly housing payment, including:
- Principal
- Interest
- FHA mortgage insurance
- Property taxes
- Homeowners insurance
- Lot rent, if applicable
- Any applicable community fees
A lower purchase price does not necessarily mean a lower total monthly payment.
What Can Cause an FHA Manufactured Home to Be Rejected?
Many financing problems are caused by property issues rather than the borrower’s income or credit.
Common red flags include:
Missing HUD Certification Label
The lender may need acceptable label verification if the original HUD label is missing. HUD’s current handbook specifically addresses this situation.
Foundation problems
A foundation that looks permanent may still fail the applicable engineering or HUD requirements.
Unpermitted additions
Porches, rooms, garages, decks, or other additions can create appraisal and foundation issues. HUD’s current handbook says additions and alterations must be addressed when applicable to the foundation certification.
Title problems
If the home is still treated as personal property when a Title II transaction requires real estate treatment, the transaction can become complicated.
Poor property condition
The home must meet applicable FHA property standards. Safety, structural, mechanical, and other deficiencies can affect eligibility and may need to be corrected before closing.
Multiple relocations or unclear history
A home’s transportation and installation history can matter. HUD’s Title II requirements include direct transportation from the manufacturer or dealership to the site.
This is one area where buyers should let an experienced manufactured housing lender review the property before assuming it qualifies.
Manufactured Home vs. Modular Home: What Is the Difference?
Manufactured and modular homes are often confused, but they are not the same thing.
A manufactured home is constructed under the federal HUD Code and carries the applicable HUD certification.
A modular home is generally constructed to state or local building codes rather than the federal manufactured housing standards.
That distinction affects financing, appraisal, title, and property classification.
A modular home that is permanently installed and legally classified as real property may generally be financed similarly to other residential real estate, subject to the applicable FHA requirements.
A Better Way to Check FHA Eligibility Before You Buy
One of the most useful lessons from manufactured housing transactions is that property eligibility should be checked before the buyer becomes financially committed.
A practical pre offer checklist is:
- Confirm the construction date.
- Locate the HUD Certification Label.
- Confirm the home’s square footage.
- Determine whether the land is owned or leased.
- Verify the home’s title classification.
- Ask whether the home has been permanently installed.
- Check for foundation documentation.
- Identify additions or alterations.
- Confirm utilities and site suitability.
- Have an FHA experienced lender review the property.
- Order the appraisal when appropriate.
- Resolve title or foundation problems before closing.
This sequence can save time because manufactured home financing often depends on documents that a typical buyer may never think to request.
HUD also maintains its current FHA Single Family Housing Policy Handbook 4000.1, which lenders use for FHA policy requirements.
Are FHA Loans a Good Option for Manufactured Homes?
For the right buyer and property, FHA financing can make manufactured housing more accessible.
Potential advantages
- Lower minimum down payment for qualifying borrowers.
- Flexible credit standards compared with some conventional options.
- FHA financing may work for qualifying manufactured homes on owned land.
- Title I can provide an option for certain manufactured homes and leased lots.
- Down payment assistance may be available depending on the program and location.
Potential disadvantages
- Mortgage insurance adds cost.
- Property requirements can be stricter than buyers expect.
- Foundation certification may be necessary.
- Some lenders do not offer every manufactured housing FHA product.
- Loan limits and program rules can restrict financing.
- Title and real estate classification can complicate transactions.
The biggest takeaway is that FHA financing is not simply a question of whether the house is “manufactured.” The home’s construction, foundation, title, land arrangement, and documentation all matter.
FHA Loans for Manufactured Homes: What Should You Do First?
If you are considering an FHA financed manufactured home, start with the property rather than the sales price.
Ask the seller or listing agent for the home’s construction date, HUD label information, title details, foundation documentation, and information about the land.
Then give those details to an FHA experienced lender.
If the home is on leased land, specifically ask about FHA Title I manufactured home financing rather than assuming a standard FHA mortgage will apply. HUD confirms that Title I can finance a manufactured home unit, lot, or combination and can accommodate certain leased lot arrangements.
For a home on owned land, ask the lender to review the permanent foundation and real estate classification early in the process.
That simple step can prevent you from spending weeks pursuing a property that cannot meet the financing requirements.
Conclusion
FHA Loans for Manufactured Homes can be a practical path to homeownership, but eligibility depends on much more than the buyer’s credit score and down payment.
For standard FHA Title II financing, key requirements include the home’s HUD certification, construction date, minimum 400 square foot size, real estate classification, permanent chassis, and compliant permanent foundation.
For buyers who do not own the land, FHA Title I may provide another financing route, including certain leased lot situations.
The smartest move is to verify the property’s financing eligibility before making a nonrefundable commitment. Review the title, HUD label, foundation, land arrangement, and property condition with an experienced FHA lender.
FAQ Section
Can you get FHA Loans for Manufactured Homes?
Yes. Qualifying manufactured homes can be financed through FHA programs. Standard Title II financing has specific requirements for construction date, HUD certification, square footage, real estate classification, permanent chassis, and permanent foundation. FHA Title I provides separate financing options for certain manufactured homes.
What year does a manufactured home have to be built for FHA?
For FHA Title II mortgage insurance, the manufactured home generally must have been constructed on or after June 15, 1976, and comply with the applicable federal manufactured housing standards.
Does an FHA manufactured home need a permanent foundation?
Yes, for standard FHA Title II financing, the manufactured home must be designed for use with a permanent foundation that complies with HUD’s applicable requirements. Current FHA guidance also addresses foundation certification by a licensed engineer or architect.
Can I get an FHA loan for a manufactured home if I lease the land?
Potentially. HUD’s Title I manufactured home program permits certain manufactured homes to be placed on leased lots. HUD specifies lease requirements, including a generally required initial lease term of three years and advance notice provisions for termination. Lender availability and other program requirements still apply.
What is the minimum square footage for an FHA manufactured home?
For FHA Title II mortgage insurance, a manufactured home must have at least 400 square feet of floor area.
Is a manufactured home the same as a modular home?
No. Manufactured homes are built under federal HUD manufactured housing standards, while modular homes are generally built to applicable state or local building codes. Their financing and property classification can therefore differ.







One Response