
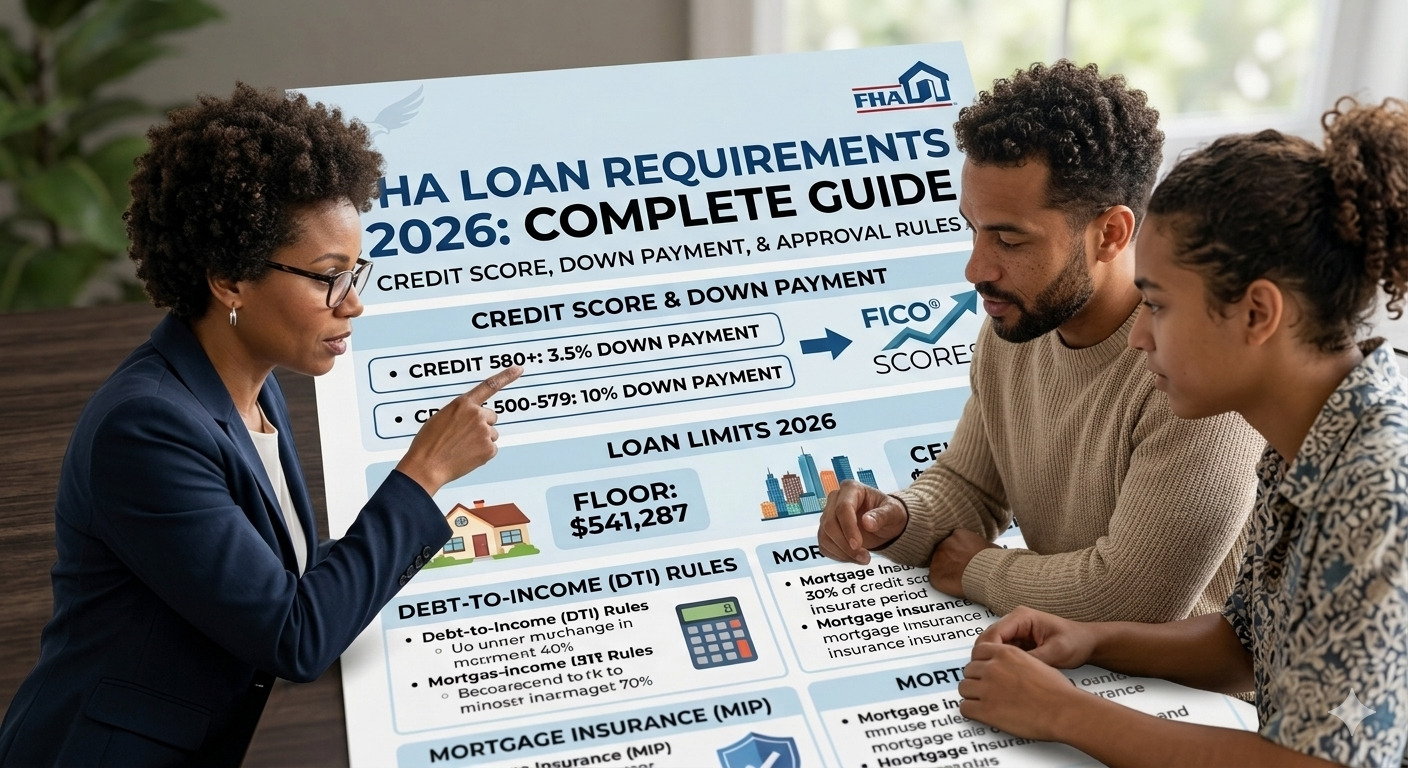

Buying a home remains one of the biggest financial decisions in 2026. Many people look for flexible mortgage options that make homeownership easier and more realistic. FHA loans continue to be one of the most trusted programs for this purpose because they offer lower barriers and simpler qualification standards.
This guide explains FHA loan requirements 2026 in a clear and practical way so you can understand exactly what lenders expect and how you can prepare for approval.
What Is an FHA Loan
An FHA loan is a mortgage backed by the Federal Housing Administration. It is designed to help people who may not qualify for traditional home loans due to limited savings or lower credit history.
Because the loan is insured by the government, lenders feel more secure approving borrowers who might otherwise be considered higher risk. This makes FHA loans a strong option for many buyers in 2026.
FHA Loan Requirements 2026 Overview
To qualify for an FHA Mortgage loan in 2026, you must meet several basic requirements. These rules help lenders decide if you are financially ready to take on a mortgage.
Key requirement areas include:
• Credit score evaluation
• Down payment ability
• Stable income history
• Debt to income balance
• Property condition standards
Each of these factors plays an important role in the approval process.
Credit Score Requirements for FHA Loan 2026
Your credit score is one of the most important parts of your application. It shows lenders how reliably you manage debt.
In 2026, general guidelines include:
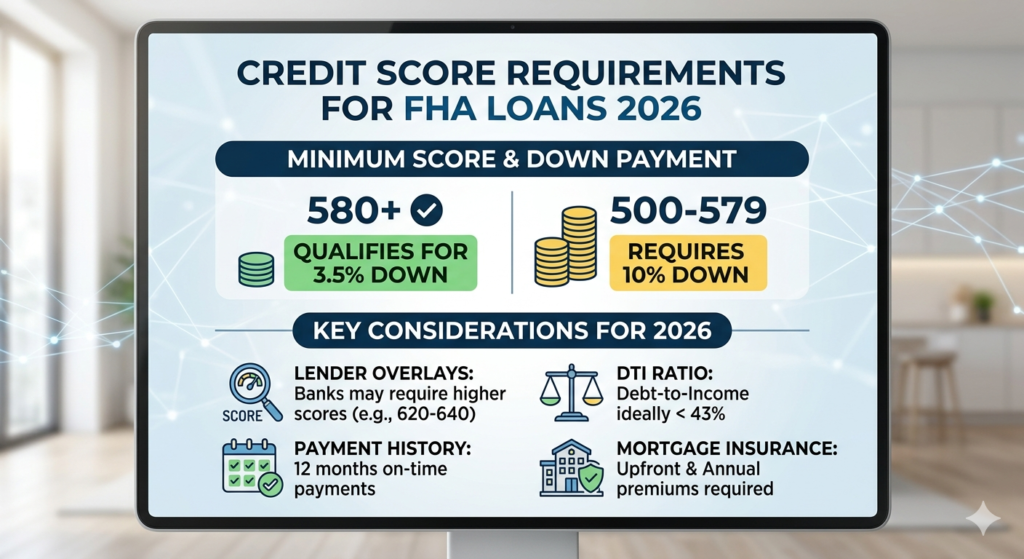
• A credit score of 580 or higher may qualify you for a lower down payment option
• A credit score between 500 and 579 may still qualify with a higher down payment
• Some lenders may apply stricter rules based on overall financial profile
Even if your credit is not strong, FHA loans remain more flexible compared to many other mortgage types.
How to Improve Your Credit Profile
Improving your credit before applying can significantly increase your approval chances. Focus on:
• Paying bills on time every month
• Reducing credit card balances
• Avoiding new loans or credit applications
• Checking your credit report for errors and fixing them
Small improvements can make a big difference in loan decisions.
Down Payment Requirements in 2026
One of the biggest advantages of FHA loans is the low down payment requirement. This helps many buyers who do not have large savings Mortgage Guider Hub.
Typical requirements include:
• Around 3.5 percent of the home price for borrowers with stronger credit
• Around 10 percent or more if credit score is lower than 580
This flexibility allows more people to enter the housing market sooner instead of waiting years to save a large amount.
Income and Employment Requirements
Lenders want to make sure you have a stable income to repay your loan comfortably.
In most cases, you need:
• At least two years of steady employment history
• Verifiable income through pay records or tax documents
• A stable or improving financial situation
If you are self employed, you may still qualify, but you will need to provide extra financial documentation to prove consistent earnings.
Debt to Income Ratio Requirements
Debt to income ratio is the comparison between your monthly debt payments and your monthly income. It helps lenders understand how much financial pressure you already carry.
For FHA loans in 2026:
• Most lenders prefer a ratio of 43 percent or lower
• Some borrowers may qualify with higher ratios if they have strong financial strengths in other areas
Keeping your debt low before applying can improve your chances of approval.
Property Requirements for FHA Loans
The home you want to buy must also meet FHA property standards. This ensures the house is safe and suitable for living.
The property must:
• Be safe and structurally strong
• Have proper water, electricity, and sanitation systems
• Meet basic livability standards
• Pass an FHA approved appraisal inspection
If the property does not meet these conditions, repairs may be required before loan approval.
Additional FHA Loan Eligibility Rules
Beyond credit and income, there are other important rules to keep in mind.
You must:
• Use the home as your primary residence
• Provide valid identification and legal residency proof
• Be able to cover closing costs or negotiate assistance
• Follow waiting periods after bankruptcy or foreclosure if applicable
These rules ensure the program is used for genuine homeownership purposes.
Benefits of FHA Loans in 2026
FHA loans remain popular because they offer several advantages that help a wide range of buyers.
Key benefits include:
• Low down payment requirements
• Flexible credit score acceptance
• Easier qualification compared to conventional loans
• Competitive interest rates in many cases
• Support for buyers with limited savings
These benefits make FHA loans a practical option for many households in 2026.
Step by Step FHA Loan Process
Understanding the process can help you prepare better and avoid delays.
Step 1 Pre approval
You share your financial details with a lender and receive an estimate of how much you may qualify for.
Step 2 Home search
You look for a property that fits your budget and meets FHA standards.
Step 3 Full application
You submit all documents including income proof, credit history, and identification.
Step 4 Appraisal and review
The property is inspected to confirm value and safety.
Step 5 Final approval and closing
After approval, you complete the paperwork and officially become a homeowner.
Tips to Increase Approval Chances
If you want to improve your chances of getting approved, focus on preparation.
Helpful strategies include:
• Keep employment stable and consistent
• Reduce outstanding debts before applying
• Save money for down payment and closing costs
• Avoid unnecessary credit activity
• Work with an experienced mortgage lender
Good preparation can speed up approval and reduce stress.
Conclusion
FHA loan requirements 2026 continue to make homeownership more accessible for many people. With flexible credit score rules, low down payment options, and supportive lending standards, FHA loans remain one of the best mortgage choices for buyers entering the housing market.
If you are planning to buy a home, start preparing early by improving your credit, organizing financial documents, and saving for your down payment. Taking these steps will make the approval process smoother and increase your chances of success.
Frequently Asked Questions
What credit score is needed for FHA loan 2026
Most borrowers can qualify with a score of 580 or higher, depending on lender requirements.
How much down payment is required for FHA loans
The down payment can be as low as 3.5 percent for eligible borrowers.
Can I get FHA loan with low credit
Yes, FHA loans are designed to help borrowers with lower credit scores compared to traditional loans.
Do FHA loans require mortgage insurance
Yes, mortgage insurance is usually required to protect the lender.
Can I buy any property with FHA loan
No, the property must be your primary home and meet FHA safety standards.
How long does FHA approval take
The process usually takes a few weeks depending on documentation and appraisal.






