

Learn about FHA Loan in New York 2026 requirements, credit score, down payment, loan limits, and discover the top lenders for home buyers today.
FHA Loan in New York 2026: Latest Requirements and Top Lenders Today
Buying a home in New York can feel challenging because of rising home prices and changing mortgage rates. An FHA Loan in New York is one of the most popular financing options for buyers who need a lower down payment and flexible credit requirements. Whether you are buying your first home or returning to the housing market, an FHA loan can help make homeownership more affordable.
In this guide, you will learn everything about FHA Loan in New York 2026, including eligibility requirements, loan limits, down payment rules, mortgage insurance, and the top lenders that offer competitive financing.
What Is an FHA Loan?
An FHA loan is a mortgage insured by the Federal Housing Administration. It is designed to help borrowers qualify for home financing with more flexible lending requirements than many conventional loans.
Many buyers choose FHA loans because they offer:
- Lower down payment options
- Flexible credit score requirements
- Competitive mortgage interest rates
- Easier qualification standards
- Higher debt to income flexibility
These benefits make FHA loans an excellent option for many New York home buyers.
FHA Loan Requirements in New York 2026
Before applying, it is important to understand the basic FHA loan requirements.
Minimum Credit Score
Most lenders require:
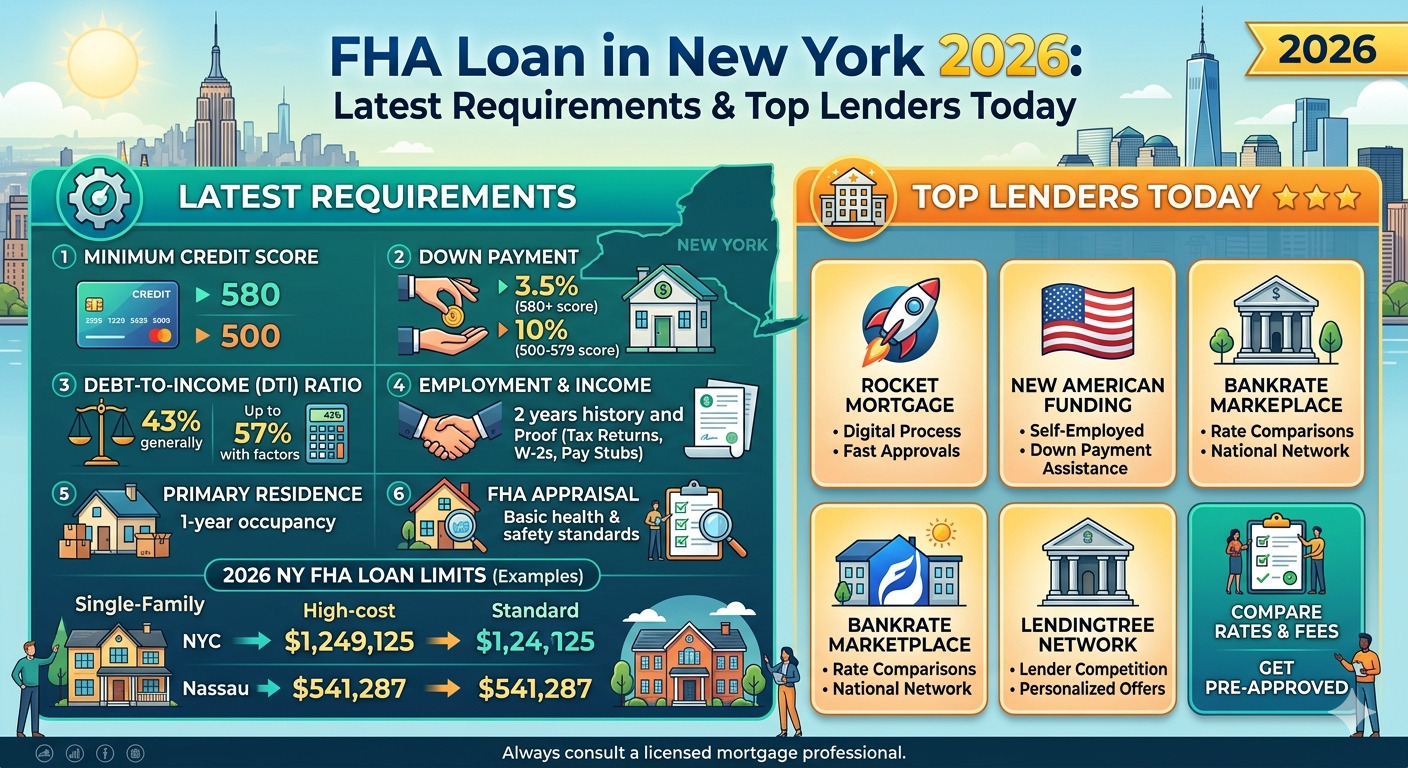
- Credit score of 580 for a 3.5 percent down payment
- Credit score between 500 and 579 may qualify with a 10 percent down payment
Individual lenders may have stricter credit requirements.
Down Payment
One of the biggest advantages of an FHA loan is the low down payment.
Most qualified buyers only need:
- 3.5 percent down with a qualifying credit score
- 10 percent down for lower credit scores
Gift funds from family members are often allowed for the down payment.
Employment and Income
Lenders typically look for:
- Stable employment history
- Reliable monthly income
- Proof of income through tax returns or pay stubs
- Ability to repay the mortgage
Debt to Income Ratio
Many lenders prefer a debt to income ratio below 43 percent, although higher ratios may be approved when compensating factors are present.
FHA Loan Limits in New York 2026
FHA loan limits depend on the county where you plan to buy a home.
Higher cost counties such as New York City generally have much higher loan limits than rural counties.
Before shopping for a home, check the current FHA loan limit for your county to understand your maximum borrowing amount.
Mortgage Insurance Requirements
Every FHA loan includes mortgage insurance.
There are two types:
Upfront Mortgage Insurance Premium
This is usually financed into the loan amount at closing.
Annual Mortgage Insurance Premium
This premium is included in your monthly mortgage payment.
Mortgage insurance helps protect lenders and allows buyers to qualify with lower down payments.
Property Requirements
The home must meet FHA property standards.
Eligible properties include:
- Single family homes
- Approved condominiums
- Multi family properties within FHA guidelines
- Certain manufactured homes
The property must also pass an FHA appraisal to confirm it meets minimum safety and livability standards.
Top FHA Lenders in New York
Choosing the right lender is just as important as choosing the right loan.
Some well known FHA lenders serving New York include:
Rocket Mortgage
Rocket Mortgage is known for its fast online application process and digital mortgage experience.
Pennymac
Pennymac offers competitive FHA loan options along with helpful educational resources.
New American Funding
This lender provides personalized customer service and flexible loan solutions for many home buyers.
Chase
Chase offers FHA loans through its nationwide branch network and online mortgage platform.
Wells Fargo
Wells Fargo remains one of the largest mortgage lenders and continues to offer FHA financing in many markets.
Always compare multiple lenders to find the best interest rate, closing costs, and customer service.
Benefits of an FHA Loan in New York
There are many reasons buyers choose FHA financing.
Lower Down Payment
Many buyers can purchase a home with only 3.5 percent down.
Easier Credit Requirements
FHA loans are often available to borrowers with less than perfect credit.
Competitive Interest Rates
Interest rates are often attractive compared with other mortgage options.
Flexible Qualification
Borrowers with moderate income and existing debt may still qualify.
Potential Drawbacks
While FHA loans offer many advantages, they also have limitations.
Some disadvantages include:
- Mortgage insurance is required.
- Loan limits may restrict higher priced homes.
- Property must meet FHA appraisal standards.
- Mortgage insurance may remain for many years.
Understanding these costs can help you choose the best mortgage for your financial goals.
How to Apply for an FHA Loan
The application process is simple.
Step 1
Check your credit score and financial situation.
Step 2
Gather important documents including:
- Income verification
- Bank statements
- Tax returns
- Employment information
Step 3
Compare offers from multiple FHA approved lenders.
Step 4
Submit your mortgage application.
Step 5
Complete the home appraisal and underwriting process.
Step 6
Close on your new home and receive your keys.
Tips for Getting Approved
You can improve your chances of approval by following these tips.
- Improve your credit score before applying.
- Save for your down payment and closing costs.
- Avoid opening new credit accounts.
- Pay existing debts on time.
- Compare several mortgage lenders before making a decision.
Internal Linking Suggestions
You can strengthen your website SEO by linking this article to related content such as:
- FHA Loan Requirements 2026
- FHA Loan Limits Guide
- FHA vs Conventional Loan
- Best Mortgage Rates Today
- Home Buying Guide for New Buyers
- Mortgage Calculator
Frequently Asked Questions
Who qualifies for an FHA loan in New York?
Most buyers with stable income, acceptable credit, and enough funds for the required down payment may qualify.
What credit score is needed for an FHA loan?
Many borrowers qualify with a credit score of 580 for the minimum down payment, while lower scores may require a larger down payment.
Can I buy a condo with an FHA loan?
Yes. The condominium must meet FHA approval requirements.
How much is the FHA down payment?
Qualified borrowers can purchase a home with as little as 3.5 percent down.
Are FHA interest rates lower than conventional loans?
Interest rates vary, but FHA loans often offer competitive rates, especially for borrowers with moderate credit.
Can I refinance an FHA loan later?
Yes. Many homeowners refinance into another FHA loan or a conventional mortgage when they qualify.
Is mortgage insurance required?
Yes. FHA loans require both upfront and annual mortgage insurance premiums.
Conclusion
An FHA Loan in New York 2026 continues to be one of the best mortgage options for buyers seeking flexible credit requirements and a low down payment. Whether you are purchasing your first home or returning to the housing market, FHA financing can provide an affordable path to homeownership.
Before applying, compare several lenders, review current loan limits, understand mortgage insurance costs, and choose the loan that best fits your financial goals. Careful planning today can help you secure the right mortgage and enjoy long term success as a homeowner.






