

An FHA Cash-Out Refinance can turn part of your home’s equity into cash without selling your property. For qualified homeowners, it replaces the existing mortgage with a larger FHA-insured mortgage and gives you the remaining proceeds after the old loan and eligible costs are paid.
The important question is not simply, “Can I get cash from my home?” It is whether the new mortgage, insurance costs, closing expenses and reduced equity make financial sense for your situation.
In this guide, you will learn exactly how an FHA cash-out refinance works, who can qualify, how much cash you may be able to access, what it costs, and when another option such as a HELOC or home equity loan may be better.
Quick answer: An FHA cash-out refinance lets an eligible homeowner replace an existing mortgage with a new FHA mortgage and receive cash from available home equity. FHA currently limits the new mortgage to 80% of the property’s adjusted value, so you generally need to retain at least 20% equity.
What Is an FHA Cash-Out Refinance?
An FHA cash-out refinance is a refinance transaction insured by the Federal Housing Administration that allows you to borrow more than the balance of your existing mortgage and receive the difference in cash.
For example, suppose:
- Your home is worth $350,000
- Your current mortgage balance is $210,000
- The FHA maximum LTV is 80%
- Maximum new mortgage based on value: $280,000
- Existing mortgage payoff: $210,000
- Potential gross equity withdrawal: $70,000
Your actual cash received could be lower because the transaction may include closing costs, prepaid items and other eligible charges.
You also do not necessarily need an existing FHA mortgage. FHA cash-out refinancing can be used when the current mortgage is conventional or another eligible mortgage type.
Unlike a HELOC or home equity loan, a cash-out refinance replaces your first mortgage rather than adding a second mortgage behind it.
How Does an FHA Cash-Out Refinance Work?
The process is similar to applying for a new mortgage because the lender must evaluate your property and finances.
1. Check your equity
Start with your home’s estimated market value and current mortgage balance.
A simple formula is:
Home equity = Current home value − Mortgage balance
Then calculate the approximate maximum FHA loan:
Maximum FHA loan = Adjusted property value × 80%
Your available cash is approximately:
Maximum new loan − Existing mortgage payoff − Eligible costs = Potential cash to borrower
This is only an estimate. The lender’s appraisal, underwriting decision and final closing figures determine the actual transaction.
2. Apply with an FHA approved lender
The lender will generally review your income, employment, debts, credit profile, assets and mortgage history.
Lenders can apply their own underwriting standards in addition to FHA requirements. That means a lender’s minimum credit score or debt to income expectations may be stricter than the basic FHA framework.
3. Complete the appraisal
An appraisal is important because the property’s value determines how much you can borrow.
If you believe your property is worth $400,000 but the appraisal comes in at $350,000, your borrowing capacity may be substantially lower than expected.
This is one of the most overlooked risks when estimating cash available before applying.
4. Go through underwriting
The lender verifies your documentation and determines whether you meet FHA and lender requirements.
You may be asked for:
- Pay stubs
- W-2s or tax documents
- Bank statements
- Employment information
- Current mortgage statements
- Homeowners insurance information
- Identification and other financial documents
5. Close and receive the proceeds
At closing, the new mortgage pays off the existing mortgage and eligible transaction costs. The remaining amount is generally delivered to you as cash.
FHA Cash-Out Refinance Requirements in 2026
One of the biggest differences between an FHA cash-out refinance and a conventional cash-out refinance is the FHA program’s specific eligibility framework.
You must occupy the property
FHA cash-out refinancing is generally limited to an owner occupied principal residence.
HUD’s current handbook says the property must have been owned and occupied by at least one borrower as the borrower’s principal residence for the 12 months before FHA case number assignment. There is a specific inheritance exception, subject to FHA conditions.
That means an investment property or second home generally does not qualify for an FHA cash-out refinance.
You need an acceptable mortgage payment history
FHA requires documentation that the borrower made mortgage payments within the month due during the previous 12 months, or since obtaining the mortgage if the mortgage is newer.
The mortgage secured by the subject property must also be current for the month immediately before disbursement.
This requirement is particularly important for homeowners who recently experienced payment problems.
Your loan to value is limited to 80%
The maximum FHA cash-out refinance LTV and CLTV are generally 80%.
HUD reduced the maximum from 85% to 80% beginning with FHA case numbers assigned on or after September 1, 2019. The policy remains reflected in FHA guidance.
So if your home is worth $400,000, the maximum mortgage based on an 80% LTV calculation is $320,000 before considering the other limits and adjustments that may apply.
Credit score matters
FHA itself is known for more flexible credit requirements than many conventional programs. However, there is an important distinction between FHA eligibility and a lender’s actual approval standards.
A lender may require a higher score for a cash-out refinance than the FHA’s baseline underwriting framework. Your credit score can also affect your rate, approval conditions and overall affordability.
Do not treat a single advertised minimum credit score as a guarantee of approval.
The property must meet FHA requirements
The home must satisfy applicable FHA property and appraisal standards. Your lender and appraiser will determine whether the property is acceptable under current FHA rules.
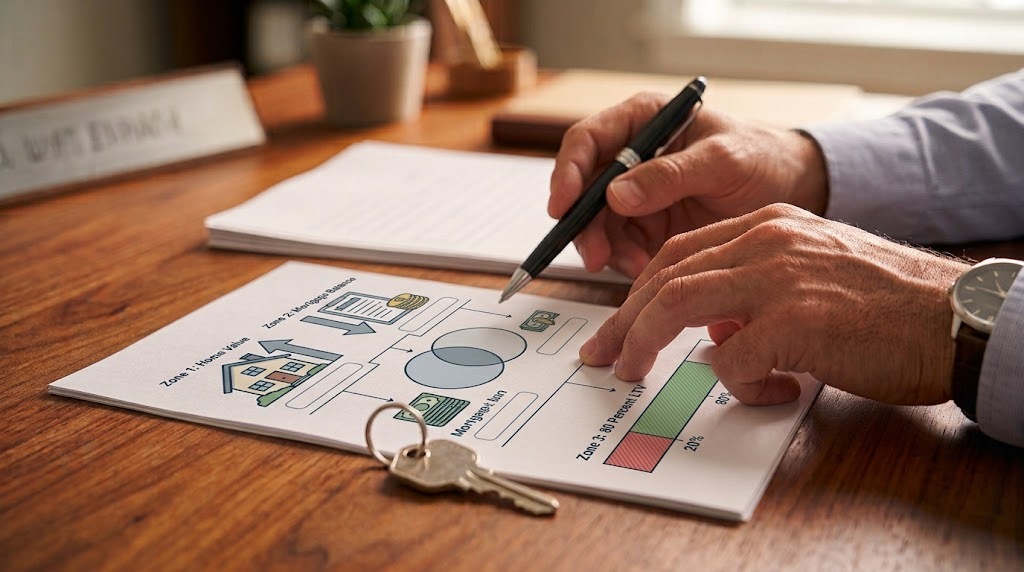
How Much Cash Can You Get From an FHA Cash-Out Refinance?
The amount of cash available depends mainly on four numbers:
- Your home’s adjusted value
- Your existing mortgage payoff
- The maximum FHA loan amount
- Eligible closing costs and other transaction adjustments
Example: $450,000 home
Imagine your home appraises for $450,000 and you owe $250,000.
At an 80% LTV:
$450,000 × 80% = $360,000
That creates a theoretical difference of:
$360,000 − $250,000 = $110,000
The $110,000 is not necessarily the amount you will receive. Closing costs, prepaid expenses and other applicable charges can reduce the cash proceeds.
There is also a separate FHA loan limit based on location and property type. For 2026, FHA’s nationwide one unit forward mortgage limit ranges from a $541,287 floor to a $1,249,125 ceiling, although the actual limit for a property depends on its location.
This creates an important planning point: 80% of your home’s value is not automatically the amount you can borrow. The FHA loan limit for your county and other underwriting factors can further restrict the transaction.
How Much Does an FHA Cash-Out Refinance Cost?
An FHA cash-out refinance can involve several expenses, so comparing only the interest rate can produce the wrong conclusion.
Upfront mortgage insurance
Most FHA forward mortgage transactions require an upfront mortgage insurance premium.
HUD currently lists the standard upfront MIP at 1.75% of the base loan amount.
For example, a $300,000 base loan would produce a $5,250 upfront MIP before considering how the transaction is structured.
The upfront premium may generally be financed into the mortgage rather than paid entirely from your bank account, subject to FHA rules.
Annual mortgage insurance
FHA loans also have annual mortgage insurance premiums collected through monthly payments. The applicable amount depends on factors such as loan term, LTV and base loan amount.
This is one reason an FHA refinance can look attractive based on the interest rate but become less attractive after adding the full insurance cost.
Closing costs
You may also encounter:
- Appraisal fees
- Title services
- Recording charges
- Origination fees
- Credit report fees
- Prepaid taxes and insurance
- Discount points, if selected
The exact amount varies by lender, location, loan size and transaction details.
The right comparison is therefore total borrowing cost, not simply the advertised mortgage rate.
FHA Cash-Out Refinance Pros and Cons
Pros
1. Access home equity without selling
You can convert some of your home’s equity into cash while continuing to own and occupy the property.
2. More flexible credit profile
FHA financing can be accessible to borrowers who may have difficulty qualifying for some conventional refinance options.
3. You can use the money for many purposes
Cash proceeds may be used for purposes such as home improvements, debt consolidation, education expenses or other legitimate financial needs.
4. You may consolidate expensive debt
If the numbers work, using home equity to eliminate high interest revolving debt can reduce the interest rate on that portion of your debt.
However, converting unsecured debt into mortgage debt also puts your home behind the obligation, so this strategy requires discipline.
5. You can refinance a non FHA mortgage
You do not necessarily need an existing FHA loan to use the FHA cash-out program.
Cons
1. Your mortgage balance increases
You are borrowing against equity you have already built.
2. You may pay mortgage insurance
FHA mortgage insurance can materially affect the long term cost of the loan.
3. Closing costs reduce your cash
The amount shown by a simple equity calculation is not necessarily the amount deposited into your account.
4. You may reset your mortgage term
Moving from an older mortgage into a new 30 year loan can extend the repayment period. Even if the monthly payment appears manageable, total interest can increase.
5. Your home secures the new debt
This is the biggest risk. If the new payment becomes unaffordable, the consequences can include foreclosure.
The CFPB has specifically warned that using home equity to pay non mortgage debts can increase foreclosure risk because unsecured obligations become debt secured by the home.
When Does an FHA Cash-Out Refinance Make Sense?
An FHA cash-out refinance deserves serious consideration when the money has a clear financial purpose.
For example, using $40,000 to complete necessary home improvements that protect or improve the property’s value may be more defensible than using the same $40,000 for recurring lifestyle expenses.
A useful test is:
Will the financial benefit of the cash last longer than the debt used to obtain it?
If the answer is yes, investigate the numbers.
If the cash will simply cover a recurring budget shortfall, refinancing may delay the underlying problem while increasing the debt secured by your home.
An original planning example
Consider a homeowner who owes $210,000 and has a $350,000 home.
At an 80% LTV, the maximum value based on the property calculation is $280,000. That gives approximately $70,000 before costs.
Instead of automatically taking the full amount, the homeowner could compare three scenarios:
- Take $70,000 and accept the highest new payment.
- Take $40,000 for a specific renovation and preserve more equity.
- Take no cash and use a rate and term refinance if the primary goal is reducing the mortgage cost.
The third option may produce less immediate cash but could be financially stronger. The lesson is simple: maximum cash is not the same thing as maximum financial benefit.
FHA Cash-Out Refinance vs. HELOC vs. Home Equity Loan
An FHA cash-out refinance is not automatically the best way to access equity.
| Option | How it works | Main advantage | Main concern |
|---|---|---|---|
| FHA cash-out refinance | Replaces your first mortgage | Access cash through one new mortgage | New rate, costs and FHA mortgage insurance |
| HELOC | Adds a revolving second lien | Borrow only what you need | Usually variable rate |
| Home equity loan | Adds a second mortgage with a lump sum | Predictable payment | Second monthly payment |
| Conventional cash-out refinance | Replaces your first mortgage | May offer better terms for stronger borrowers | Qualification can be stricter |
A HELOC or home equity loan may make more sense if you already have a very low mortgage rate that you do not want to replace.
The CFPB notes that home equity loans and HELOCs can allow homeowners to tap equity while keeping the existing first mortgage intact.
FHA Cash-Out Refinance vs. FHA Streamline Refinance
These two FHA refinance options serve different purposes.
An FHA cash-out refinance is designed to access equity and provide cash.
An FHA Streamline Refinance is designed to refinance an existing FHA mortgage with reduced documentation and does not function as a cash-out product.
If you already have an FHA loan and your primary goal is to improve the mortgage terms rather than withdraw equity, an FHA Streamline Refinance may be worth investigating.
How to Get the Best FHA Cash-Out Refinance Terms
Before applying, take these steps:
- Check your current mortgage rate. Do not replace a favorable rate without calculating the long term cost.
- Estimate your home’s value conservatively. A high online estimate is not the same as an appraisal.
- Calculate your 80% LTV ceiling.
- Check the FHA loan limit for your county.
- Review your credit reports for errors.
- Calculate your debt to income ratio.
- Get more than one lender quote.
- Compare APR and total costs, not just the interest rate.
- Decide exactly how much cash you need.
- Compare a HELOC and home equity loan before signing.
Is an FHA Cash-Out Refinance Worth It in 2026?
An FHA cash-out refinance can be useful, but it should not be treated as free access to your home’s equity.
The strongest candidates are homeowners who have sufficient equity, stable income, acceptable payment history, a clear reason for borrowing and a realistic plan for handling the new monthly payment.
The weaker candidates are homeowners who need cash simply to cover ongoing expenses or who would have to replace a highly favorable existing mortgage with a substantially more expensive loan.
Before making the decision, compare:
- New interest rate
- New loan balance
- Monthly principal and interest
- FHA mortgage insurance
- Closing costs
- Cash received
- Remaining loan term
- Total interest
- Alternative financing options
The CFPB’s research also shows why debt consolidation deserves careful analysis. Cash-out borrowers often use extracted equity to pay down other debt, but converting that debt into mortgage debt changes the risk because the home becomes collateral.
Final Takeaway
An FHA Cash-Out Refinance can turn home equity into usable cash while replacing your existing mortgage with a new FHA-insured loan. Its relatively flexible FHA framework can make it attractive for some homeowners, but the 80% LTV ceiling, mortgage insurance, closing costs and increased mortgage balance all matter.
The best decision is not necessarily the loan that gives you the most cash. It is the loan that solves your financial goal at a cost you can comfortably manage.
Before applying, calculate the new payment, compare the total cost with a HELOC or home equity loan, confirm your county’s 2026 FHA loan limit and ask the lender for a complete Loan Estimate.
FAQ Section
What is an FHA Cash-Out Refinance?
An FHA cash-out refinance replaces your existing mortgage with a new FHA-insured mortgage that can be larger than your current loan balance. The difference, after eligible payoffs and costs, is provided as cash.
How much can you cash out with an FHA refinance?
FHA cash-out refinances are generally limited to 80% of the property’s adjusted value. Your actual proceeds also depend on your mortgage payoff, closing costs, FHA loan limits and underwriting.
Do I need an FHA loan to get an FHA cash-out refinance?
No. An FHA cash-out refinance can be used to refinance an eligible existing mortgage even when the current loan is not FHA insured.
Can I use FHA cash-out refinance funds for anything?
Generally, cash proceeds can be used for many legitimate personal financial purposes, including home improvements and debt consolidation. However, borrowers should consider whether the use of the money creates enough long term financial benefit to justify increasing mortgage debt.
What credit score do I need for an FHA cash-out refinance?
There is no single lender approval score that applies to every borrower. FHA underwriting and individual lender requirements can differ. A lender may impose a higher minimum credit score or additional requirements, so borrowers should compare lenders rather than relying on one advertised minimum.
Is an FHA cash-out refinance better than a HELOC?
Not necessarily. An FHA cash-out refinance replaces your first mortgage, while a HELOC generally leaves your existing first mortgage in place. If you have a very low current mortgage rate, a HELOC or home equity loan may be worth comparing before refinancing the entire balance.







One Response