
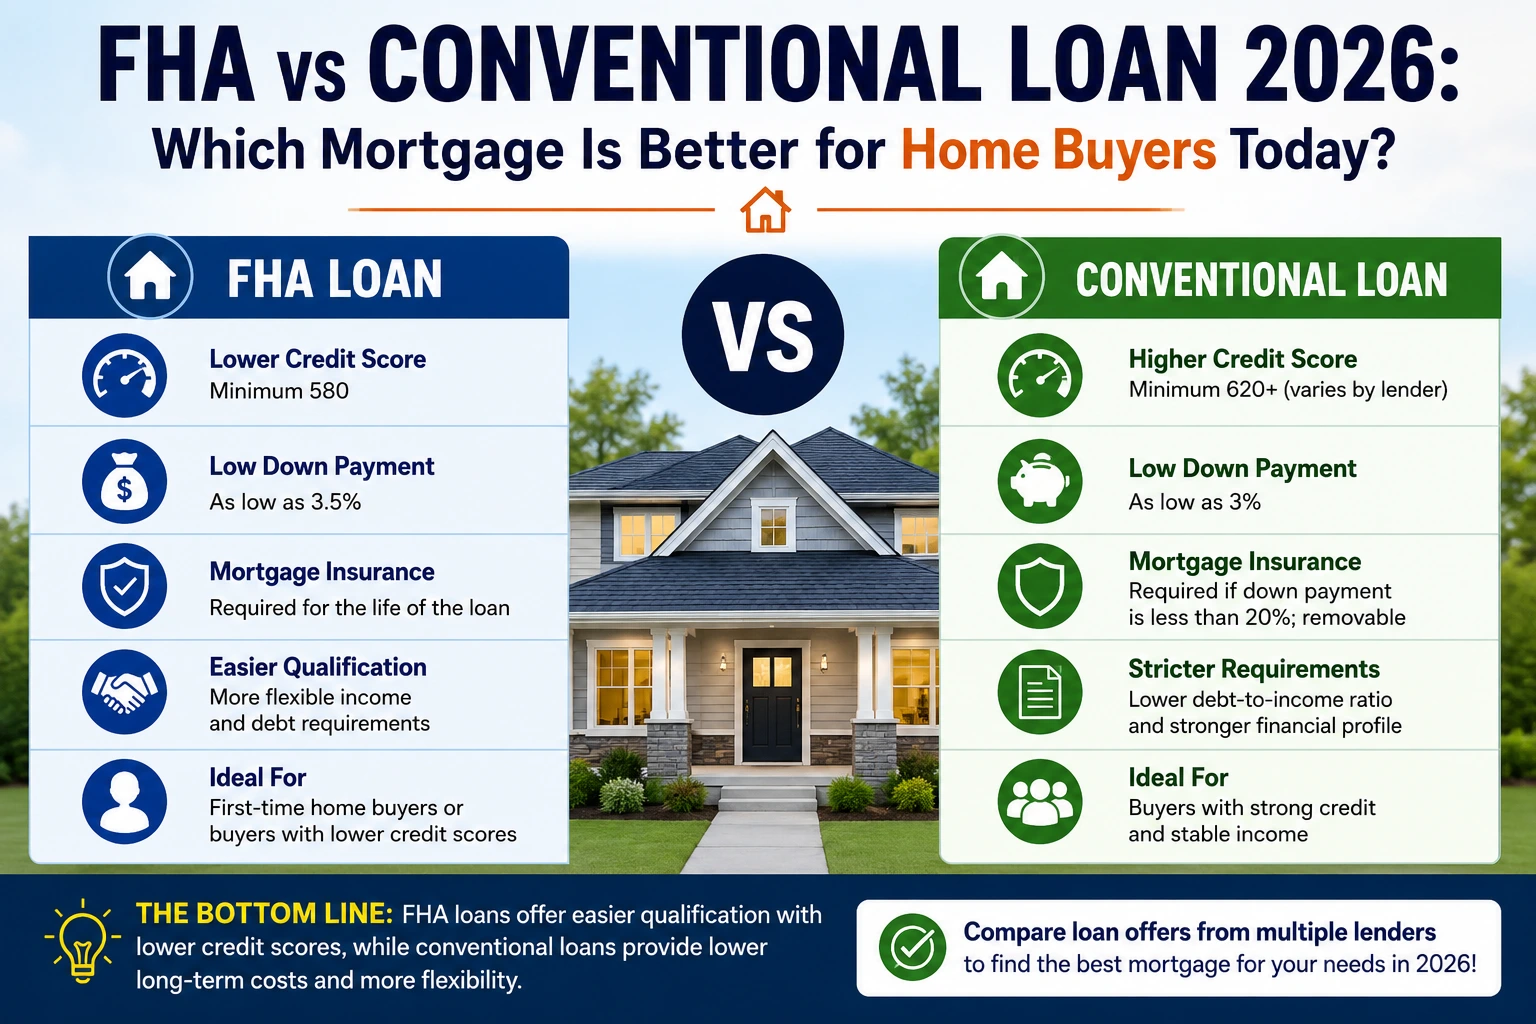

Compare FHA vs Conventional Loan 2026 requirements, down payment options, credit score rules, and costs to find the best mortgage for your needs.
FHA vs Conventional Loan 2026: Complete Guide for Home Buyers
Buying a home is one of the biggest financial decisions most people will make. If you are planning to purchase a home in 2026, choosing the right mortgage can save you thousands of dollars over the life of your loan. Two of the most popular mortgage options available today are FHA loans and conventional loans.
Many home buyers ask the same question: Which is better, an FHA loan or a conventional loan? The answer depends on your credit score, income, savings, and long term financial goals.
This guide will explain the key differences between FHA and conventional loans, including credit requirements, down payments, mortgage insurance, interest rates, and eligibility standards. By the end, you will have a better understanding of which mortgage option may be right for you.
What Is an FHA Loan?
An FHA loan is a Best Mortgage Loan insured by the Federal Housing Administration. This government backed program was created to help more people become homeowners by making mortgage qualification easier.
FHA loans are especially popular among first time home buyers because they allow lower credit scores and smaller down payments than many traditional mortgage programs.
Benefits of FHA Loans
- Lower credit score requirements
- Down payment as low as 3.5 percent
- Flexible debt to income guidelines
- Easier approval process
- Available to many first time and repeat buyers
Because the government insures the loan, lenders are often willing to approve borrowers who may not qualify for other types of financing.
What Is a Conventional Loan?
A conventional loan is a mortgage that is not backed by a government agency. These loans are offered through banks, mortgage lenders, and credit unions.
Conventional loans often have stricter qualification requirements, but they can offer lower overall borrowing costs for qualified buyers.
Benefits of Conventional Loans
- Competitive interest rates
- Lower mortgage insurance costs in many cases
- Greater flexibility for property types
- Potential for lower monthly payments
- Ability to remove Mortgage Guider Hub insurance later
Conventional loans are often a strong choice for borrowers with good credit and stable income.
FHA vs Conventional Loan 2026: Key Differences
Understanding the differences between these mortgage options can help you make an informed decision.
Credit Score Requirements
One of the biggest differences between FHA and conventional loans is the credit score requirement.
FHA Loan Credit Scores
FHA loans are designed to help borrowers with less than perfect credit.
Most lenders allow:
- 580 or higher for a 3.5 percent down payment
- Lower scores may qualify with a larger down payment
Conventional Loan Credit Scores
Conventional loans generally require stronger credit.
Most lenders prefer:
- Minimum score of 620
- Higher scores for better rates and loan terms
If your credit score is below average, an FHA loan may be easier to obtain.
Down Payment Requirements
Saving for a down payment can be challenging for many buyers.
FHA Loan Down Payment
The minimum FHA down payment is typically 3.5 percent of the home’s purchase price.
For a $300,000 home, that equals $10,500.
Conventional Loan Down Payment
Many conventional loan programs allow down payments as low as 3 percent.
For the same $300,000 home, the minimum down payment could be $9,000.
While both programs offer low down payment options, conventional loans may provide more flexibility for qualified borrowers.
Mortgage Insurance Requirements
Mortgage insurance protects lenders if a borrower stops making payments.
This area often creates the biggest difference in long term loan costs.
FHA Mortgage Insurance
FHA borrowers must pay mortgage insurance premiums.
These costs include:
- An upfront mortgage insurance premium
- An annual mortgage insurance premium included in monthly payments
In many cases, FHA mortgage insurance remains for a long period of time.
Conventional Mortgage Insurance
Conventional loans require private mortgage insurance when the down payment is less than 20 percent.
The major advantage is that private mortgage insurance can usually be removed once enough equity has been built in the property.
For many borrowers, this can lead to significant savings.
Debt to Income Ratio
Debt to income ratio measures how much of your monthly income goes toward debt payments.
FHA Loan Guidelines
FHA loans often allow higher debt ratios, making qualification easier for some borrowers.
Conventional Loan Guidelines
Conventional loans usually require lower debt ratios and stronger financial profiles.
Borrowers carrying student loans, auto loans, or credit card debt may find FHA financing easier to qualify for.
Interest Rates
Interest rates vary based on market conditions and borrower qualifications.
FHA loans sometimes offer attractive rates because they are government insured.
However, when mortgage insurance costs are included, conventional loans may be less expensive overall for borrowers with strong credit.
Comparing loan estimates from multiple lenders is the best way to determine which option offers the lowest total cost.
Advantages of FHA Loans in 2026
Easier Qualification
Borrowers with lower credit scores often have an easier time qualifying for FHA financing.
Lower Credit Standards
FHA programs are designed to expand access to homeownership.
Flexible Financial Requirements
Buyers with limited savings or higher debt levels may benefit from FHA guidelines.
Popular Among First Time Buyers
Many first time home buyers choose FHA loans because of their accessibility and lower entry requirements.
Advantages of Conventional Loans in 2026
Lower Long Term Costs
Qualified borrowers often pay less over the life of the loan.
Cancelable Mortgage Insurance
Private mortgage insurance can usually be removed once sufficient equity is reached.
More Property Flexibility
Conventional financing can be used for a broader range of property types.
Strong Option for Good Credit Borrowers
Home buyers with excellent credit may secure very competitive mortgage terms.
Who Should Choose an FHA Loan?
An FHA loan may be the right choice if:
- Your credit score needs improvement
- You have limited savings
- You are a first time home buyer
- You have higher debt levels
- You need flexible qualification requirements
FHA financing can help many buyers achieve homeownership sooner than they expected.
Who Should Choose a Conventional Loan?
A conventional loan may be a better fit if:
- You have strong credit
- You can afford a larger down payment
- You want lower long term costs
- You plan to stay in the home for many years
- You want mortgage insurance removed later
For financially strong borrowers, conventional financing often provides the best value.
FHA vs Conventional Loan 2026: Which Loan Is Better?
There is no one size fits all answer.
FHA loans are often ideal for buyers who need flexible approval standards and lower credit score requirements.
Conventional loans are frequently the better choice for borrowers with good credit, stable income, and sufficient savings.
The best mortgage depends on your unique financial situation. Before choosing a loan, compare rates, fees, closing costs, and monthly payments from multiple lenders.
A small difference in interest rates can save thousands of dollars over time.
Frequently Asked Questions
Is an FHA loan easier to qualify for than a conventional loan?
Yes. FHA loans generally have more flexible credit and income requirements.
What credit score is needed for an FHA loan in 2026?
Most borrowers need a credit score of at least 580 to qualify for the minimum down payment option.
Can I refinance an FHA loan into a conventional loan?
Yes. Many homeowners refinance once they build equity or improve their credit score.
Which loan has lower monthly payments?
The answer depends on interest rates, mortgage insurance costs, loan amount, and borrower qualifications.
Do FHA loans always require mortgage insurance?
Yes. FHA loans include mortgage insurance requirements.
Can conventional mortgage insurance be removed?
Yes. Private mortgage insurance can typically be canceled after reaching required equity levels.
Are FHA loans only for first time buyers?
No. Both first time and repeat buyers may qualify for FHA financing.
Which mortgage is best for first time home buyers?
Both can be excellent options. FHA loans are often easier to qualify for, while conventional loans may cost less over time.
Conclusion
The FHA vs Conventional Loan 2026 comparison comes down to your financial profile and homeownership goals. FHA loans offer easier qualification standards, lower credit score requirements, and flexible approval guidelines. Conventional loans provide lower long term costs, more property flexibility, and the ability to remove mortgage insurance.
Before making a final decision, review your budget, credit score, debt obligations, and down payment savings. Compare offers from several lenders and carefully evaluate all loan costs.







5 Responses