

Interest rates today can mean very different things depending on whether you are checking mortgage rates, Treasury yields, credit-card rates, savings rates, or the Federal Reserve’s policy rate. For homebuyers, the most important distinction is that the federal funds rate does not directly equal the mortgage rate you receive from a lender.
As of September 24, 2026, the national 30-year fixed mortgage benchmark reported by Freddie Mac was 7.03%, while Mortgage News Daily’s daily index showed 7.45%. Those numbers are different because they use different methodologies and update schedules.
So, what should you actually pay attention to? Look at the loan type, APR, points, credit profile, down payment, loan-to-value ratio, and lender fees—not just the headline rate.
What Are Interest Rates Today?
Interest rates today are the current borrowing or investment rates available across different parts of the financial market.
For mortgage shoppers, Mortgage interest rates today represent the cost of borrowing money to purchase or refinance a home. Your actual rate can be different from a published national average because mortgage pricing is risk-based.
In simple terms:
The mortgage rate you qualify for depends on both market conditions and your individual financial profile.
A lender may consider your:
- Credit score and credit history
- Debt-to-income ratio
- Down payment
- Loan-to-value ratio
- Loan amount
- Property type
- Occupancy
- Loan program
- Loan term
- Points and lender credits
- Refinance versus purchase purpose
For example, Wells Fargo explains that credit profile, property type, LTV, DTI, loan type, discount points, and other risk factors can influence mortgage pricing.
Mortgage Interest Rates Today: What Are the Current Benchmarks?
There is no single “official” mortgage rate for every borrower.
Different organizations measure rates differently, which is why you may see several numbers on the same day.
As of September 24, 2026, the major published benchmarks included:
| Rate source | 30-year fixed | 15-year fixed | Frequency |
|---|---|---|---|
| Mortgage News Daily | 7.45% | 7.10% | Daily |
| Freddie Mac PMMS | 7.03% | 6.42% | Weekly |
| MBA survey | 7.12% | 6.43% | Weekly |
Mortgage News Daily’s index also reported 7.05% for 30-year FHA and 7.07% for 30-year VA loans on September 24.
Freddie Mac’s Primary Mortgage Market Survey reported a 30-year fixed average of 7.03% and a 15-year average of 6.42% for the same date.
Why Do Published Rates Differ?
The difference is primarily methodological.
Mortgage News Daily updates its index on weekdays and is designed to capture day-to-day mortgage market movement. Its page also tracks mortgage-backed securities and Treasury markets.
Freddie Mac’s PMMS is a weekly survey based on mortgage rates collected from thousands of loan applications submitted through Loan Product Advisor.
That means a weekly survey should not automatically be interpreted as the exact rate a lender will quote you this afternoon.
Practical takeaway: use daily sources to understand today’s market direction and weekly surveys to understand the broader trend.
Why Are Interest Rates Today Changing?
Mortgage rates move because investors constantly reprice bonds and mortgage-backed securities based on economic expectations.
Several factors matter.
Inflation
Persistent inflation can push investors to expect tighter monetary policy or higher yields. Higher market yields can put upward pressure on mortgage rates.
Economic Growth
Stronger economic data can sometimes push longer-term yields higher because investors anticipate continued growth, inflation, or higher interest rates.
Employment
Jobs data can influence expectations for monetary policy and economic growth. A surprisingly strong or weak labor market report can cause rates to move quickly.
Treasury Yields
The 10-year Treasury yield is one of the most useful market indicators to watch when thinking about long-term mortgage rates.
The Federal Reserve’s H.15 data showed the 10-year Treasury constant maturity yield at 4.94% on September 24, 2026.
Mortgage rates do not simply equal the 10-year Treasury yield. Instead, mortgage pricing reflects Treasury-market conditions plus mortgage-backed-security pricing, lender costs, borrower risk, servicing economics, and other factors.
Mortgage-Backed Securities
Mortgage lenders frequently sell or securitize mortgages through the mortgage-backed-securities market.
When MBS prices move, mortgage pricing can respond. Mortgage News Daily specifically tracks MBS prices alongside mortgage rates and notes that MBS movement can influence the day’s mortgage-rate direction.
Does the Federal Funds Rate Determine Mortgage Rates?
Not directly.
This is one of the most important things to understand when researching interest rates today.
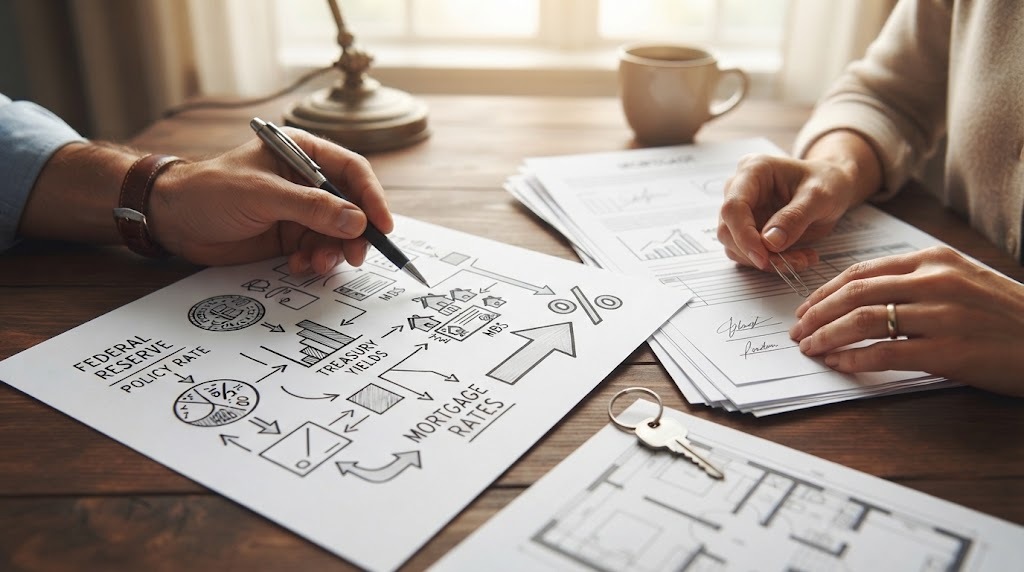
The federal funds rate is a short-term interest rate associated with overnight lending between depository institutions. The New York Fed publishes the effective federal funds rate based on transaction-level market data.
Mortgage rates are longer-term consumer loan rates and are influenced more directly by bond and mortgage-backed-security markets.
This creates an important distinction:
Fed funds rate: primarily a short-term monetary-policy benchmark.
Mortgage rate: a long-term borrowing rate influenced by market yields, MBS pricing, lender economics, and borrower risk.
The two are related because monetary policy affects economic expectations and financial markets, but a Federal Reserve rate change does not guarantee an equal mortgage-rate change.
What Determines the Mortgage Rate You Actually Get?
Two borrowers can apply for similar mortgages on the same day and receive different pricing.
Here are the biggest variables to examine.
Credit Score
A stronger credit profile can help you qualify for better pricing, although the exact effect depends on the loan program and other characteristics.
Before applying, review your credit reports for errors and avoid taking on unnecessary new debt.
Down Payment and LTV
LTV measures your loan amount compared with the property’s value.
For example, a $400,000 home with a $320,000 mortgage has an 80% LTV.
A lower LTV can reduce lender risk and may improve pricing in certain situations.
Debt-to-Income Ratio
DTI compares your monthly debt obligations with qualifying income.
A higher DTI can make a borrower appear riskier and may affect loan approval, pricing, or available loan options.
Loan Type
The rate for a conventional mortgage may differ from an FHA, VA, jumbo, or adjustable-rate mortgage.
Published Mortgage News Daily data illustrates this clearly: its September 24 daily index showed different rates for conventional, FHA, VA, jumbo, and 7/6 SOFR ARM loans.
Loan Term
A 15-year mortgage generally has a higher monthly principal-and-interest payment but can have a lower interest rate and significantly less total interest over the life of the loan.
A 30-year mortgage usually provides a lower monthly payment but extends repayment over a much longer period.
Property and Occupancy
A primary residence, second home, investment property, condominium, and multifamily property may receive different pricing because lenders evaluate their risk differently.
Interest Rate vs. APR: Which One Should You Compare?
When comparing interest rates today, don’t stop at the note rate.
Interest rate is the percentage charged on the principal borrowed.
APR, or annual percentage rate, attempts to express the yearly cost of the mortgage while incorporating certain finance charges and costs.
A loan advertising a lower interest rate can still be more expensive if it requires substantially higher upfront fees or discount points.
U.S. Bank explains that APR incorporates fees and costs beyond the stated interest rate, while its displayed monthly mortgage payments may exclude taxes and insurance.
A Simple Example
Imagine two lenders offer:
Lender A
- Rate: 6.75%
- Lower upfront fees
Lender B
- Rate: 6.50%
- Several thousand dollars in discount points
Lender B has the lower advertised rate, but that does not automatically make it the cheaper mortgage.
The right comparison is the Loan Estimate, including rate, APR, points, lender charges, closing costs, monthly payment, and cash required to close.
Should You Pay Discount Points for a Lower Rate?
Discount points are upfront costs paid to obtain a lower interest rate.
One point generally equals about 1% of the loan amount. For example, one point on a $300,000 mortgage would cost approximately $3,000. U.S. Bank provides the same basic explanation of points and their relationship to rate and payment.
The key question is break-even time.
Suppose paying points costs $3,000 and reduces your payment by $75 per month.
$3,000 ÷ $75 = 40 months
You would need to keep the mortgage for roughly 40 months just to recover the upfront cost through monthly savings, ignoring tax considerations and other variables.
This is one of the most useful calculations a borrower can perform when evaluating interest rates today.
How Can You Get a Better Mortgage Rate Today?
You cannot control Treasury yields or MBS markets, but you can improve several parts of your mortgage profile.
1. Compare Multiple Lenders
Don’t assume your bank automatically has the best rate.
Get comparable Loan Estimates from multiple lenders and compare the same loan type, term, points, and assumptions.
Wells Fargo recommends comparing two or three loan estimates before settling on a mortgage.
2. Improve Your Credit Profile
If you have time before applying, review your credit reports, make payments on time, and avoid unnecessary new credit.
3. Increase Your Down Payment When Practical
A larger down payment can reduce your LTV and may improve pricing or reduce mortgage insurance requirements depending on the loan.
4. Compare Points and Lender Credits
A lender offering a lower rate may charge more upfront. Another lender may offer a slightly higher rate with lower closing costs.
Compare the entire transaction.
5. Consider Different Loan Terms
Run the numbers for both 15-year and 30-year options rather than choosing solely based on the headline rate.
6. Ask About Rate Locks
Mortgage rates can change between application and closing.
A rate lock can protect an agreed rate for a specified period, subject to the lender’s terms and conditions.
What Should Homebuyers Watch When Checking Interest Rates Today?
If you’re checking rates every morning, focus on these five items:
- 30-year fixed mortgage rate
- 15-year fixed mortgage rate
- APR and points
- 10-year Treasury yield and MBS direction
- Your actual lender quotes
The fifth item is the most important.
A national average is useful for market context, but your Loan Estimate tells you what the mortgage actually costs you.
An Original Example: Why a Small Rate Difference Matters
Consider a $350,000 mortgage.
At 7.00% for 30 years, principal and interest are roughly $2,329 per month.
At 6.50%, the payment is roughly $2,212 per month.
That’s about $117 per month before taxes, insurance, mortgage insurance, or other costs.
Over a year, the payment difference is approximately $1,404.
But if the 6.50% loan requires $7,000 more in points and fees, the lower rate is not automatically the better deal. The borrower needs to calculate the break-even period and consider how long they expect to keep the mortgage.
This is why comparing only the advertised rate can lead to a misleading conclusion.
Where Can You Check Reliable Interest Rates Today?
For mortgage shoppers, use several sources rather than relying on one number.
- Freddie Mac PMMS: useful for weekly national mortgage-rate trends.
- Mortgage News Daily: useful for daily mortgage-market movements and MBS context.
- Federal Reserve H.15: useful for Treasury yields and other selected interest rates.
- New York Fed: useful for the effective federal funds rate and related reference-rate information.
- Individual lenders: useful for seeing actual rate, APR, points, and loan-program pricing.
Are Interest Rates Today Good or Bad for Homebuyers?
There is no universal answer.
A rate that looks high compared with a few years ago could still make sense for a buyer who finds the right property, has strong finances, and plans to hold the home for many years.
Conversely, a seemingly attractive rate may not be a good deal if it comes with excessive points, fees, or an unsuitable loan structure.
Instead of asking only:
“What is the interest rate today?”
ask:
“What is my total cost to borrow, and how does this offer compare with other offers for the same loan?”
That question leads to a much better mortgage decision.
Frequently Asked Questions About Interest Rates Today
What are interest rates today?
Interest rates today vary by financial product and market. For mortgages, the rate depends on loan type, market conditions, borrower qualifications, loan term, property characteristics, points, and lender pricing.
What are mortgage interest rates today?
As of September 24, 2026, Freddie Mac reported a 30-year fixed mortgage average of 7.03% and a 15-year average of 6.42%. Mortgage News Daily’s daily index was higher at 7.45% for 30-year fixed mortgages, illustrating why rate source and methodology matter.
Does the Fed control mortgage rates?
The Federal Reserve influences financial conditions through monetary policy, but it does not directly set the mortgage rate that individual homebuyers receive. Mortgage rates are heavily influenced by longer-term bond and mortgage-backed-security markets.
Why is my mortgage rate different from the national average?
National averages represent specific survey methodologies and assumptions. Your actual rate can differ because of credit, LTV, DTI, loan type, property, occupancy, loan size, points, lender pricing, and other factors.
Is APR more important than the interest rate?
APR is useful because it incorporates certain finance charges into a broader annualized cost measure. However, borrowers should compare both APR and the actual costs, including points, lender fees, closing costs, and monthly payment.
Should I wait for rates to fall before buying a home?
Waiting solely for a lower rate is not automatically the best strategy. Rates can move unpredictably, while home prices, inventory, and your personal financial circumstances can change. Compare the cost of buying now with the realistic alternatives available to you.
Conclusion: How to Use Interest Rates Today Wisely
Interest rates today are more than one headline percentage.
For mortgage shoppers, the smartest approach is to understand the difference between daily and weekly benchmarks, follow major market indicators, compare APR and points, and obtain multiple Loan Estimates.
The most important number is ultimately the rate and total cost you can actually qualify for.
If you’re preparing to buy or refinance, start by comparing your available loan options and calculating the payment under several rate scenarios.







One Response