

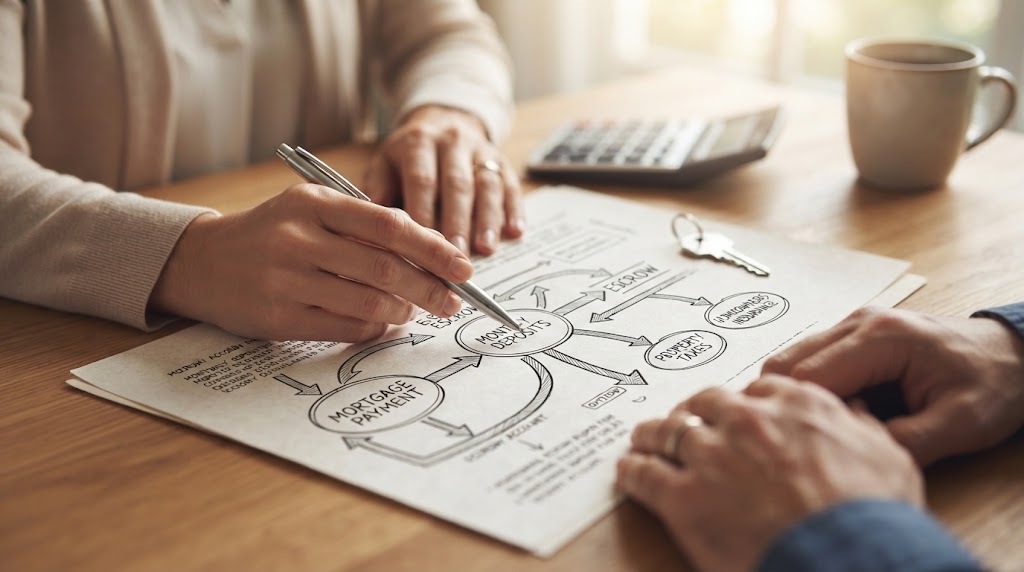
What is an escrow account? It is an account used to hold money for specific property-related expenses, most commonly property taxes and homeowners insurance. With a mortgage escrow account, you pay part of these costs each month with your mortgage payment, and your mortgage servicer uses the funds to pay the bills when they are due.
For many homeowners, escrow makes budgeting easier because a large annual or semiannual tax or insurance bill is divided into smaller monthly amounts. However, escrow can also be confusing when your mortgage payment suddenly increases, your account shows a shortage, or you receive an unexpected refund.
The key point is simple: escrow is not an extra mortgage charge. It is money collected in advance to pay certain homeownership expenses.
The Consumer Financial Protection Bureau (CFPB) explains that an escrow or impound account is generally established or controlled by a mortgage servicer to pay property taxes, insurance premiums, and other permitted charges.
What Is an Escrow Account and How Does It Work?
A mortgage escrow account acts like a dedicated holding account for certain expenses associated with your home.
Instead of receiving a $4,800 property tax bill and needing to find the entire amount at once, your servicer may collect approximately $400 per month toward that expense. The money accumulates in escrow until the tax payment is due.
A typical mortgage payment can therefore contain:
- Principal
- Interest
- Property taxes
- Homeowners insurance
- Mortgage insurance, when applicable
- Other permitted escrowed expenses
Your principal and interest pay for the mortgage itself. The escrow portion is set aside for bills associated with the property.
A Simple Mortgage Escrow Example
Suppose your estimated annual property taxes are $4,800 and your homeowners insurance costs $1,200 per year.
Your estimated annual escrow expenses would be:
$4,800 + $1,200 = $6,000
Dividing that by 12 months gives:
$6,000 ÷ 12 = $500 per month
So, approximately $500 of your monthly mortgage payment could go toward escrow, before considering any required initial deposit or permitted cushion.
This is an important distinction: the $500 is not interest charged by the lender. It is money being collected to cover future property expenses.
Your actual escrow payment can be different because the servicer must account for payment dates, projected changes, the account balance, and applicable escrow rules.
How Does a Mortgage Escrow Account Work?
The process generally follows a predictable cycle.
1. The Servicer Estimates Your Annual Expenses
Your mortgage servicer estimates how much will be needed for property taxes, homeowners insurance, and other eligible expenses.
The estimate is based on available information about your property and expected bills.
2. You Make Monthly Escrow Deposits
Each mortgage payment includes an escrow portion. The servicer deposits those funds into the escrow account.
Federal Regulation X generally allows a servicer to collect one-twelfth of the anticipated annual escrow disbursements as the monthly escrow amount, subject to applicable rules and limitations.
3. The Servicer Pays the Bills
When your property tax or insurance bill becomes due, the servicer uses the escrow funds to make the payment.
This is one of the biggest advantages of escrow: you do not have to remember every property-related due date yourself.
4. The Account Is Reviewed
Your servicer periodically analyzes the account to determine whether enough money is being collected.
Under federal rules, servicers generally conduct an escrow analysis over a 12-month computation year and provide an annual escrow statement.
If taxes or insurance have changed, your monthly payment may change as well.
What Does an Escrow Account Pay For?
The exact expenses depend on your mortgage and loan documents, but common escrow items include:
- Property taxes
- Homeowners insurance
- Flood insurance, when applicable
- Mortgage insurance or related required charges in certain loan programs
- Certain assessments or other permitted property charges
The CFPB defines federally regulated escrow accounts broadly enough to include taxes, insurance premiums, and other permitted charges connected with a federally related mortgage loan.
What Usually Is Not Paid From Escrow?
Not every homeownership expense belongs in escrow.
For example, homeowners association dues are typically handled separately unless your specific mortgage arrangement provides otherwise. U.S. Bank also notes that certain supplemental or unexpected property assessments may not automatically be paid from escrow.
Homeowners should therefore check their mortgage documents rather than assuming every property bill is covered.
Why Do Mortgage Lenders Use Escrow Accounts?
The biggest reason is payment reliability.
Property taxes and homeowners insurance are not optional expenses simply because they are separate from the mortgage principal and interest. If taxes remain unpaid, governments can impose penalties or place a tax lien on the property. If insurance lapses, the homeowner can also face serious financial risks.
The CFPB warns that failure to keep taxes and insurance current can have consequences that include liens and, in some circumstances, foreclosure-related risk.
Escrow reduces the chance that a homeowner will spend money intended for these bills elsewhere.
It also makes budgeting easier. Instead of preparing for one or two large bills each year, the homeowner makes smaller monthly contributions.
Wells Fargo similarly identifies predictable budgeting and keeping tax and insurance payments current as major advantages of mortgage escrow.
Can an Escrow Account Increase Your Mortgage Payment?
Yes.
This is one of the most important things homeowners need to understand.
Your mortgage payment can increase even when your interest rate and principal-and-interest payment have not changed.
For example, imagine your monthly payment initially looks like this:
| Payment component | Monthly amount |
|---|---|
| Principal and interest | $1,700 |
| Property tax escrow | $400 |
| Insurance escrow | $100 |
| Total payment | $2,200 |
If your property taxes later rise to $5,400 annually, the tax portion could increase from $400 to approximately $450 per month.
Your new estimated payment could therefore become approximately:
$1,700 + $450 + $100 = $2,250
That $50 increase does not necessarily mean your lender raised your mortgage interest rate.
It may simply mean your property expenses increased.
U.S. Bank and the CFPB both explain that changes in property taxes or insurance premiums can change the escrow portion and therefore the total monthly mortgage payment.
What Is an Escrow Shortage?
An escrow shortage occurs when the account does not have enough money to cover projected or required expenses.
This can happen when:
- Property taxes increase
- Homeowners insurance becomes more expensive
- A tax assessment changes
- An insurance policy is replaced at a higher premium
- The timing of a bill changes
- The original estimates were lower than the actual costs
For example, suppose your servicer expected your annual taxes to be $4,800 but the actual bill becomes $5,400. The additional $600 creates pressure on the escrow balance.
Your servicer may increase your future monthly escrow payment and may also require you to repay an existing shortage, depending on the circumstances and applicable rules.
A shortage does not necessarily mean your mortgage is wrong. Often, it simply means the underlying property expenses changed.
Should You Pay an Escrow Shortage Immediately?
That depends on the options provided by your servicer.
You may be allowed to pay the shortage in a lump sum or have it spread across future payments. Paying the shortage does not necessarily prevent future payment changes because the servicer may also need to account for higher taxes or insurance going forward.
What Is an Escrow Surplus or Refund?
The opposite of a shortage is a surplus.
A surplus can occur when the escrow account contains more money than needed under the applicable calculation.
Federal rules place limits on escrow balances and generally restrict the amount of cushion a servicer can require for covered federally related mortgage loans. The maximum cushion is generally one-sixth of estimated annual escrow disbursements, or about two months of payments, subject to applicable requirements.
If your annual escrow statement shows a surplus, the treatment can depend on the size of the surplus, the loan status, and applicable federal or state requirements.
The important lesson is to read the annual escrow statement rather than assuming every surplus automatically means a refund of the same amount.
Is an Escrow Account Required?
Not for every mortgage.
Whether escrow is required depends on factors such as:
- Loan type
- Lender requirements
- Down payment or loan-to-value considerations
- Federal or state requirements
- Property characteristics
- Insurance and tax considerations
Some loan programs have specific escrow requirements. For example, FHA servicing guidance requires escrowed funds for property-related charges such as real estate taxes, required hazard insurance, applicable flood insurance, and FHA mortgage insurance.
Some conventional borrowers may have more flexibility depending on the lender and loan structure.
If you do not have escrow, you become responsible for saving enough money to pay property taxes and insurance directly and on time.
Escrow Account vs. Escrow During a Home Purchase
There is an important terminology trap here.
The phrase escrow account can describe two different situations.
Mortgage Escrow After Closing
This is the account discussed throughout this guide. Your mortgage servicer collects money each month and uses it to pay taxes, insurance, and other permitted expenses.
Transaction Escrow Before Closing
During a home purchase, an escrow agent or company may temporarily hold earnest money, documents, and other funds while the conditions of the sale are completed.
NAR describes transaction escrow as a neutral arrangement designed to protect the parties while the purchase conditions are fulfilled. Earnest money can be deposited into escrow after the purchase agreement is signed and funds can be released when the transaction’s requirements are satisfied.
These are related concepts, but they are not the same account serving the same purpose.
This distinction is frequently overlooked in basic escrow explanations and is especially important for first-time buyers.
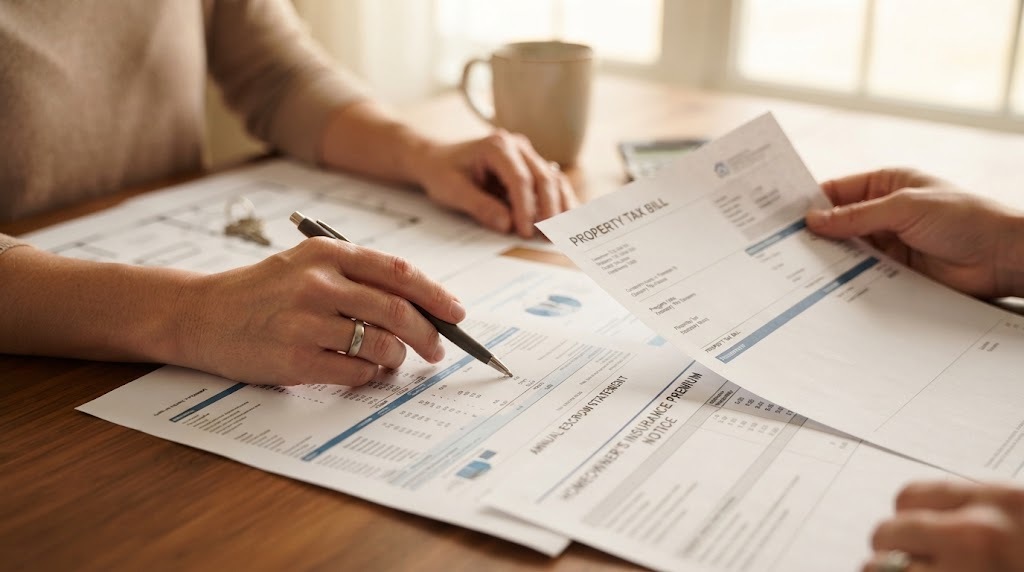
What Should You Check on Your Escrow Statement?
Do not ignore your annual escrow statement.
A quick review can help you catch errors before they become expensive problems.
Check these items:
- Current property tax estimate
- Current homeowners insurance premium
- Projected payment dates
- Beginning escrow balance
- Monthly escrow deposits
- Actual disbursements
- Projected ending balance
- Any shortage or surplus
- New monthly mortgage payment
Compare the tax and insurance figures against your actual bills or insurance declarations page.
If your insurance premium increased by $300 but the escrow analysis shows a dramatically larger change, ask your servicer to explain the calculation.
Federal rules require annual escrow statements for covered accounts, and the CFPB says the annual statement is provided within 30 days after completion of the escrow computation year.
Practical Escrow Tip for Homeowners
After years of reviewing mortgage payment structures, one useful habit is to separate the escrow problem from the mortgage problem.
If your payment rises, first compare the old and new:
Principal + interest + taxes + insurance + other escrowed items
If principal and interest are unchanged but taxes or insurance increased, you have an escrow adjustment rather than a mortgage-rate problem.
That simple comparison can prevent a common mistake: assuming that every payment increase means the loan itself became more expensive.
For example, a homeowner whose taxes increase by $600 per year should expect roughly $50 more per month in future escrow collection before considering any shortage repayment or other adjustments.
That is a much clearer way to understand the change than simply looking at the new total payment.
Frequently Asked Questions About Escrow
Does escrow cost extra money?
An escrow account generally does not represent an additional fee for the same money. It is a mechanism for collecting and holding funds needed for eligible property expenses. Separate escrow or transaction fees can exist in some real estate transactions, so always review your closing documents.
Does escrow earn interest?
Whether escrow funds earn interest for the borrower depends on applicable law and the specific loan and account arrangement. Federal rules do not universally require all mortgage escrow accounts to earn interest.
Can I cancel my mortgage escrow account?
Sometimes, but not always. Cancellation depends on your loan terms, lender requirements, loan type, applicable law, and other factors. Do not assume that reaching 20% equity automatically guarantees cancellation.
Why did my mortgage payment increase if my interest rate stayed the same?
The most common explanation is an increase in property taxes, homeowners insurance, an escrow shortage, or a combination of these factors. Review your escrow analysis to identify exactly what changed.
What happens if my escrow account does not have enough money?
Your servicer may identify a shortage and adjust future escrow payments. Depending on the situation, you may be offered a lump-sum repayment option or a repayment schedule. Your servicer’s escrow statement should explain the adjustment.
Conclusion: Understanding Escrow Makes Homeownership Easier
So, what is an escrow account? It is a system that helps homeowners set aside money for property taxes, homeowners insurance, and certain other eligible expenses through regular mortgage payments.
A mortgage escrow account can simplify budgeting, but it is important to understand why the payment can change. Taxes and insurance are not fixed forever, so your escrow contribution may rise or fall after an annual analysis.
The best approach is simple: review your escrow statement, compare projected figures with your actual tax and insurance bills, and ask your mortgage servicer about anything that does not make sense.
If you are preparing to buy a home, understanding escrow before closing can also help you estimate your true monthly housing cost rather than looking only at principal and interest.
For official consumer guidance, the Consumer Financial Protection Bureau provides detailed information about escrow accounts and federal mortgage-servicing requirements.
FAQ Section
What is an escrow account?
An escrow account is an account managed or controlled by a mortgage servicer to collect and hold money for expenses such as property taxes and homeowners insurance.
How does a mortgage escrow account work?
A portion of your monthly mortgage payment goes into escrow. When property taxes or insurance premiums are due, the mortgage servicer uses those funds to pay the bills on your behalf.
Why did my mortgage payment increase because of escrow?
Your payment may increase because property taxes or insurance premiums increased, because your escrow account experienced a shortage, or because the servicer’s new analysis projects higher future expenses.
Can an escrow account have a surplus?
Yes. If more money is collected than required under the applicable escrow calculation, the account can have a surplus. Federal rules limit escrow cushions for covered federally related mortgage loans.
Is a mortgage escrow account required?
Not for every mortgage. Requirements vary according to loan type, lender requirements, property characteristics, and applicable federal or state rules. Some loan programs have specific escrow requirements.
Is mortgage escrow the same as closing escrow?
No. Mortgage escrow generally holds funds for ongoing property expenses after closing. Closing or transaction escrow is a temporary arrangement used to hold funds and documents during a real estate transaction.







One Response