

If you’re wondering what is a home equity loan, the simple answer is this: it is a loan that lets you borrow against the equity you’ve built in your home. You generally receive the money as a lump sum and repay it through scheduled monthly payments.
For many homeowners, a home equity loan can provide access to a substantial amount of money without replacing the existing first mortgage. That can make it useful for a major renovation, large one-time expense, or carefully planned debt consolidation.
But there is an important trade-off: your home secures the loan. If you cannot repay the debt, you could put your home at risk.
This guide explains how home equity loans work, how much you may be able to borrow, the difference between a home equity loan and a home equity line of credit (HELOC), typical qualification factors, costs, tax considerations, advantages and disadvantages, and alternatives worth considering before you apply.
What Is a Home Equity Loan?
A home equity loan is a secured installment loan that allows a homeowner to borrow money using the equity in their property as collateral.
Home equity = current home value − outstanding mortgage balance.
For example, suppose your home is currently worth $400,000 and your remaining mortgage balance is $250,000:
- Home value: $400,000
- Mortgage balance: $250,000
- Estimated equity: $150,000
- Equity percentage: 37.5%
However, having $150,000 of equity does not automatically mean a lender will give you a $150,000 home equity loan. Lenders consider your income, credit profile, existing debt, property value, loan-to-value ratio, and their own underwriting requirements.
The Consumer Financial Protection Bureau explains that a home equity loan is generally received as a lump sum and may be considered a second mortgage when you already have a mortgage on the property.
How Does a Home Equity Loan Work?
A home equity loan usually follows a straightforward process.
1. You determine your available equity
The lender first evaluates your home’s current market value and your existing mortgage balance.
A professional appraisal or another valuation method may be used to establish the property’s value.
2. You apply for a specific loan amount
Unlike a HELOC, you normally request a defined amount upfront.
For example, you might apply for $50,000 to fund a kitchen renovation rather than opening a credit line that you can repeatedly draw from.
3. The lender evaluates your finances
The lender may review:
- Credit score and credit history
- Income and employment
- Debt-to-income ratio
- Existing mortgage balance
- Property value
- Loan-to-value ratio
- Payment history
- Available equity
There is no single nationwide credit score or equity requirement that guarantees approval. Requirements vary by lender and loan program.
4. You receive a lump sum
If approved, the loan proceeds are generally delivered as one lump sum.
5. You make monthly payments
You repay principal and interest according to the loan’s repayment schedule.
Many home equity loans have fixed rates, which makes the monthly payment easier to predict than a variable-rate product. However, terms, rates, fees, and structures vary by lender.
A practical example
Imagine a homeowner has:
- $400,000 property value
- $250,000 first mortgage balance
- $150,000 estimated equity
- $50,000 home equity loan
The homeowner keeps the original mortgage and adds the new home equity loan payment.
That means the homeowner now has two debts secured by the same property.
This is one of the most important points to understand before borrowing: a home equity loan does not make existing mortgage debt disappear. It adds another obligation.
How Much Can You Borrow With a Home Equity Loan?
The amount you can borrow depends on several factors rather than simply your total equity.
Lenders commonly evaluate the combined loan-to-value ratio, or CLTV.
A simplified calculation is:
CLTV = (existing mortgage balance + new home equity loan) ÷ home value × 100
Using the previous example:
$250,000 existing mortgage + $50,000 home equity loan = $300,000 total secured debt.
$300,000 ÷ $400,000 = 75% CLTV
Whether 75% is acceptable depends on the lender and the borrower’s overall financial profile.
Some lenders may allow borrowing up to a particular percentage of home value, but maximums vary. U.S. Bank, for example, states that its qualification process considers equity, credit, DTI, and income history and notes an LTV limit for its specific product.
Do not treat a lender’s maximum as your recommended borrowing amount. A loan that technically fits underwriting rules may still be too large for your monthly budget.
Home Equity Loan vs. HELOC: What’s the Difference?
A home equity line of credit (HELOC) also allows you to borrow against home equity, but it works differently.
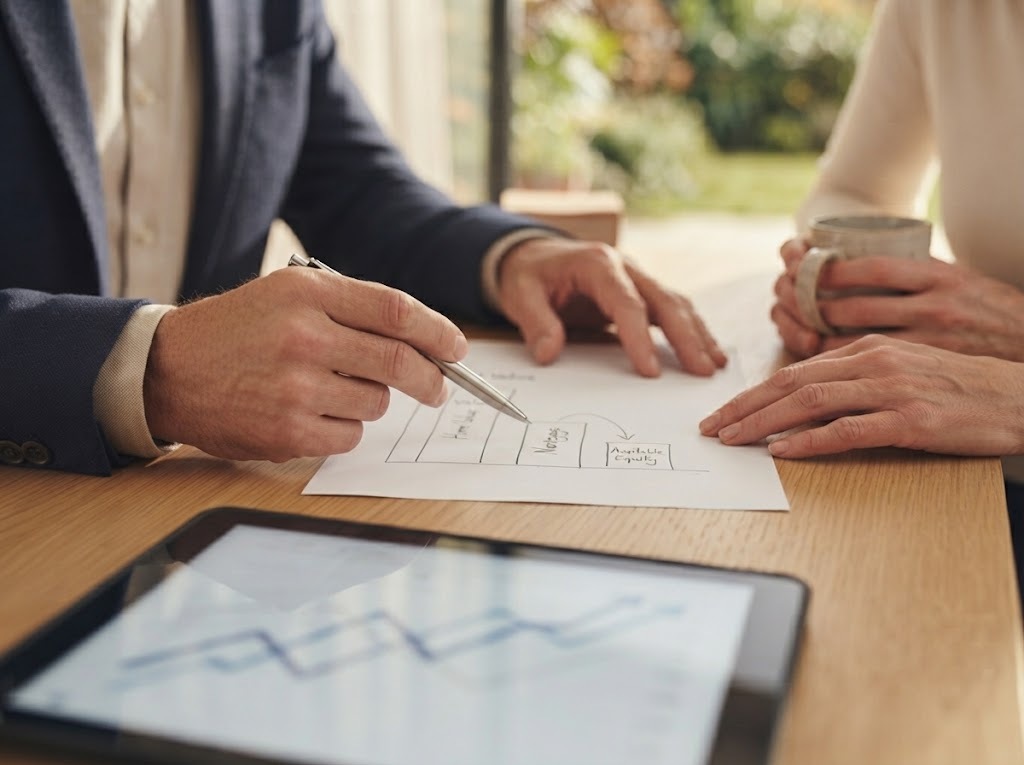
A home equity loan generally provides a lump sum. A HELOC provides a revolving credit line that you can draw from as needed during the draw period.
| Feature | Home Equity Loan | HELOC |
|---|---|---|
| Funding | Lump sum | Draw as needed |
| Credit structure | Installment loan | Revolving credit |
| Interest rate | Often fixed | Usually variable |
| Payments | Generally predictable | Can change |
| Best suited for | Known, one-time expense | Expenses occurring over time |
| Interest | Charged on loan balance | Generally charged on amount borrowed |
| Reusable credit | No | Yes, during draw period |
The CFPB describes a HELOC as an open-end line of credit that lets borrowers repeatedly access available home equity. HELOCs commonly have a draw period followed by a repayment period.
When might a home equity loan make more sense?
A home equity loan may be worth considering when:
- You know exactly how much money you need.
- You prefer predictable payments.
- You have a large one-time expense.
- You want to keep your existing first mortgage.
- You have a clear repayment plan.
When might a HELOC make more sense?
A HELOC may be more practical when:
- Your expenses will happen over several months or years.
- You don’t know the final cost of a project.
- You want to borrow only what you need.
- You want access to funds without taking the entire amount upfront.
Because HELOC rates are often variable, your payment can change as rates or your outstanding balance change.
What Can You Use a Home Equity Loan For?
A home equity loan can generally be used for many legitimate personal expenses, subject to the lender’s terms and applicable law.
Common uses include:
Home improvements
Renovations are one of the most common reasons homeowners consider tapping their equity.
Examples include:
- Kitchen remodeling
- Bathroom renovation
- Roof replacement
- Room additions
- Major repairs
- Energy-efficiency improvements
Using equity for improvements can be particularly important when the homeowner has a defined project budget.
Debt consolidation
Some homeowners use a home equity loan to consolidate higher-interest debt.
But this strategy requires caution.
Converting unsecured debt into debt secured by your home changes the risk. If you cannot make payments, your home could be at risk.
The CFPB specifically warns consumers to carefully evaluate alternatives before using home equity to pay off debts.
Education expenses
Some homeowners use home equity to help cover education-related expenses. However, compare the total cost and risks against federal or private student financing before making a decision.
Large planned expenses
Depending on lender rules, homeowners may use the funds for expenses such as major purchases or other significant financial needs.
The key question should not simply be “Can I use a home equity loan for this?”
A better question is:
“Does using my home as collateral make financial sense for this expense?”
What Are the Advantages of a Home Equity Loan?
Understanding the benefits helps explain why these loans remain popular.
Fixed and predictable payments
A fixed-rate home equity loan can make budgeting easier because your principal and interest payment generally follows a predictable schedule.
Access to a large amount of money
Homeowners with substantial equity may be able to access more funds than they could through some unsecured borrowing options.
Keep your existing first mortgage
A home equity loan can allow you to borrow without replacing your existing first mortgage.
This may matter if your current mortgage has favorable terms that you do not want to disturb.
Potentially lower borrowing cost than unsecured debt
Because the home secures the loan, the interest rate may be lower than some unsecured borrowing products.
That does not automatically make a home equity loan cheaper overall. Fees, repayment period, and total interest still matter.
Defined repayment schedule
Unlike revolving credit, an installment loan gives you a specific balance and repayment schedule from the beginning.
What Are the Disadvantages and Risks?
The risks deserve just as much attention as the benefits.
Your home is collateral
This is the biggest issue.
If you fail to repay the loan, the lender may have legal remedies that can ultimately put your home at risk.
You add another monthly payment
If you already have a mortgage, your home equity loan is generally an additional obligation.
Before borrowing, calculate:
Current housing payment + home equity payment + other debt payments = total monthly debt obligations
Make sure the new payment remains manageable even if your income changes.
Closing costs and fees may apply
Depending on the lender, costs can include appraisal, origination, recording, application, title, or other charges.
Some lenders advertise no closing costs, while others charge fees. Never assume every lender uses the same pricing structure.
Your home value can fall
Home equity is based partly on property value. If property values decline, your equity can shrink.
Debt consolidation can create a false sense of savings
A lower monthly payment does not necessarily mean a lower total cost.
For example, stretching repayment over 15 or 20 years could reduce the monthly payment while increasing the total interest paid.
What Are the Requirements for a Home Equity Loan?
There is no universal approval checklist, but lenders commonly examine several major areas.
Sufficient equity
You need enough equity to support the requested loan under the lender’s CLTV rules.
Credit history
A stronger credit profile can improve your chances of approval and may help you qualify for better pricing.
Some lenders publish specific minimum credit scores, but these are not universal requirements. U.S. Bank currently lists a 660 FICO score for its home equity loan product, while also considering other factors.
Income and employment
Lenders need evidence that you can afford the new debt.
Depending on your situation, documentation may include pay stubs, W-2s, tax returns, bank statements, or other income records.
Debt-to-income ratio
Your DTI helps lenders measure your existing monthly debt compared with your gross income.
A lower DTI generally makes your financial profile stronger, although each lender uses its own underwriting standards.
Property value
The lender needs enough information to determine the property’s value and calculate the applicable LTV or CLTV.
How Much Does a Home Equity Loan Cost?
The cost is more than the advertised interest rate.
When comparing offers, examine:
- Interest rate
- APR
- Loan amount
- Loan term
- Monthly payment
- Origination fees
- Appraisal costs
- Title or recording charges
- Prepayment restrictions
- Total interest over the life of the loan
Example: Why the monthly payment is not enough
Suppose you borrow $50,000 at a hypothetical 8% fixed interest rate for 10 years.
Your principal and interest payment would be approximately $607 per month, and the total principal and interest paid would be roughly $72,900 over the full term.
The exact cost will vary based on the actual rate, term, fees, and lender.
This illustrates an important point: compare total borrowing cost, not just the monthly payment.
Is Home Equity Loan Interest Tax Deductible?
Sometimes, but you should not assume it is.
Under current IRS guidance, interest on home equity debt is generally deductible only when the loan proceeds are used to buy, build, or substantially improve the home that secures the debt, subject to applicable tax rules and limitations.
For example, using a home equity loan to substantially improve the home securing the loan may qualify, while using the money for unrelated personal expenses generally does not create the same deduction.
Tax rules can change, and individual circumstances matter.
Speak with a qualified tax professional before making a borrowing decision based on a potential deduction.
Home Equity Loan vs. Cash-Out Refinance
A home equity loan and cash-out refinance both allow homeowners to access home equity, but they work differently.
Home equity loan
You generally keep your existing first mortgage and add a separate loan secured by the property.
Cash-out refinance
You replace your existing mortgage with a new, larger mortgage and receive the difference as cash.
For example:
- Existing mortgage: $250,000
- New cash-out refinance: $325,000
- Cash before applicable costs: approximately $75,000
A cash-out refinance may make sense when changing the first mortgage is financially attractive.
A home equity loan may make more sense when you want to preserve your existing mortgage terms.
The right choice depends heavily on your current mortgage rate, new loan rate, closing costs, desired cash amount, and how long you expect to keep the property.
Is a Home Equity Loan a Good Idea in 2026?
There is no universal yes or no.
A home equity loan may be reasonable when:
- You have substantial equity.
- Your income comfortably supports the new payment.
- You have a specific financial purpose.
- The expected benefit of the project justifies the borrowing cost.
- You understand the risk of using your home as collateral.
- You compare multiple lenders before choosing an offer.
It may be a poor choice when:
- You are already struggling with mortgage payments.
- You have little emergency savings.
- Your income is unstable.
- You are borrowing simply because your home has appreciated.
- You are using the loan to fund ongoing spending.
- The new payment would stretch your budget.
- You have not compared alternatives.
The CFPB recommends considering alternatives and understanding the risk of borrowing against your home, particularly when using equity to address existing debt problems.
How to Decide Between a Home Equity Loan, HELOC, and Cash-Out Refinance
Use your financial objective as the starting point.
Choose a home equity loan when:
You need a known lump sum and prefer predictable payments.
Consider a HELOC when:
You need flexible access to money over time and can manage potential rate changes.
Consider cash-out refinancing when:
You want to replace your existing mortgage and the new mortgage terms make financial sense.
Before choosing, compare:
- Interest rate
- APR
- Monthly payment
- Closing costs
- Total interest
- Repayment period
- Existing mortgage rate
- Tax considerations
- Early payoff rules
- Risk to your home
Smart Questions to Ask a Lender Before Applying
Before signing, ask:
- What is the interest rate and APR?
- Is the rate fixed or variable?
- What is the total amount I will repay?
- Are there closing costs?
- Are there annual or maintenance fees?
- Is there a prepayment penalty?
- What happens if I pay the loan off early?
- What is the maximum CLTV?
- What documents are required?
- How could the loan affect my existing mortgage?
- What happens if my home value falls?
- Are there alternatives that may cost less?
Getting answers in writing makes it easier to compare offers from different lenders.
A Simple Home Equity Loan Decision Test
Before applying, run this five-question test:
1. Do I have a specific purpose for the money?
If you cannot explain exactly why you need the loan, waiting may be better.
2. Can I comfortably make the payment?
Calculate the payment alongside your existing mortgage and other obligations.
3. Have I compared alternatives?
Look at a HELOC, cash-out refinance, personal loan, or other appropriate financing.
4. Have I calculated the total cost?
Do not focus only on the monthly payment.
5. Would I still be comfortable if my financial situation changed?
This is often the question borrowers overlook.
A loan should fit your budget under realistic conditions, not only under the best-case scenario.
Final Takeaway: What Is a Home Equity Loan?
So, what is a home equity loan?
It is a secured installment loan that allows homeowners to borrow against the equity in their property, usually receiving the money as a lump sum and repaying it through scheduled payments.
The main attraction is straightforward: you can access a potentially significant amount of money while keeping your existing first mortgage.
The main risk is equally straightforward: your home is collateral.
A home equity loan can be useful for a well-planned financial purpose, but it should not be treated as free cash. Compare the interest rate, APR, fees, repayment period, total interest, and alternatives before borrowing.
If you’re researching mortgage and home financing options in the United States, visit FHA Mortgage Brokers] for additional educational resources and mortgage guidance.
FAQ Section
What is a home equity loan?
A home equity loan is a secured installment loan that allows a homeowner to borrow against the equity in their home. The borrower typically receives a lump sum and repays it through scheduled monthly payments.
Is a home equity loan the same as a HELOC?
No. A home equity loan usually provides a lump sum, while a home equity line of credit (HELOC) provides a revolving credit line that can generally be accessed as needed during the draw period. HELOCs commonly have variable interest rates.
How much can I borrow with a home equity loan?
The amount depends on factors such as your home value, existing mortgage balance, credit history, income, debt-to-income ratio, and the lender’s maximum LTV or CLTV requirements. Having substantial equity does not guarantee approval for the entire amount.
Does a home equity loan have to be repaid if I sell my home?
Generally, the outstanding secured debts against the property must be addressed when the home is sold. Your lender or settlement agent can provide the exact payoff requirements for your loan.
Is home equity loan interest tax deductible?
It may be deductible when the borrowed funds are used to buy, build, or substantially improve the home securing the loan, subject to IRS rules and applicable limitations. Consult a qualified tax professional about your specific situation.
Is a home equity loan risky?
Yes. Because the home secures the debt, failure to repay can put the property at risk. Borrowers should evaluate their ability to make payments and compare alternatives before taking out the loan.







One Response