

FHA Loan Requirements 2026: Full Eligibility Checklist can help you determine whether you are ready to apply for an FHA mortgage. The FHA program can be attractive to buyers who have limited savings or less than perfect credit, but qualifying is not based on credit score alone.
In simple terms, most borrowers need a qualifying credit history, sufficient income, manageable debt, the required down payment, an eligible primary residence, and a property that meets FHA standards. Your lender will also review your complete financial profile before approving the mortgage.
The Federal Housing Administration does not lend the money directly. Instead, FHA insurance protects approved lenders against certain losses, allowing lenders to offer financing under FHA program rules.
This guide breaks down the requirements that matter in 2026, including the updated FHA loan limits, mortgage insurance, income documentation, property rules, and common issues that can delay approval.
FHA Loan Requirements 2026 at a Glance
Before getting into the details, here is the basic checklist:
- Credit score: 580 or higher generally allows 3.5% down; 500 to 579 generally requires 10% down.
- Down payment: As low as 3.5% with a qualifying credit score.
- Income: Must be properly documented and sufficient to support the proposed mortgage and other debts.
- Employment: Lenders generally review employment and income history for stability.
- Debt to income ratio: There is not one universal FHA DTI limit for every borrower. Automated and manual underwriting can produce different results.
- Primary residence: The home generally must be your principal residence.
- Property: The home must meet applicable FHA property requirements.
- Mortgage insurance: FHA loans generally require both upfront and annual mortgage insurance premiums.
- Loan limits: The maximum FHA insured loan varies by county and property size.
- Federal debt: Delinquent federal debt or certain unresolved obligations can create eligibility problems.
One important point often missed in simplified FHA guides is that FHA minimum standards are not the same thing as a lender’s approval standards. An FHA approved lender can apply additional requirements, commonly called overlays.
What Are the FHA Credit Score and Down Payment Requirements?
Credit score and down payment are closely connected under standard FHA financing.
Credit score of 580 or higher
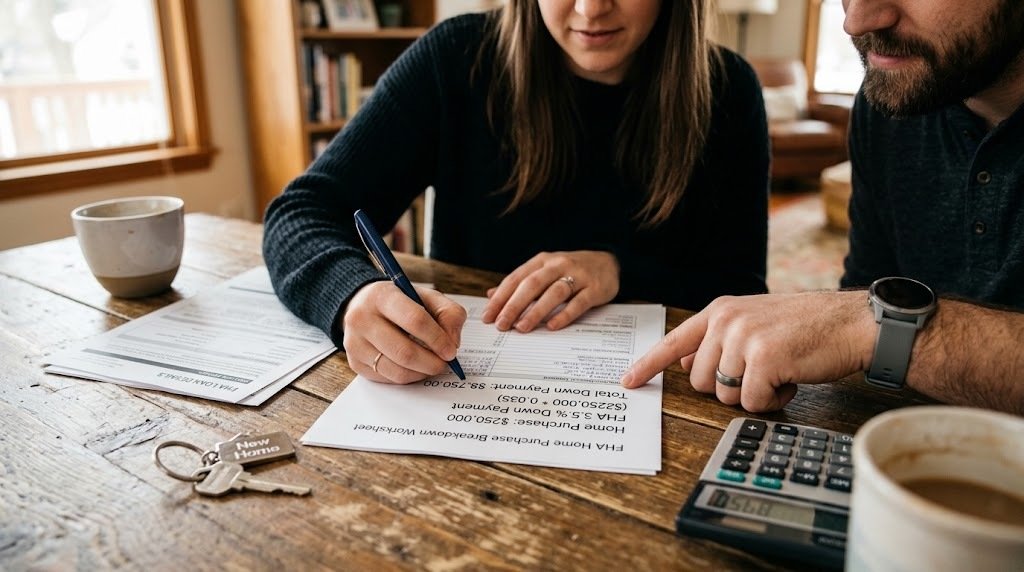
A borrower with a minimum decision credit score of 580 or higher can generally qualify for maximum FHA financing of 96.5% loan to value, meaning a 3.5% minimum down payment for a standard purchase transaction.
Credit score from 500 to 579
Borrowers with a qualifying score between 500 and 579 are generally limited to 90% loan to value. That means a 10% minimum down payment.
A score below 500 does not meet the standard FHA minimum credit score policy.
However, these are FHA program thresholds, not guarantees of approval. A lender may require a higher score or additional compensating factors.
Can gift money be used?
Yes. Eligible gift funds can generally be used toward the FHA minimum required investment when the donor and documentation meet FHA rules.
The lender will need documentation showing where the money came from and that it is a genuine gift rather than an undisclosed loan. Acceptable sources can include certain family members, employers, charitable organizations, and government or public entities.
For example, if you purchase a $250,000 home, a 3.5% down payment would be $8,750. If an eligible family member provides documented gift funds, those funds may potentially help cover the required investment.
That is a practical distinction worth remembering: the FHA minimum down payment is not necessarily the same as the amount of cash you should have available before buying. You may also need funds for closing costs, prepaid expenses, inspections, moving costs, reserves, and other expenses.
What Income, Employment and DTI Requirements Apply?
FHA underwriting looks beyond your credit score. The lender must determine whether your income is reliable and whether your debts can be supported by that income.
Employment and income documentation
Lenders commonly review employment and income history and may request documents such as:
- Recent pay stubs
- W 2 forms
- Tax returns when applicable
- Bank statements
- 1099 forms for qualifying self employed borrowers
- Employment verification
- Documentation for additional income sources
- Proof of funds for the down payment and closing costs
Two years of employment or income history is commonly reviewed, although the exact documentation depends on your circumstances. CrossCountry Mortgage, for example, notes that lenders generally verify an income history of at least two years or qualifying school or military history.
Changing jobs does not automatically make you ineligible. The key issue is whether the lender can document stable and qualifying income under FHA underwriting rules.
How does DTI work?
Your debt to income ratio compares qualifying monthly debt obligations with gross monthly income.
For example:
Gross monthly income: $6,000
Qualifying monthly debts: $2,400
DTI: 40%
A common mistake is treating 43% as an absolute FHA maximum. That is too simplistic.
FHA loans can be evaluated through automated underwriting, including the FHA TOTAL Mortgage Scorecard, or through manual underwriting when applicable. The acceptable ratios and compensating factors can differ.
For manually underwritten loans, FHA’s framework includes specific housing and total debt ratio limits, with additional flexibility possible when qualifying compensating factors are present.
Original practical insight: A borrower with a 580 credit score and 40% DTI should not assume approval simply because both numbers appear acceptable. Underwriting also considers income stability, assets, payment history, liabilities, the property, and the overall strength of the file. In real applications, the interaction between these factors matters more than any single number.
What Property Requirements Must the Home Meet?
Qualifying for an FHA mortgage is only half of the process. The property must also qualify.
For a standard FHA purchase loan, the property generally needs to be the borrower’s primary residence and must meet applicable FHA property acceptability requirements. FHA financing can be used for eligible one to four unit properties, provided the borrower meets the occupancy and other program requirements.
Primary residence requirement
At least one borrower generally must occupy the property as their principal residence within 60 days of signing the security instrument and intend to continue occupying it for at least one year, subject to applicable exceptions.
That means a standard FHA loan is not designed for buying a vacation home or a pure investment property.
A multi unit property can be different. An eligible borrower may purchase a property with up to four units and occupy one unit as the principal residence.
FHA appraisal and property condition
An FHA appraisal does more than estimate value. The property must meet applicable FHA standards relating to safety, security, and structural soundness.
Potential issues can include:
- Roof condition
- Electrical systems
- Plumbing
- Utilities
- Water and drainage
- Structural concerns
- Safety hazards
- Certain property condition defects
The FHA appraisal should not be treated as a substitute for a private home inspection. A home inspection can provide a more detailed assessment of the home’s condition and potential future repair costs.
This distinction is important because a property can pass an FHA appraisal while still having problems that a buyer should understand before closing.
HUD was also reviewing FHA minimum property requirements in 2026, so buyers and real estate professionals should verify current requirements rather than relying on older checklists.
What Are the FHA Loan Limits for 2026?
FHA loan limits are not the same nationwide. They vary by location and property size.
For FHA case numbers assigned on or after January 1, 2026, the nationwide one unit limits are:
| Property size | 2026 low cost floor | 2026 high cost ceiling |
|---|---|---|
| One unit | $541,287 | $1,249,125 |
| Two units | $693,050 | $1,599,375 |
| Three units | $837,700 | $1,933,200 |
| Four units | $1,041,125 | $2,402,625 |
HUD establishes county and metropolitan area limits based on local home prices. The national one unit floor is $541,287, while the high cost ceiling is $1,249,125 for 2026.
So, if you are planning to buy a $700,000 home, do not assume that the FHA limit is $541,287 simply because that is the national floor. Your county could have a higher applicable limit.
Always check the FHA limit for the specific county and property type before making an offer.
How Does FHA Mortgage Insurance Affect Eligibility and Cost?
FHA loans require mortgage insurance, commonly called MIP, rather than conventional PMI.
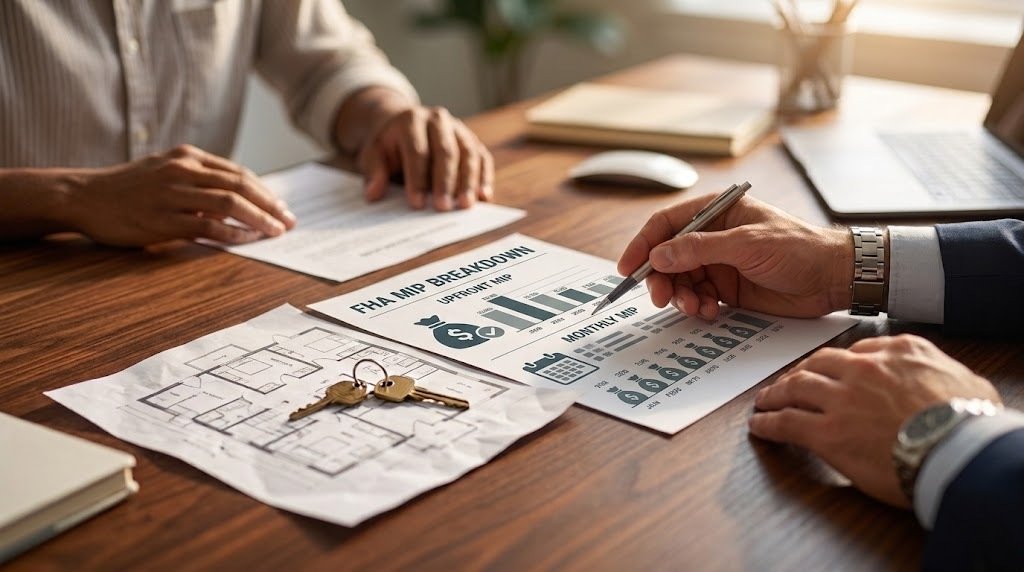
Most FHA forward mortgages have two components:
- Upfront Mortgage Insurance Premium
- Annual Mortgage Insurance Premium paid through monthly payments
HUD states that the standard upfront MIP for most FHA purchase and refinance transactions is 1.75% of the base loan amount. The annual MIP depends on factors such as loan term, loan amount, and loan to value.
The upfront premium may generally be financed into the mortgage instead of being paid entirely in cash at closing. However, financing it increases the loan balance and therefore increases borrowing costs.
This is one reason buyers should compare the total cost of FHA financing with conventional options instead of looking only at the minimum down payment.
For borrowers with lower credit scores or limited down payment funds, FHA can be attractive. For borrowers with stronger credit and more money available, a conventional mortgage may sometimes have a lower overall cost. The CFPB recommends comparing actual loan offers rather than assuming one program is always cheaper.
Other FHA Eligibility Requirements You Should Check
Your credit, income, debt, and property are not the only considerations.
Social Security number and legal eligibility
Your lender must be able to verify your identity and eligibility under current FHA rules. Current FHA policy also changed in 2025 regarding eligibility for certain non permanent residents, so borrowers with immigration or residency questions should confirm their status with an FHA approved lender using current HUD guidance rather than relying on older articles.
Federal debt
Delinquent federal debt or certain unresolved federal obligations can create problems during underwriting. Lenders may review federal debt and related records as part of the eligibility process.
Bankruptcy and foreclosure history
A past bankruptcy or foreclosure does not automatically mean you can never obtain an FHA loan. However, waiting periods, credit recovery, payment history, and the circumstances surrounding the event can affect eligibility.
Because these rules can become complicated, borrowers with recent bankruptcy, foreclosure, short sale, or major derogatory credit should have the lender review the complete timeline before submitting an offer.
Avoid major financial changes before closing
Getting pre approved does not mean you can stop monitoring your finances.
Before closing, avoid unnecessary actions such as:
- Opening new credit accounts
- Taking out a large personal loan
- Financing a vehicle
- Making unusually large purchases
- Missing payments
- Changing employment without discussing it with your lender
- Moving money between accounts without documentation
A lender may need to re verify your financial information before closing.
Complete FHA Loan Requirements 2026 Checklist
Use this checklist before applying:
- Credit score reviewed
- Down payment funds identified
- Gift funds documented if applicable
- Employment and income history documented
- Monthly debts calculated
- DTI reviewed
- Bank statements prepared
- Federal debt checked
- Bankruptcy or foreclosure history reviewed
- Primary residence confirmed
- Property type confirmed as FHA eligible
- 2026 county loan limit checked
- FHA appraisal requirements understood
- Home inspection considered
- Upfront and annual MIP included in affordability calculations
- Closing costs and prepaid expenses budgeted
- FHA approved lender selected
- Loan Estimate compared with other options
How to Prepare for an FHA Loan in 2026
A strong application starts before you submit the mortgage application.
Step 1: Review your credit
Check your credit reports and look for errors, missed payments, collections, or high balances.
Step 2: Calculate your real monthly budget
Do not calculate affordability using principal and interest alone. Include taxes, homeowners insurance, mortgage insurance, HOA fees when applicable, and other housing costs. The CFPB recommends considering the complete monthly housing payment when deciding how much home you can afford.
Step 3: Prepare your documentation
Gather income records, bank statements, identification, employment information, and documentation for any unusual deposits or financial events.
Step 4: Check the local FHA loan limit
Use HUD’s county level FHA loan limit tool before assuming the property price fits within FHA guidelines.
Step 5: Compare lenders
Different lenders can have different overlays, rates, fees, and underwriting practices. Comparing offers can help you understand the true cost of financing.
Step 6: Get pre approved before shopping seriously
A pre approval can help you understand your buying range and demonstrate that your finances have been reviewed before you make an offer.
FHA vs. Conventional: Which Is Better?
FHA is not automatically better than conventional financing.
FHA may make more sense when:
- Your credit profile is less than perfect.
- You have limited savings for a down payment.
- You need more flexible qualification options.
- You want to purchase an eligible primary residence with FHA financing.
Conventional financing may make more sense when:
- You have stronger credit.
- You can make a larger down payment.
- You want to minimize mortgage insurance costs.
- The property or transaction does not fit FHA requirements.
The right choice depends on the actual interest rate, fees, mortgage insurance, down payment, monthly payment, and long term cost. The CFPB recommends shopping and comparing loan offers rather than selecting a mortgage based on one feature alone.
Final Thoughts on FHA Loan Requirements 2026
FHA Loan Requirements 2026 are more than a 580 credit score and 3.5% down payment. Approval depends on the complete borrower profile, including credit history, income, debts, assets, occupancy, and the property itself.
The biggest 2026 update borrowers should know is the increase in FHA loan limits. The one unit national floor is now $541,287, while the ceiling is $1,249,125, with actual limits varying by location.
If you are planning to buy a home with FHA financing, start by reviewing your credit, calculating your complete monthly budget, checking your county’s FHA limit, and gathering your financial documents.
For the most accurate decision, speak with an FHA approved lender and compare the actual loan costs available for your situation.
FAQ Section
1. What is the minimum credit score for an FHA loan in 2026?
The standard FHA minimum credit score policy allows borrowers with scores of 580 or higher to qualify for maximum financing with a 3.5% minimum down payment. Scores from 500 to 579 are generally limited to 90% loan to value, requiring 10% down. Individual lenders may impose stricter requirements.
2. How much down payment do I need for an FHA loan in 2026?
With a qualifying credit score of at least 580, the standard minimum down payment is 3.5%. Borrowers with scores from 500 to 579 generally need 10% down. Eligible gift funds and qualifying assistance programs may help provide the required funds when properly documented.
3. What is the FHA DTI limit in 2026?
There is no single universal FHA DTI maximum that applies to every borrower. Automated and manual underwriting evaluate debt ratios differently, and the lender considers the complete application.
4. Can I use an FHA loan to buy a second home?
Generally, no. Standard FHA financing is intended for a principal residence. At least one borrower generally must occupy the property within 60 days and intend to continue occupying it for at least one year, subject to applicable exceptions.
5. What are the FHA loan limits for 2026?
For a one unit property, the 2026 FHA nationwide loan limit ranges from a $541,287 floor to a $1,249,125 ceiling. Actual limits depend on the property’s location and number of units.
6. Does every FHA loan require mortgage insurance?
Most FHA forward mortgages require an upfront mortgage insurance premium and an annual mortgage insurance premium paid through monthly payments. The exact annual premium depends on factors including loan term, loan amount, and loan to value.







One Response