
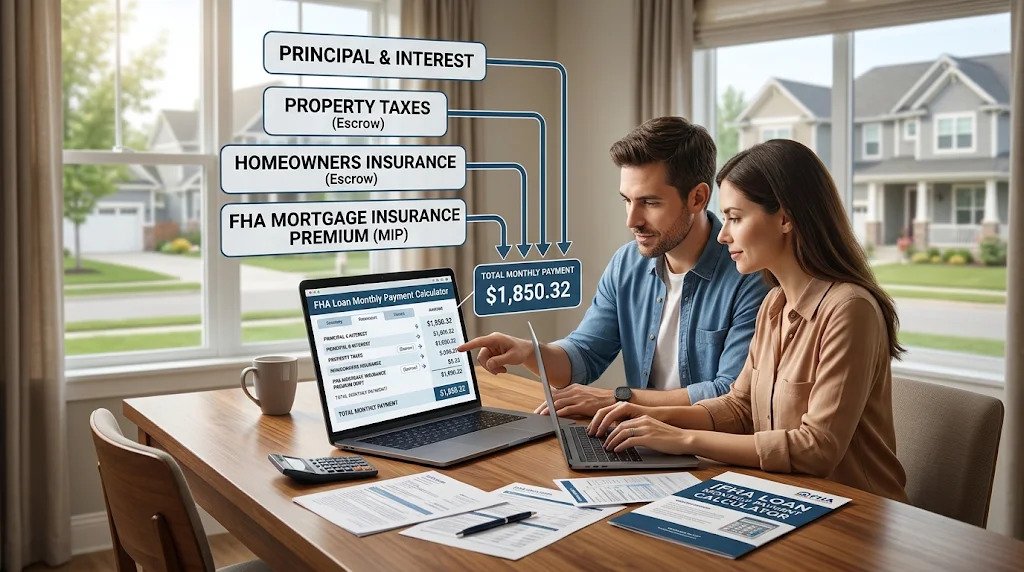

An FHA loan monthly payment calculator is the first tool most buyers reach for, and the one most buyers use wrong. Type in a home price and a rate, get a number back, and it feels like the answer. But that number is only real if it counts everything FHA adds on top of principal and interest.
This guide shows what the calculator should include, how each piece works, and what payments look like at different prices. Program figures come from current HUD rules for 2026, and rates shown are illustrations, not quotes.
What an FHA Loan Monthly Payment Calculator Should Tell You
A good FHA loan monthly payment calculator answers one question: how much leaves your bank account each month once you own the home? An FHA payment has five parts, not two. Principal and interest are only the start. Mortgage insurance, property taxes and homeowners insurance sit on top, and the insurance part is where FHA differs most.
Use one that asks for home price, down payment, rate, term, property tax and insurance. Some also ask for your county, since limits and tax rates change by location. Check it uses current rules: for 2026 the minimum down payment is 3.5 percent with a 580 credit score, and 10 percent for scores of 500 to 579.
The Five Parts of Your FHA Monthly Payment
Lenders shorten the payment to PITI: principal, interest, taxes and insurance. FHA adds a fifth piece, the annual mortgage insurance premium, so think of it as PITI plus MIP. Principal pays down the loan, interest is the cost of borrowing, and together they are fixed on a fixed rate loan, but they are only part of the bill.
MIP is the FHA insurance charge, and every FHA loan has it. The upfront premium of 1.75 percent is usually rolled into the loan. The annual premium is added monthly: 0.55 percent for most 30 year loans with less than 5 percent down, and 0.50 percent with 5 percent or more down. Taxes and insurance are usually collected monthly into escrow, so use your county rate and a real quote.
| Payment part | What it pays for | Does it change? |
|---|---|---|
| Principal | Paying down your loan balance | Grows over time |
| Interest | Cost of borrowing | Falls over time as the balance drops |
| Annual MIP | FHA mortgage insurance | Falls as the balance falls |
| Property taxes | County and local taxes | Can change yearly |
| Homeowners insurance | Cover for the home | Can rise yearly |
How Your Down Payment and the Upfront Premium Change the Loan
Your loan amount is not the home price minus the down payment. It is that figure plus the upfront premium, because almost every borrower finances it instead of paying cash at closing. On a $300,000 home with 3.5 percent down, the down payment is $10,500 and the base loan is $289,500. The upfront premium is 1.75 percent of that, or $5,066.25, making the total loan $294,566.25.
That extra $5,066 is borrowed money, and you pay interest on it for the life of the loan. For 2026, FHA insures one unit loans from $541,287 in lower cost counties to $1,249,125 in high cost counties, and your base loan must fit your county limit.

FHA Loan Monthly Payment Examples at Different Home Prices
The table below uses the same labelled assumptions: a 30 year fixed rate of 6.5 percent as an illustration, 3.5 percent down, annual MIP of 0.55 percent, and illustrative tax and insurance figures.
| Home price | Base loan | Total loan with upfront MIP | Principal and interest | Monthly MIP | Taxes and insurance (illustrative) | Estimated total |
|---|---|---|---|---|---|---|
| $250,000 | $241,250 | $245,472 | $1,552 | $111 | $375 | $2,038 |
| $300,000 | $289,500 | $294,566 | $1,862 | $133 | $450 | $2,445 |
| $400,000 | $386,000 | $392,755 | $2,483 | $177 | $600 | $3,260 |
Three things stand out. The upfront premium adds roughly $5,000 to $7,000 to the loan. MIP adds $111 to $177 a month and stays for the life of the loan at 3.5 percent down. Taxes and insurance are nearly one dollar in five: $450 of the $2,445 payment in the $300,000 example. With 10 percent down on a $350,000 home, the payment is about $2,682 and MIP ends after 11 years.
How the Interest Rate Moves Your FHA Monthly Payment
The rate moves your payment fastest, because it applies to the whole loan for 30 years. On the same $294,566 loan, one percentage point moves principal and interest by about $190 to $200 a month, or roughly $2,300 a year. Run the calculator at two rates, so a rate move does not break your budget.
| Illustrative interest rate | Monthly principal and interest | Difference from 6.5 percent |
|---|---|---|
| 5.5 percent | $1,673 | $189 less |
| 6.5 percent | $1,862 | Baseline |
| 7.5 percent | $2,060 | $198 more |
FHA Loan Monthly Payment: 30 Year Term vs 15 Year Term
Most buyers choose a 30 year term for the lower payment. But a 15 year term is worth a look: on the same $294,566 loan at 6.0 percent, principal and interest are about $2,486 a month against $1,862 on a 30 year term at 6.5 percent. That is $624 more a month, but the loan is gone in half the time with far less interest. The higher payment must still fit your debt to income ratio.
How to Use an FHA Loan Monthly Payment Calculator Step by Step
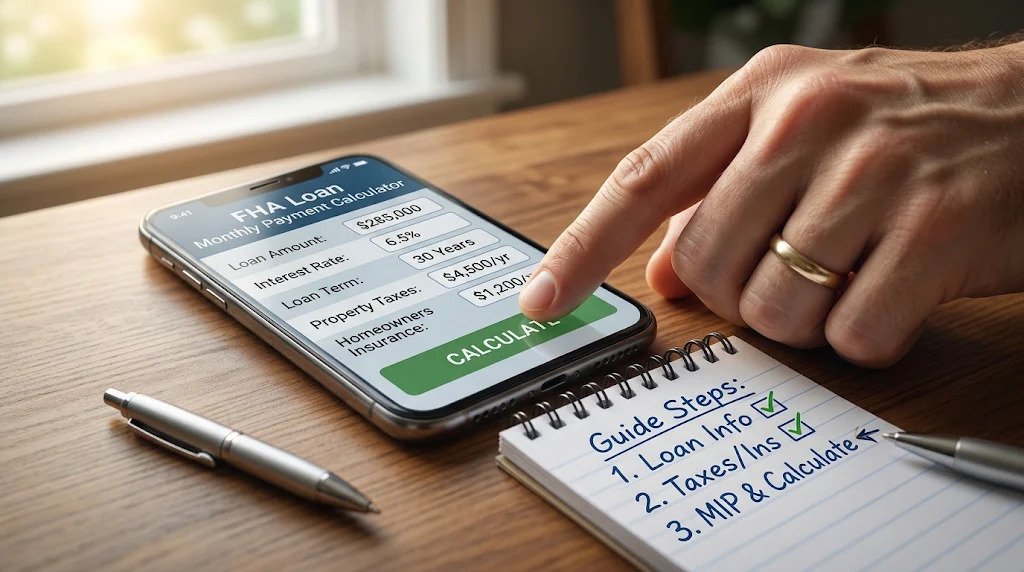
Start with a home price you can afford and enter the down payment in dollars, checking your score clears 580 for 3.5 percent down. Add the rate and the term, usually 30 years. Add the upfront premium of 1.75 percent to the loan and the annual MIP of 0.55 percent divided by 12. Then add property taxes and homeowners insurance from real figures, plus flood insurance if the home is in a flood zone. Read the result as a range and budget for the higher end of it.
Mistakes That Make Your FHA Monthly Payment Calculator Wrong
The most common mistake is treating principal and interest as the whole payment, when taxes, insurance and MIP can add 25 to 30 percent. Others are forgetting the upfront premium, using the list price instead of the lower of price and appraised value, and ignoring that MIP lasts for the life of the loan at 3.5 percent down. Closing costs are not in the payment at all, yet they decide whether you can close. See our guide to FHA loan closing costs for those figures.
Ways to Lower Your FHA Monthly Payment
A bigger down payment is the strongest lever: it shrinks the loan, cuts MIP to 0.50 percent at 5 percent down, and limits MIP to 11 years at 10 percent down. A lower rate is second, earned by improving your score and comparing three lenders. A cheaper home is third: $25,000 less cuts the payment by roughly $150 a month. Check homestead exemptions too, and consider refinancing later to remove MIP. See our guide to FHA mortgage insurance MIP cost.
What the Calculator Cannot Tell You
A calculator is a planning tool, not an approval. It cannot judge your credit history, income stability, debt to income ratio or the property itself. Test the edges: run the numbers at a higher rate and higher taxes, and make sure the payment still works. Our FHA loan down payment calculator guide covers the down payment side.
The Bottom Line on Your FHA Monthly Payment
Your real FHA monthly payment is principal, interest, mortgage insurance, property taxes and homeowners insurance together. Run the numbers with the 2026 rules, use real tax and insurance figures, and test a higher rate before you commit. The FHA program is described on Wikipedia, and HUD publishes the rules and loan limit lookup at HUD.gov and the HUD loan limits page.
What does an FHA loan monthly payment calculator include?
Principal, interest, annual MIP, property taxes and homeowners insurance. One showing only principal and interest misses parts that can add 25 to 30 percent.
How is the FHA monthly payment calculated?
Take the home price minus the down payment for the base loan, add the 1.75 percent upfront MIP, work out principal and interest from the rate and term, then add monthly MIP, taxes and insurance.
What is the minimum down payment for an FHA loan in 2026?
It is 3.5 percent with a credit score of 580 or higher, and 10 percent for scores of 500 to 579. Below 500, FHA does not insure the loan.
How much is FHA mortgage insurance per month?
For most 30 year loans with less than 5 percent down, annual MIP is 0.55 percent of the balance, divided by 12. On a $289,500 loan that is about $133 a month.
Does FHA MIP ever go away?
With less than 10 percent down, annual MIP lasts for the life of the loan. With 10 percent or more down, it drops off after 11 years.
What are the FHA loan limits for 2026?
For a one unit home, from $541,287 in lower cost counties to $1,249,125 in high cost counties. Your county limit sits somewhere in that range.
Are property taxes and insurance included in an FHA payment?
Yes, in most cases your lender collects them monthly into an escrow account and pays the bills for you.
What credit score do I need for the lowest FHA monthly payment?
A score of 580 or higher opens the 3.5 percent down payment, and a higher score generally helps you get a better rate.
Is a 15 year FHA loan payment much higher than a 30 year payment?
Yes. On a $294,566 loan, principal and interest are about $2,486 a month on a 15 year term at 6.0 percent, against about $1,862 on a 30 year term at 6.5 percent.
Can I use an FHA loan monthly payment calculator before I know my rate?
Yes, and you should. Run it at two or three illustrative rates to see how the payment moves, then get a real quote before you make an offer.
Does the upfront MIP have to be paid in cash at closing?
No. Most borrowers finance the 1.75 percent upfront premium into the loan. You can also pay it in cash, which keeps the loan smaller.
Why is my actual FHA payment higher than the calculator showed?
Usually it left out taxes, insurance or MIP, used an older MIP rate, skipped the upfront premium, or used a lower rate than the one you locked.
#FHALoan #FHALoanCalculator #MonthlyPayment #FHAMortgage #FirstTimeHomeBuyer #MortgageInsurance






